
- Home
- »
- Advanced Interior Materials
- »
-
Personal Protective Equipment Market Report, 2026-2033GVR Report cover

Personal Protective Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Head Protection, Hand Protection), By End Use (Healthcare, Manufacturing), By Region (North America, Asia Pacific, Europe, MEA, Latin America), And Segment Forecasts
Market Size, 2025
$90.4BMarket Estimate, 2026
$96.8BMarket Forecast, 2033
$159.8BCAGR, 2026–2033
7.4%Personal Protective Equipment Market Summary
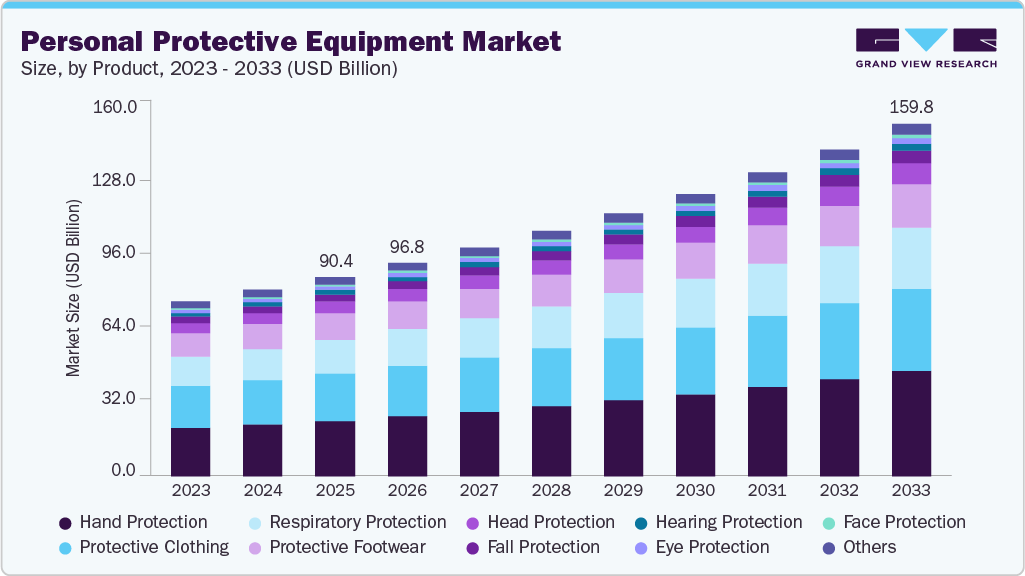
The global personal protective equipment market size was valued at USD 90.4 billion in 2025 and is projected to grow from USD 96.8 billion in 2026 to USD 159.8 billion by 2033, at a CAGR of 7.4% from 2026 to 2033. North America dominated the global market, accounting for a revenue share of 30.3% in 2025. Growing emphasis on employee health and safety, stricter workplace protection requirements, and increasing awareness of occupational hazards are strengthening demand for personal protective equipment (PPE) across industries.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Hand protection segment held the largest market share of 28.0% in 2025.
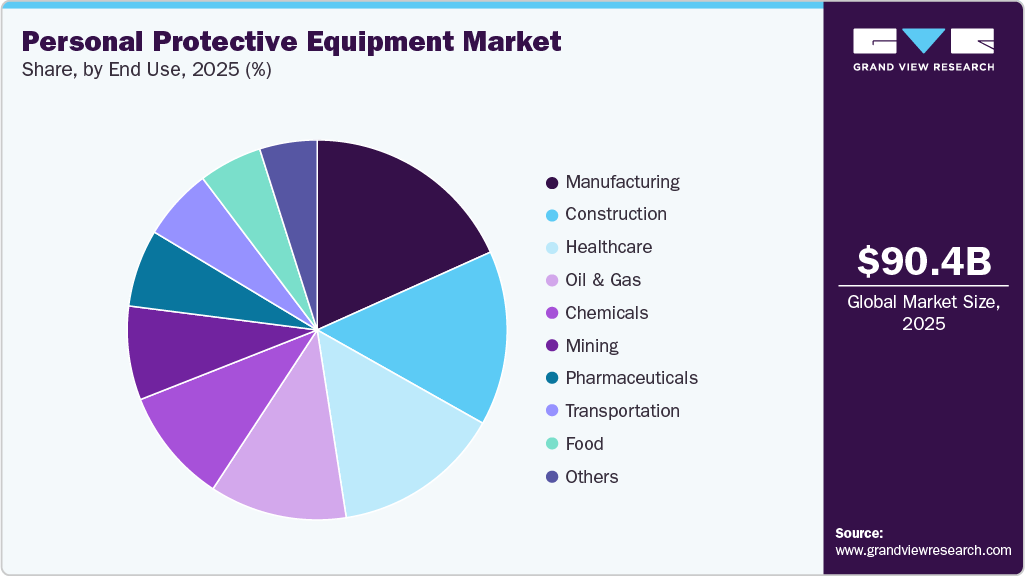
- By end use: Manufacturing segment held the largest market share of 18.3% in 2025.
Regional Highlights
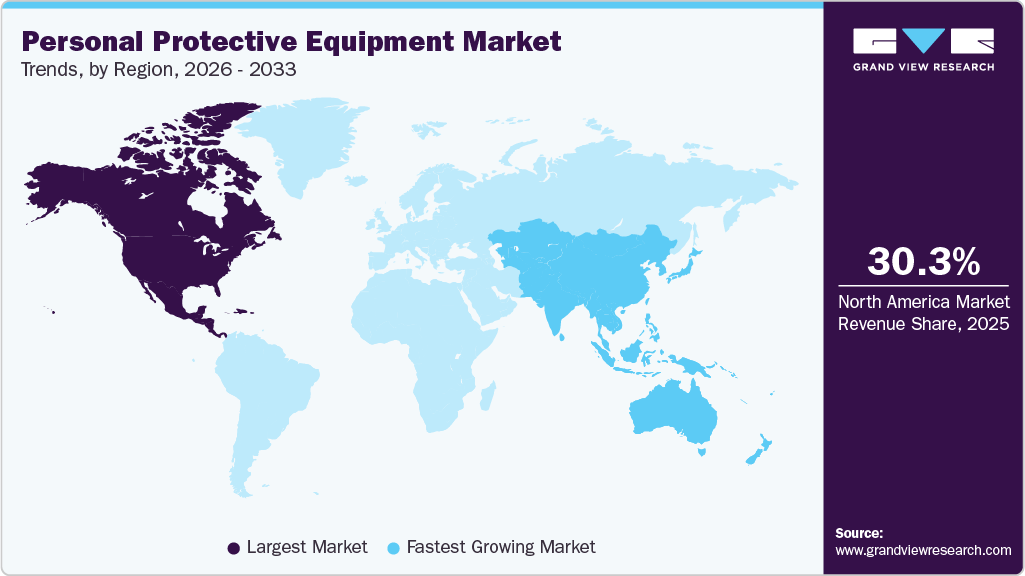
- Largest regional market: North America (30.3% market share, 2025)
- Fastest-growing market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 90.4 Billion
- Estimated market size in 2026: USD 96.8 Billion
- Projected market size by 2033: USD 159.8 Billion
- CAGR (2026-2033): 7.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Key Takeaways from the Report-
Manufacturers are focusing on advanced materials, ergonomic designs, improved comfort, and task-specific protection, while smart PPE is emerging as an area for technological differentiation.
-
Expansion across manufacturing, construction, oil & gas, chemicals, mining, and other high-risk industries is sustaining demand for application-specific protective equipment.
-
Increasing awareness of occupational hazards and stricter safety requirements are encouraging employers to adopt PPE more consistently across hazardous work environments.
-
Beyond traditional industrial applications, ongoing emphasis on infection control and worker protection is supporting demand for protective clothing, respiratory protection, and hand protection within healthcare environments.
-
Increasing workplace safety regulations, greater awareness of occupational hazards, and technological developments such as smart PPE with integrated sensors are supporting market expansion and product differentiation.
-
Emerging markets, particularly in Asia Pacific, are benefiting from expanding construction and manufacturing activity alongside stronger workplace safety frameworks, creating opportunities for PPE suppliers to broaden their presence.
The personal protective equipment (PPE) market is being driven by rising workplace safety awareness, stricter occupational health and safety regulations, and growing demand for specialized protection across high-risk industries. Increasing industrialization in emerging economies, expanding construction and manufacturing activities, and greater emphasis on worker well-being are supporting broader PPE adoption. In these markets, gaps in access to adequate protective equipment and persistent workplace hazards are creating additional opportunities for market expansion.
 To learn more about this report, Download Free Sample Report
Manufacturers are responding with application-specific solutions that enhance protection, comfort, and usability, while investing in lightweight materials, ergonomic designs, sustainable products, and smart PPE technologies with connected sensors. Compliance with standards established by bodies such as OSHA, NIOSH, and European safety authorities remains critical for market access. Although automation and engineering controls can reduce PPE requirements in certain applications, persistent industrial and biological hazards continue to sustain demand for reliable, high-performance protective solutions.
Market Dynamics
The global PPE market is influenced by expanding industrial activity, evolving workplace safety requirements, and increasing demand across high-risk and healthcare applications. Industrialization in Asia Pacific is strengthening demand for application-specific protective equipment, while healthcare infrastructure expansion in emerging economies is creating new avenues for growth. However, limited safety awareness, inconsistent regulatory enforcement, inadequate training, and resistance to PPE usage continue to constrain adoption in some markets. Technological advancements, improved product design, and stronger safety practices are expected to support long-term market development.
Ongoing industrialization across Asia Pacific is expected to remain a significant driver of PPE demand as expanding manufacturing, construction, mining, electronics, and infrastructure activities increase workforce exposure to occupational hazards. Strong industrial activity across the region, supported by growing demand from manufacturing and resource-intensive industries, is encouraging employers to strengthen workplace safety programs. At the same time, tighter safety regulations and greater awareness of occupational risks are driving investment in certified, application-specific PPE designed to protect workers from mechanical, chemical, thermal, and respiratory hazards.
Rising foreign investment, development of industrial parks, infrastructure projects, and the expansion of export-oriented manufacturing are further broadening the addressable market for PPE suppliers. In addition, governments and industrial operators are placing greater emphasis on occupational health and safety, encouraging the adoption of certified and application-specific protective equipment. The increasing presence of multinational manufacturers in the region is also likely to reinforce international safety practices and procurement standards. Consequently, continued industrialization, coupled with improving workplace safety awareness and regulatory enforcement, is expected to support sustained PPE adoption across Asia Pacific.
Limited awareness of occupational safety requirements and deliberate negligence in the use of PPE can constrain market penetration, particularly in developing and emerging economies. PPE is essential across high-risk industries such as manufacturing, oil & gas, chemicals, food & beverages, mining, and construction; however, availability alone does not ensure consistent usage. In markets where workplace safety awareness remains limited, workers may perceive protective equipment as uncomfortable, restrictive, or unnecessary, particularly when immediate hazards are not apparent. Employers may also reduce PPE spending where safety investments are viewed primarily as a cost rather than a means of preventing injuries, downtime, and potential liabilities.
Inconsistent enforcement of occupational safety regulations can weaken incentives for businesses to implement comprehensive PPE programs. Improper selection, inadequate training, poor fit, and failure to replace worn-out equipment can further reduce the effectiveness of protection. These factors can limit recurring demand for high-quality PPE and encourage the use of lower-cost alternatives. Strengthening worker education, employer accountability, regulatory enforcement, and safety training will therefore be important for overcoming this restraint and improving the adoption of personal protective equipment.
The expansion of healthcare infrastructure across emerging economies is creating significant opportunities for PPE manufacturers. Rising investments in hospitals, diagnostic laboratories, pharmaceutical facilities, and specialty clinics are increasing demand for surgical gloves, masks, respirators, gowns, face shields, and protective eyewear. Growing healthcare expenditure, urbanization, and improved access to medical services are further supporting adoption. Governments are also strengthening healthcare preparedness through disease surveillance, emergency response capabilities, and PPE stockpiling following recent infectious disease outbreaks. Meanwhile, stricter infection prevention and occupational safety requirements, alongside growth in pharmaceutical manufacturing, biotechnology, home healthcare, and ambulatory services, are broadening PPE applications beyond traditional hospital settings.
Analyst Perspective
In the coming years, the personal protective equipment market is expected to focus on performance, specialization, and technology-led differentiation. Manufacturers will increasingly prioritize lightweight, ergonomic, and durable products that enhance comfort without compromising protection, particularly in demanding industrial environments. Smart PPE incorporating sensors, connectivity, and real-time monitoring is expected to gain traction as employers seek greater visibility into worker safety and exposure risks. Sustainability will also become a stronger differentiator, encouraging recyclable materials, longer-lasting products, and lower-impact manufacturing. Companies with broad portfolios, regulatory expertise, reliable supply chains, and strong distribution networks will be positioned to serve diverse industries and regions. Customization and application-specific solutions will further support adaptation to evolving workplace hazards and safety requirements.
Product Insights
The hand protection segment dominated the personal protective equipment industry, accounting for a revenue share of 28.0% in 2025. The segment’s growth is primarily driven by the critical role of protective gloves in preventing hand injuries, including cuts, abrasions, burns, and chemical exposure. With rising safety regulations and heightened awareness of occupational hazards, demand for hand protection has surged across industries, including construction, oil & gas, food processing, healthcare, and metal fabrication. The need to safeguard workers from risks posed by hazardous chemicals, hot surfaces, and heavy machinery continues to reinforce the segment's dominant position in the broader PPE market. Increasing government efforts, coupled with the adoption of stringent regulations and safety guidelines for the use of hand protection equipment, are anticipated to positively impact the overall market growth over the forecast period.
The head protection segment is expected to grow at the fastest CAGR of 7.9% from 2026 to 2033, in terms of revenue. The head protection segment is driven by the growing construction activities in regions like Africa and Southeast Asia, where rising hazards such as falling objects increase the need for protective headgear. Hard hats are critical for reducing head injuries in industries including construction, mining, oil & gas, and manufacturing. North America is a mature market with strong demand for innovative, task-specific head protection products, and manufacturers focus on customization while facing intense competition.
Manufacturers are introducing helmets made from advanced thermoplastics and composite materials that provide higher impact resistance while reducing weight and improving ventilation. Modern designs increasingly incorporate adjustable suspension systems, integrated face shields, hearing protection compatibility, communication headsets, and mounting options for lights and sensors, making them suitable for digitally connected industrial workplaces. These factors collectively support the steady growth of the head protection market over the forecast period.
End Use Insights
The manufacturing segment dominated the personal protective equipment market, accounting for a revenue share of 18.3% in 2025. The manufacturing sector is one of the largest consumers of personal protective equipment (PPE) owing to the wide range of occupational hazards associated with industrial production processes. Routine exposure of the workforce to mechanical risks, pointed tools, operational equipment, chemical spills, airborne substances, significant noise, high heat, and electrical threats necessitates ongoing provision of protective gloves, safety footwear, protective clothing, eye and face protection, respiratory devices, hearing protection, and safety helmets.
PPE plays a critical role in minimizing workplace injuries while ensuring operational continuity and compliance with occupational health and safety regulations across manufacturing facilities. The continued expansion of global manufacturing activities, supported by investments in industrial automation, advanced manufacturing technologies, and production capacity expansion, is expected to sustain demand for PPE over the forecast period.
 To learn more about this report, Download Free Sample Report
The healthcare segment is expected to grow at the fastest CAGR of 10.4% from 2026 to 2033 in terms of revenue. Growth is supported by increasing emphasis on infection prevention, occupational safety, and protection of healthcare workers from infectious and hazardous exposures. Demand remains concentrated across protective clothing, respiratory protection, and hand protection, with healthcare facilities increasingly incorporating PPE into routine infection-control practices. Expansion of healthcare infrastructure and pharmaceutical and laboratory activities in emerging economies is further broadening the addressable market.
Continued focus on healthcare-associated infection prevention, outbreak preparedness, and standardized safety protocols is encouraging healthcare providers to maintain reliable supplies of protective equipment, supporting sustained demand beyond periods of acute health emergencies. Growing healthcare expenditure and continued investment in healthcare infrastructure are expected to sustain global demand for PPE. According to the U.S. Centers for Medicare & Medicaid Services (CMS), national health expenditures increased from USD 4.3 trillion in 2021 to USD 5.3 trillion in 2024, reflecting continued expansion in healthcare spending and demand for medical services. This growth, alongside investments in healthcare facilities and workforce capacity, is expected to support procurement of PPE across hospitals, laboratories, and other healthcare settings.
Regional Insights
The North America personal protective equipment market held the largest revenue share of 30.3% in 2025. The regional market is driven by significant growth in the oil & gas, chemical processing, and manufacturing sectors. A defining factor of the North American PPE landscape is the robust regulatory environment, spearheaded by agencies such as the Occupational Safety and Health Administration (OSHA) in the U.S. and the Canadian Centre for Occupational Health and Safety (CCOHS). These agencies have set comprehensive safety protocols that mandate the use of appropriate PPE in hazardous work environments, contributing significantly to sustained market growth.
 To learn more about this report, Download Free Sample Report
The personal protective equipment market in the U.S. is expected to grow at a CAGR of 7.9% over the forecast period, driven by increased oil and natural gas production fueled by technological advances in drilling and completion. Workers in this sector face significant risks, including chemical exposure, slips, and hand injuries, highlighting the need for durable PPE such as nitrile-based reusable gloves that provide chemical resistance and grip.
Asia Pacific Personal Protective Equipment Market Trends
The Asia Pacific personal protective equipment industry is anticipated to grow at the fastest CAGR of 8.7% over the forecast period. The rapid growth of the construction industry in Asia Pacific, driven by rising population needs and substantial investments in infrastructure across countries like China and India, is fueling the PPE demand. The region's cost-effective labor and strategic global supply chain position further support expansion across multiple sectors, including pharmaceuticals, healthcare, automotive, mining, and oil & gas. Strengthened legal and policy frameworks, such as stricter workplace safety inspections and mandatory PPE use, especially fall protection, are driving increased adoption of PPE. These factors collectively are expected to sustain strong PPE market growth in the Asia Pacific over the forecast period.
India’s personal protective equipment market is the fastest-growing market in the region with a projected CAGR of 10.4% over the forecast period. India’s strong economic growth and infrastructure expansion are driving increased demand for PPE in the construction and manufacturing sectors. Government initiatives like “Make in India” and stricter safety regulations bolster PPE adoption across industries, including automotive and electronics. Growing domestic demand is also encouraging PPE manufacturers to expand production capacity and strengthen their presence in key industrial hubs. In Jul 2026, Mallcom India announced an investment of approximately USD 11.5 million to expand its PPE manufacturing capabilities through its new Sanand facility in Gujarat. Rising workplace hazards and growing accident-related costs further emphasize the need for effective worker protection. Together, these factors are expected to sustain robust market growth.
Europe Personal Protective Equipment Market Trends
The personal protective equipment industry in Europe accounted for a revenue share of 29.7% in 2025. Europe represents a mature and highly regulated PPE market, characterized by a strong regulatory environment, high worker safety standards, and a growing emphasis on sustainable, technologically advanced protective solutions. The PPE demand is primarily generated across manufacturing, construction, healthcare, chemicals, transportation, mining, and food industries. Regulation (EU) 2016/425, whose consolidated version was updated in May 2026, establishes requirements for PPE design, manufacture, conformity assessment, and market placement.
Healthcare remains a stable and strategically important demand segment in the region, with the 2025 EU4Health program allocated approximately EUR 571.3 million (~USD 645.6 million), including about EUR 381.0 million (~USD 430.5 million), for crisis preparedness. The program specifically identifies reusable respiratory PPE and protective suits as priority products and includes an indicative EUR 20 million (~USD 22.6 million) call supporting preparedness against chemical and biological hazards. Combined with the EU’s 2025 stockpiling and medical countermeasures strategies, these measures are expected to support demand for respirators, protective gowns and suits, gloves, masks, goggles, and face shields across hospitals, laboratories, emergency response agencies, and strategic reserves.
Germany’s personal protective equipment market is projected to grow at a CAGR of 6.8% over the forecast period. Germany represents one of the largest and most advanced markets for personal protective equipment (PPE) in Europe, driven by its strong industrial base and rigorous workplace safety regulations. Key sectors in the country, including manufacturing, automotive, chemical, and construction, are substantial users of PPE and benefit from stringent regulation by bodies such as the German Social Accident Insurance (DGUV).
Middle East & Africa Personal Protective Equipment Market Trends
The Middle East & Africa personal protective equipment industry is anticipated to grow steadily at a CAGR of 6.6% over the forecast period. Robust demand for PPE in sectors such as construction, manufacturing, healthcare, and fire services is being driven by the burgeoning oil and gas industry and significant infrastructure investments in the Middle East and Africa. Stringent occupational health and safety regulations, rising awareness of workplace hazards, and expanding blue-collar workforces further boost PPE adoption across the region. Significant projects, including a USD 800 billion LNG expansion in Africa and nearly 700 healthcare developments in the UAE, are key growth drivers. Together, these factors are expected to sustain robust market growth.
The personal protective equipment (PPE) industry in the UAE is expected to grow at a CAGR of 7.5% over the forecast period, driven by a surge in construction and industrial investments aimed at economic self-sufficiency, including mega infrastructure projects like Masa Residence and new airport facilities in Abu Dhabi. In addition, stringent occupational health and safety requirements are encouraging employers to provide task-specific protective equipment and training. Continued investments in energy, manufacturing, logistics, and other industrial activities are expected to further expand the workforce exposed to occupational hazards, supporting sustained demand for PPE across the UAE.
Latin America Personal Protective Equipment Market Trends
The Latin America personal protective equipment industry is expected to grow at a CAGR of 7.9% over the forecast period, driven by expanding industrial and infrastructure activities across mining, oil & gas, construction, manufacturing, and healthcare.
Brazil is expected to remain a key regional market, supported by its diversified industrial base and workplace safety requirements. Increasing regulatory enforcement and awareness of occupational hazards are encouraging greater adoption of certified PPE, while growing demand for respiratory, hand, and application-specific protection is creating opportunities for market participants. E-commerce and expanding distribution networks are also improving product accessibility across the region.
Key Personal Protective Equipment Company Insights
The leading players in the personal protective equipment market are 3M, PIP, Uvex Safety, Mine Safety Appliances (MSA) Company, and Bullard. These companies focus on research and development activities, partnerships, collaborations, and acquisitions to develop and launch new products and gain a competitive edge in the market. In May 2025, Honeywell announced the completion of the sale of its Personal Protective Equipment (PPE) business to Protective Industrial Products, Inc. (PIP) for USD 1.325 billion in an all-cash transaction. PIP, a global manufacturer and supplier of PPE solutions, is backed by private equity firm Odyssey Investment Partners. This move boosts PIP’s global presence and safety product range. The acquisition strengthens its position as a top PPE provider worldwide.
Market players are also focusing on expanding product portfolios, strengthening distribution networks, and developing application-specific solutions to address evolving workplace safety requirements. Increasing emphasis on advanced materials, ergonomics, and smart PPE technologies is further shaping competitive differentiation across the market.
Key Personal Protective Equipment Companies
The following key companies have been profiled for this study of the personal protective equipment market.
-
3M
-
Lakeland Industries, Inc.
-
DuPont
-
PIP Global Safety
-
Alpha Pro Tech Limited
-
Ansell Ltd.
-
Avon Protection plc
-
MSA
-
Mallcom (India) Limited
-
Lindstrom Group
-
Delta Plus Group
-
Radians, Inc.
-
FallTech
-
COFRA S.r.l.
-
Polison Corp.
Recent Developments
-
In May 2026, Lindström expanded its presence in Poland with the acquisition of ORK Poland, a leading manufacturer of protective workwear. The acquisition enhances Lindström's in-house workwear production capabilities and supports its Strategy 2030 for long-term growth across Europe.
-
In February 2026, Avon Protection expanded its CBRN portfolio with the launch of the EXOSKIN-S2 protective suit for military personnel, first responders, and special forces. The new suit incorporates an activated carbon fabric inner layer to provide enhanced defense against aerosol, vapor, liquid, and particulate chemical threats during extended operations.
-
In June 2025, Ansell launched its new KIMTECH scientific PPE and BioClean cleanroom apparel at Interphex Tokyo 2025. The launch follows its acquisition of Kimberly-Clark’s PPE business in 2024. Orders are now open across the Asia Pacific region. Ansell aims to expand its presence in the pharma and semiconductor sectors through this launch.
-
In March 2024, FallTech launched the FT-Lineman Pro Body Belt. The latest utility belt breaks away from the conventional design and offers unmatched comfort, versatility, and lasting support. This new launch is likely to help the company strengthen its position in the personal protective equipment industry.
Value Chain Analysis
The key stages of the value chain of the personal protective equipment market are raw material/component suppliers, fabric suppliers, manufacturers, distributors, and end users. PPE production relies on materials such as polyamide, aramid, polyethylene, PVC, polycarbonate, nylon, metals, polymers, and specialized fabrics. Raw material suppliers convert these inputs into application-specific materials, while manufacturers transform them into PPE designed for mechanical, chemical, thermal, and other workplace hazards. Production is shaped by material innovation, safety standards, sustainability initiatives, and advanced technologies.
Distributors connect PPE manufacturers with end users across construction, manufacturing, healthcare, oil & gas, mining, chemicals, food, pharmaceuticals, transportation, and other sectors. E-commerce, established industrial distributors, retailers, and strategic partnerships are expanding product accessibility. End-user demand is driven by regulatory compliance, workplace safety awareness, industry-specific hazards, and increasing adoption of high-performance, application-specific PPE solutions.
Personal Protective Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 90.4 billion
Estimated market size in 2026
USD 96.8 billion
Projected market size by 2033
USD 159.8 billion
Growth rate
CAGR of 7.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; Italy; Spain; UK; Russia; Scandinavia; China; India; Japan; South Korea; Australia; Thailand; Malaysia; Indonesia; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
3M; Lakeland industries, Inc.; DuPont; PIP Global Safety; Alpha Pro Tech Limited; Ansell Ltd.; Avon Protection plc; MSA; Mallcom (India) Limited; Lindstrom Group; Delta Plus Group; Radians, Inc.; FallTech; COFRA S.r.l.; Polison Corp.
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Personal Protective Equipment Market Report Segmentation
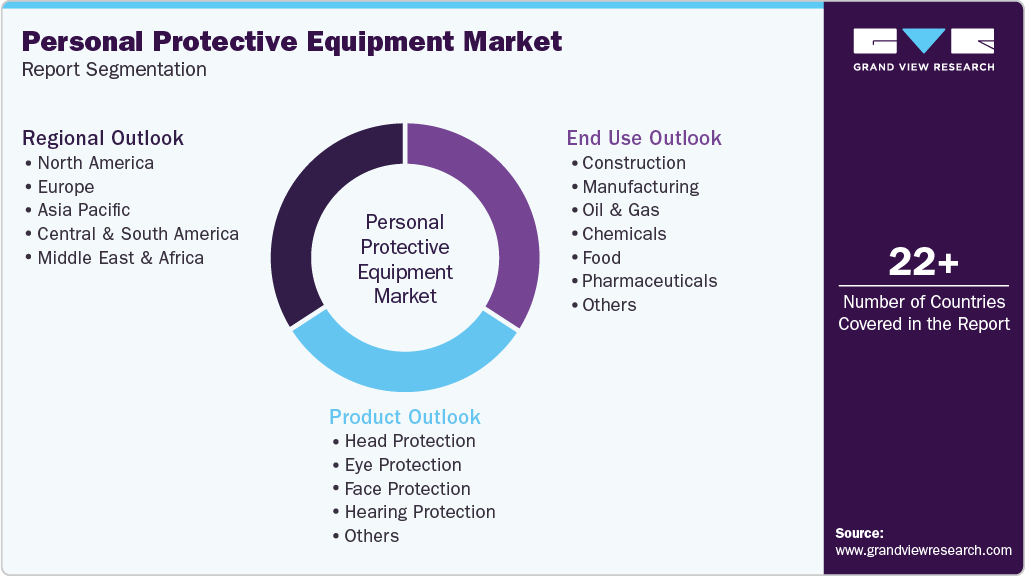
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the personal protective equipment market report based on product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Head Protection
-
Hard Hats
-
Bump Caps
-
-
Eye Protection
-
Safety Glasses
-
Goggles
-
-
Face Protection
-
Full Face Shields
-
Half Face Shields
-
-
Hearing Protection
-
Earmuffs
-
Earplugs
-
-
Protective Clothing
-
Heat & flame protection
-
Chemical defending
-
Clean room clothing
-
Mechanical protective clothing
-
Limited general use
-
Others
-
-
Respiratory Protection
-
Air-purifying respirator
-
Supplied air respirators
-
-
Protective Footwear
-
Leather
-
Rubber
-
PVC
-
Polyurethane
-
Others
-
-
Fall Protection
-
Soft Goods
-
Hard Goods
-
Others
-
-
Hand Protection
-
Disposable by Type
-
General purpose
-
Chemical handling
-
Sterile gloves
-
Surgical
-
Others
-
-
Disposable by Material
-
Natural Rubber
-
Nitrile
-
Vinyl
-
Neoprene
-
Polyethylene
-
Others
-
-
Durable
-
Mechanical gloves
-
Chemical handling
-
Thermal/flame retardant
-
Others
-
-
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Construction
-
Manufacturing
-
Oil & Gas
-
Chemicals
-
Food
-
Pharmaceuticals
-
Healthcare
-
Transportation
-
Mining
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
Spain
-
UK
-
Russia
-
Scandinavia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
Thailand
-
Malaysia
-
Indonesia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Scope & Research Methodology
The market study on the personal protective equipment market has been developed using a structured, multi-stage research framework designed to ensure accuracy, consistency, and reliability of the market size estimates and forecasts. The methodology combines quantitative modeling techniques with qualitative validation to arrive at a defensible view of market size, segmentation, and growth trends.
The personal protective equipment (PPE) market has been segmented on the basis of three parameters: product, end use, and region. In the first level, the market has been segmented into head protection, eye protection, face protection, hearing protection, protective clothing, respiratory protection, protective footwear, fall protection, hand protection and other products.
- Head Protection: Required to protect employees against hazards in industries such as construction, mining, oil & gas, and manufacturing.
- Hard Hats: Rigid helmets designed to protect the head from falling objects and impacts.
- Bump Caps: Lightweight helmets offering basic protection from bumps and scrapes, often used in areas with lower overhead hazards.
- Eye Protection: Devices used to protect employees against exposure to eye hazards from molten metal, suspended particles, liquid chemicals, chemical gases and vapors, acids and caustic liquids, or radiation.
- Safety Glasses: Eyewear with clear or tinted lenses to shield the eyes from dust, debris, splashes, and harmful light.
- Goggles: Tight-fitting eyewear that fully encloses the eye area for enhanced protection against splashes, impacts, and dust.
- Face Protection: Devices used in workplaces where there is a potential risk of facial injury due to cuts, sprays, mists, chemical vapors or gases, caustic liquids or acids, liquid chemicals, molten metal, flying particles, and light radiation.
- Full Face Shields: Transparent shields covering the entire face and protecting against splashes, impacts, dust, and some airborne hazards.
- Half Face Shields: Shields covering the lower half of the face and protecting against splashes and airborne hazards.
- Hearing Protection: Used when workplace noise cannot be reduced at the source. Hearing protection helps prevent occupational hearing loss. Common products include earmuffs and earplugs.
- Earmuffs: Ear cups connected by a headband to block out loud noise.
- Earplugs: Devices inserted into the ear canal to reduce noise levels.
- Protective Clothing: Segmented into heat and flame protection, chemical protection, cleanroom clothing, mechanical protective clothing, limited general use, and other protective clothing. Other protective clothing includes microbial protective clothing, gas-tight protective clothing, arc-flash protective clothing, thermal protective clothing, and cool suits.
- Heat & Flame Protection: Clothing made from fire-resistant materials to protect against burns and flames.
- Chemical Protection: Suits and garments designed to shield wearers from hazardous chemicals.
- Cleanroom Clothing: Garments designed to minimize particle contamination in cleanroom environments.
- Mechanical Protective Clothing: Clothing offering resistance to punctures, tears, or abrasion.
- Limited General Use: Clothing offering basic protection against dirt, dust, and light splashes.
- Others: Includes high-visibility vests, disposable coveralls, and arc-flash suits designed for specific electrical hazards.
- Respiratory Protection: Equipment designed to protect employees from dangerous dust, low-oxygen environments, smoke, fog, mists, vapors, gases, and sprays. Exposure to these hazards can cause cancer, illness, or even death.
- Air-Purifying Respirators: Masks equipped with filters that remove contaminants from inhaled air.
- Supplied-Air Respirators: Systems that provide clean air from a separate source, such as a compressed air tank.
- Protective Footwear: Includes boots and safety shoes worn by workers who may be exposed to the risk of foot injuries from rolling or falling objects.
- Leather: Protective footwear made from leather is valued for its durability, flexibility, and resistance to water and abrasion. It is commonly used in industries such as construction, manufacturing, and mining, where workers face hazards from heavy machinery, sharp objects, and electrical equipment.
- Rubber: Protective footwear made from rubber is valued for its waterproof and slip-resistant characteristics. It is widely used in sectors such as food processing and healthcare to protect against water, liquids, chemicals, and biological agents.
- PVC: Polyvinyl chloride (PVC) is a widely used material for protective footwear due to its durability, flexibility, and resistance to chemicals and abrasion.
- Polyurethane: Polyurethane footwear offers durability and resistance to chemicals, abrasion, and slips. It is commonly used in industrial environments where workers face risks of foot injuries from heavy machinery or falling objects.
- Others: Includes composite, nylon, and textile materials used in protective footwear.
- Fall Protection: Used to prevent injuries resulting from falls from elevated locations. It is further categorized into soft goods, hard goods, and others.
- Soft Goods: Typically include shock-absorbing lanyards, harnesses, body belts, and ropes designed to reduce the severity of falls.
- Hard Goods: Typically include anchors, carabiners, rope grabs, and retractable blocks.
- Others: Includes fall-arrest blocks, descent devices, and rescue equipment.
- Hand Protection: Required to protect employees against hand injuries caused by splinters, sharp edges, knives, blood and bodily fluids, hot objects, electricity, excessive vibrations, and extreme cold. It is further segmented into disposable and durable gloves.
- Disposable Gloves: Designed for single-use applications. They are typically thinner and less expensive than durable gloves and provide basic protection against dirt, dust, liquids, and chemicals. They are commonly used in food service, healthcare, cleaning, and light-duty industrial applications.
- Disposable Gloves by Material:
- Latex Rubber: A highly elastic natural material offering superior touch sensitivity. It is mainly used for medical and industrial applications.
- Vinyl: A synthetic material with limited durability, used in applications requiring lower levels of protection, such as the food industry.
- Neoprene: A synthetic rubber that offers resistance to refrigerants, oil, heat, flame, and abrasion.
- Nitrile: A synthetic rubber commonly used as an alternative to latex and offering high chemical resistance.
- Polyethylene: Provides cost-effective protection against fats, oils, mild chemicals, paints, and abrasions. It is used in industries such as food processing and farming.
- Others: Includes Tri-Polymer, polyisoprene, Norfoil, and Viton.
- Disposable Gloves by Type:
- General-Purpose Disposable Gloves: Versatile gloves used across various industries for a wide range of tasks, including food service, janitorial services, cleaning, hospitality, and light industrial applications.
- Chemical-Handling Disposable Gloves: Specifically designed to protect against chemicals such as acids, solvents, oils, and other hazardous substances.
- Sterile Disposable Gloves: Used in environments requiring aseptic conditions, including healthcare facilities, laboratories, and cleanroom environments.
- Surgical Disposable Gloves: Essential protective equipment used by healthcare professionals during surgical procedures to maintain sterility and prevent cross-contamination.
- Other Disposable Gloves: Includes food safety gloves, electrical safety gloves, and puncture-resistant gloves.
- Durable Gloves: Durable gloves are engineered for extended use in challenging environments and are designed to withstand repeated use while providing robust protection against various hazards. These gloves offer advantages such as strength, durability, and resistance to harsh working conditions, making them suitable for heavy-duty applications.
- Mechanical Durable Gloves: Designed for use in harsh environments, these gloves provide protection against mechanical hazards and are engineered to withstand repeated use. They offer strength, durability, and resistance to abrasion, cuts, punctures, and other mechanical hazards.
- Chemical-Handling Durable Gloves: Specifically engineered to protect workers against chemical hazards in various industrial settings. These gloves provide protection against corrosive substances, acids, solvents, and other hazardous chemicals.
- Flame-Retardant Durable Gloves: Used in industries such as firefighting, welding, oil & gas, and chemical manufacturing. These gloves provide protection against flames, heat, and other thermal hazards encountered in the workplace.
- Other Durable Gloves: Includes anti-vibration gloves, electrical gloves, and cut-resistant gloves.
- Others: Other personal protective equipment includes bouffant caps, hoods, beard nets/covers, and shoe/boot covers.
Based on end use, the market has been segmented into construction, manufacturing, oil & gas, chemicals, food, pharmaceuticals, healthcare, transportation, mining and other end use.
- Construction: Includes the application of PPE in building construction, heavy and civil engineering construction, and renovation and maintenance of buildings and other structures.
- Manufacturing: Includes the application of PPE in the production of goods or products through processes such as fabrication, assembly, raw material processing, and material handling. It encompasses industries such as automotive, electrical and electronics, textile, pulp and paper, and metal manufacturing.
- Oil & Gas: Includes the application of PPE across various activities in the oil and gas industry, such as exploration, extraction, transportation, refining, and distribution of natural gas and petroleum resources. It encompasses upstream and downstream operations.
- Chemicals: Includes the application of PPE in the production, processing, and distribution of chemicals.
- Food: Food processing facilities use PPE to maintain hygiene and prevent contamination. Examples include hairnets, protective clothing, gloves, safety glasses, and slip-resistant footwear.
- Pharmaceuticals: Similar to the food industry, pharmaceutical PPE focuses on hygiene and contamination control. Examples include cleanroom suits, gloves, safety glasses, respirators, and shoe covers.
- Healthcare: Healthcare workers require PPE to protect themselves and patients from bodily fluids, infectious diseases, and hazardous materials. Examples include gloves, gowns, masks, face shields, and safety glasses.
- Transportation: Includes the application of PPE in end uses involving the movement of people, goods, or materials from one location to another. It encompasses industries such as railways, maritime, and aviation.
- Mining: Includes the application of PPE in mining activities to protect workers from hazards associated with extraction, processing, handling, and transportation of minerals and other natural resources.
- Other End Use: Includes applications of PPE across industries and activities not covered under the above-mentioned end-use segments.
Based on region, the market has been segmented into North America, Europe, Asia Pacific, Latin America, and Middle East & Africa (with regional classification following UN M49 Standards).
- North America: The market has been segmented into the U.S., Canada, and Mexico.
- Europe: The market has been segmented into France, Germany, Italy, Russia, Scandinavia, the UK, Spain, and other countries.
- Asia Pacific: The market has been segmented into China, India, Japan, South Korea, Indonesia, Australia, Thailand, Malaysia, and other countries.
- Latin America: The market has been segmented into Argentina, Brazil, and other countries.
- Middle East & Africa: The market has been segmented into Saudi Arabia, the UAE, South Africa, and other countries.
- Regional Classification: The regional classification follows the United Nations (UN) M49 Standards.
The study began with secondary research to understand the market landscape, key trends, competitive dynamics, and historical data. Sources included company annual reports, investor presentations, regulatory filings, industry publications, government and trade databases, paid research platforms, press releases, and reputable trade publications. This phase also supported historical data mapping (2021 onward), the identification of key market participants, and the development of preliminary hypotheses regarding segment shares and regional trends, which were subsequently validated through primary research.
Market sizing was conducted using a combination of top-down and bottom-up approaches, with findings triangulated across secondary research, company-level data, industry sources, and market indicators to arrive at a converged and validated estimate.
Under the top-down approach, the broader personal protective equipment market was first assessed using industry reports, government statistics, construction and manufacturing activity, and macroeconomic indicators. The addressable market was then segmented based on product type, including head protection, eye protection, face protection, hearing protection, protective clothing, respiratory protection, protective footwear, fall protection, hand protection, and other PPE, as well as technology, application, end-use industry, and geographic region. Segment-specific penetration rates, adoption trends, and demand indicators were applied to derive market estimates across key segments and regions.
Under the bottom-up approach, market size was estimated by analyzing revenues and sales contributions of leading PPE manufacturers and major market participants across key product categories and regions. Company-level data, product portfolios, average selling prices (ASPs), unit volumes, distribution channels, and end-use demand were assessed and aggregated to develop segment- and region-level estimates.
The results from both approaches were cross-checked and reconciled through market-share analysis and industry-level triangulation to establish the final market size and forecast.
To validate and refine assumptions derived from secondary research and market modeling, structured primary interviews were conducted with a cross-section of personal protective equipment (PPE) industry stakeholders, including C-level executives and senior management at PPE manufacturers, product and R&D managers, distributors and channel partners, industrial and commercial end users, procurement and purchasing managers, and independent industry consultants and subject-matter experts. These interviews were used to validate market size estimates and growth assumptions, assess segment- and regional-level market shares, identify emerging product and technology trends, evaluate adoption drivers and barriers, and corroborate qualitative findings related to competitive positioning, pricing dynamics, distribution strategies, and end-user preferences.
All primary inputs were systematically triangulated against secondary data and the top-down/bottom-up model outputs. Where material inconsistencies arose, additional interviews or data points were sourced until a consistent, well-supported view was established, ensuring the final estimates reflect both quantitative rigor and real-world market intelligence.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Delivered an in-depth regional analysis covering North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, with detailed insights on market size, growth rates, demand patterns, regulatory environment, and country-level opportunities. The study also included analysis of construction activity, manufacturing expansion, infrastructure investments, workplace safety requirements, and PPE adoption trends across key economies.
Helped clients identify high-growth regions, prioritize market entry strategies, understand regional demand variations, and evaluate investment opportunities across developed and emerging markets. The analysis also supported distribution planning, product portfolio strategies, and regional expansion decisions.
Opportunity Assessment
Provided a comprehensive opportunity assessment focusing on high-growth segments such as protective clothing, respiratory protection, hand protection, protective footwear, fall protection, smart and connected PPE, and technologically advanced protective equipment. The study evaluated emerging application areas, technological advancements, evolving workplace safety requirements, and future adoption trends across construction, manufacturing, oil & gas, chemicals, healthcare, pharmaceuticals, mining, transportation, and other end-use sectors.
Enabled businesses to identify future revenue opportunities, develop targeted growth strategies, and align product development initiatives with evolving industry and workplace safety requirements. The assessment also supported long-term strategic planning and innovation-focused investments.
Competitive Benchmarking
Delivered a detailed competitive benchmarking analysis of major global and regional PPE manufacturers based on product portfolio strength, pricing strategies, innovation capabilities, distribution networks, geographic presence, strategic initiatives, and product and technological advancements.
Assisted clients in understanding competitor strengths, market positioning, and differentiation strategies while identifying potential gaps and areas for competitive advantage.
Frequently Asked Questions About This Report
The global personal protective equipment market size was estimated at USD 90.4 billion in 2025 and is expected to be USD 96.8 billion in 2026.
The North America personal protective equipment market dominated the market in 2025, accounting for 30.3% share driven by expanding oil & gas, chemical, and manufacturing sectors, alongside major investments in electric vehicle and infrastructure projects. Increasing industrial activity and the resulting need for worker safety are expected to sustain robust PPE demand across the region over the forecast period.
Rising workplace safety regulations, growing awareness of occupational hazards, and expanding industrial activities are the primary drivers of the global personal protective equipment (PPE) market. Additionally, increased investments in infrastructure, healthcare, and manufacturing sectors especially in emerging economies continue to fuel PPE demand worldwide.
Asia Pacific is the fastest-growing region over the forecast period.
Some of the key players operating in the global personal protective equipment market include 3M; Lakeland industries, Inc.; DuPont; PIP Global Safety; Alpha Pro Tech Limited; Ansell Ltd.; Avon Protection plc; MSA; Mallcom (India) Limited; Lindstrom Group; Delta Plus Group; Radians, Inc.; FallTech; COFRA S.r.l.; Polison Corp.
Hand protection led with over 28.0% share in 2025, while head protection segment is expected to grow at a considerable CAGR of 7.9%.
Manufacturing dominated with 18.3% share in 2025, while healthcare segment is expected to grow at a CAGR of 10.4%.
The global personal protective equipment market, in terms of revenue, is expected to grow at a compound annual growth rate of 7.4% from 2026 to 2033 to reach USD 159.8 billion by 2033.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


