
- Home
- »
- Pharmaceuticals
- »
-
Pharmaceutical Manufacturing Market Size Report 2026-2033GVR Report cover

Pharmaceutical Manufacturing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Route Of Administration (Oral, Topical), By Molecule, By Drug Development, By Sales Channel, By Therapy Area, By Prescription, By Age Group, By Formulation, By Region, And Segment Forecasts
Market Size, 2025
$616.2BMarket Estimate, 2026
$664.0BMarket Forecast, 2033
$990.6BCAGR, 2026–2033
5.8%Pharmaceutical Manufacturing Market Summary
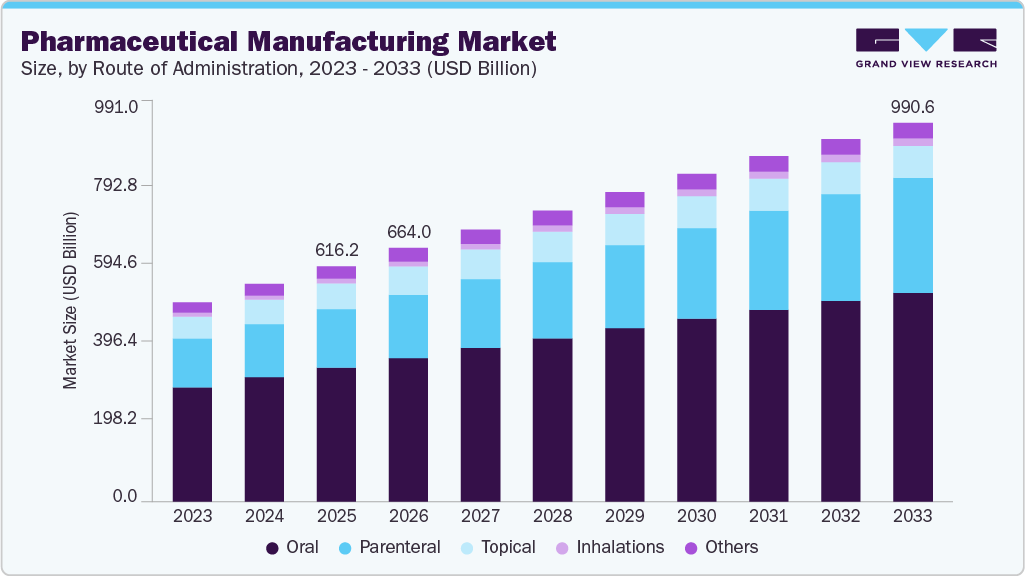
The global pharmaceutical manufacturing market size was valued at USD 616.1 billion in 2025 and is projected to grow from USD 664.0 billion in 2026 to USD 990.5 billion in 2033, at a CAGR of 5.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.2% in 2025. The market is driven by demand for advanced therapeutics, biologics, and high-volume generic drugs alongside increasing chronic disease prevalence and healthcare spending.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By molecule: The conventional drugs (small molecules) segment held the largest market share of 56.1% in 2025.
- By drug development: The outsourced segment held the largest market share in 2025.
- By formulations: The injectables segment held the largest market share of 25.9% in 2025.
Regional Highlights
- Largest regional market: North America (Approximately 40.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 616.1 Billion
- Estimated market size in 2026: USD 664.0 Billion
- Projected market size by 2033: USD 990.5 Billion
- CAGR (2026-2033): 5.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
With more patients and advanced treatments, demand for both traditional drugs and complex biologics has been increasing significantly. This has stimulated production scale ups and capacity enhancements among manufacturers, while ensuring consistent quality, safety, and compliance with regulatory frameworks. The increasing number of drug approvals by regulatory bodies is also expected to drive growth in drug manufacturing processes. In 2025, the FDA approved 32 novel drugs, indicating a positive trend.
A major driver supporting the market is the rapid evolution of drug development technologies. Increasing adoption of biologics, biosimilars, cell and gene therapies, and personalized medicines is reshaping production requirements, prompting manufacturers to invest in flexible, high-precision bioprocessing systems. At the same time, the shift toward continuous manufacturing and automation is helping companies reduce operational costs, optimize output, and improve product reliability, all of which are essential for meeting the rising global demand.
Analyst Perspective
The global market for pharmaceutical manufacturingis expected to experience noteworthy growth in the coming years, owing to increasing global demand for medicines, biologics, vaccines, and personalized healthcare therapies. Access to cutting-edge diagnostics and early detection is likely to drive a strong demand for effective pharmaceutical solutions. The growing prevalence of chronic diseases such as cancer, diabetes, cardiovascular diseases, and others has been generating increasing demand for chronic therapies, biologics, targeted cell & gene therapies, and integrated digital therapeutics (DTx), influencing the pharmaceutical manufacturing industry.
Advancements embraced by key companies, such as scaling AI applications from experimentation to enterprise scale, focusing on high-margin specialties instead of general pills, development of facilities dedicated to small-batch, localized production for gene therapies, and supply chain enhancements, are projected to add significant strength to the growth potential of this industry. Partnerships and collaborations are likely to result in shared know-how, improved competencies, and availability of expanded portfolios. Technology excellence, investments in R&D, and multiple government initiatives to eradicate specific conditions and improve healthcare access are anticipated to shape the further course of this market.
Molecule Insights
Based on molecule, the conventional drugs (small molecules) segment held the largest revenue share of 56.1% in 2025. According to a November 2022 NCBI study, small-molecule drugs represent up to 90.0% of total global drug sales in terms of units. These figures highlight a significant dominance of small molecules in the global pharmaceutical market. Recent drug approvals by regulatory bodies worldwide further support this trend. Out of the 50 new drugs approved by the U.S. FDA in 2024, 27 were small-molecule drugs, indicating their prominent position in the market.
The biologics & biosimilar (large molecules) segment is projected to grow at a significant CAGR during the forecast period. The segment growth is driven by increasing demand for advanced therapies targeting chronic and complex diseases. Investments by multiple global companies in manufacturing facility developments and enhancements are likely to support segment growth in the coming years. For instance, in March 2026, Samsung Biologics, one of the Contract Development and Manufacturing Organizations (CDMOs) from South Korea, acquired GSK’s Maryland, U.S.-based manufacturing facility comprising two cGMP manufacturing plants and 60,000-liter drug substance capacity, facilitating biologics production across various manufacturing scales. This has brought the total global manufacturing capacity of Samsung Biologics to 845,000 liters. These strategic advancements indicate the growing interest among manufacturers in this segment.
Drug Development Insights
The outsourced segment dominated the market in 2025, as more pharmaceutical companies turn to contract development and manufacturing organizations (CDMOs) to make drug development faster, lower costs, and speed up time-to-market. In April 2025, FUJIFILM Biotechnologies announced a 10-year manufacturing supply agreement with Regeneron Pharmaceuticals, Inc. This includes providing US-based production capabilities to Regeneron. Such developments highlight the critical role of this segment in market growth. CDMOs bring technical know-how, flexible capacity, and global supply-chain support. This lets pharma companies focus on core research and development while reducing operational risks, which is fueling steady growth in outsourced drug development and manufacturing.
The in-house segment is crucial for large pharmaceutical companies that require full control over their intellectual property, product quality, and regulatory compliance. Many large-scale drug manufacturers prefer in-house production to maintain control over confidential information related to novel molecules. The expansion of in-house manufacturing facilities by key firms is also contributing to the growth of the in-house segment. For instance, in February 2025, Eli Lilly announced a plan to construct four new domestic manufacturing sites in the U.S. to expand its production of APIs and injectable medicines. Such investments highlight an inclination among some of the U.S.-based manufacturers to establish in-house production facilities while focusing on reshoring the critical capabilities.
Formulation Insights
The injectables segment held the largest revenue share of more than 25.9% in 2025, primarily driven by the increasing use of biologics, the rising prevalence of chronic diseases, and the need for rapid and precise drug delivery. In addition, the expansion of self-administration devices such as prefilled syringes and auto-injectors has increased patient convenience and adoption in chronic disease management. For instance, in August 2025, the U.S. FDA approved a subcutaneous injectable version of the Alzheimer’s therapy Leqembi developed by Eisai and Biogen. The new formulation allows patients to receive weekly injections that can be administered at home, replacing earlier intravenous infusions that required hospital visits.
The sprays segment is expected to grow at the fastest CAGR during the forecast period, as more people seek non-invasive, easy-to-use drug-delivery options. Nasal and oral sprays offer rapid absorption, improved bioavailability, and greater convenience, which are especially helpful for managing chronic diseases, relieving pain, and delivering vaccines. The segment is also benefiting from advancements in metered-dose technologies, novel excipient systems, and the growing focus on self-administration therapies.
Route of Administration Insights
The oral segment dominated the market in revenue in 2025, as it is convenient, easy for patients to use, and works for many types of treatments. Tablets, capsules, and liquids are cost-effective to produce, use well-established manufacturing methods, and are easy to distribute on a large scale. This makes oral products the top choice for both prescription and over-the-counter medicines.
The parenteral segment is growing at the fastest CAGR over the forecast period, as more biologics, vaccines, and other treatments now require injection or infusion. Parenteral drugs work quickly, are highly potent, and allow for accurate dosing, which is important for cancer, autoimmune diseases, chronic conditions, and emergencies. This growth is also supported by more sterile manufacturing sites, better prefilled syringes and autoinjectors, and a move toward self-injection and home care. As more new drugs are large molecules or specialty products, parenteral formulations are expected to keep growing strongly.
Therapy Area Insights
The other diseases segment accounted for the largest revenue share of over 61.0% in 2025, reflecting the broad and diverse range of therapeutic areas. This segment includes therapies for neurological, gastrointestinal, infectious, skin, autoimmune, and rare diseases, all of which add to the overall demand for pharmaceuticals. Its strong position comes from a large patient base, ongoing new therapies, and steady use of specialty and long-term care medicines. Improvements in drug delivery, better insurance coverage, and more awareness about early treatment also help keep this segment growing.
The respiratory diseases segment is expected to grow at the fastest CAGR over the forecast period. This is due to more cases of asthma, COPD, allergies, and respiratory infections in both developed and developing countries. Factors such as higher pollution, urban living, lifestyle changes, and greater awareness of respiratory health after the pandemic are increasing the need for inhalers, nebulizers, combination drugs, biologic treatments, and preventive medicines.
Prescription Insights
The prescription medicine segment held the largest revenue share in 2025. The segment is expected to grow in the coming years with the increasing number of people suffering from chronic and complex diseases. The segment covers high-value biologics, specialty drugs, and advanced treatments, all of which require strict clinical testing, regulatory approval, and specialized manufacturing.
The over-the-counter (OTC) medicines segment is growing steadily in the coming years as they offer cost and time efficiency compared to prescription medicines. More people are choosing self-care, becoming aware of preventive health, and finding OTC products easily in stores and online.
Age Group Insights
The geriatric segment dominated the market in 2025. According to the World Health Organization (WHO), by 2030, one in six people globally will be aged 60 or older, with the population in this group marking increase from 1.0 billion in 2020 to 1.4 billion in 2030. With the growing elderly population, age-related conditions such as heart disease, diabetes, arthritis, neurodegenerative disorders, and cancer are also becoming common. They often need long-term medication and several drug therapies, which raises demand for prescription drugs, specialty treatments, and supportive care products.
The children & adolescents segment is expected to grow rapidly over the forecast period. This growth comes from a stronger focus on pediatric healthcare, more cases of infectious and lifestyle-related conditions, and stricter rules for approving pediatric drugs. Manufacturers are making more child-friendly products, such as flavored syrups, chewable tablets, and easy-to-use delivery systems, to make treatments safer and easier for children.
Sales Channel Insights
The retail segment dominated the market and accounted for a revenue share in 2025, driven by easy access to community pharmacies, drugstores, and supermarket pharmacy counters. Most people buy both prescription and over-the-counter medicines through these retail channels as they are convenient, offer good pharmacist-patient interaction, and have a wide range of products. With the rise in medical costs and health insurance premiums, more individuals are opting for self-medication to address minor health issues. This segment also benefits from more customers visiting stores, better distribution networks, and improved inventory management.
The non-retail segment, which covers hospital pharmacies, clinics, and specialty care centers, is growing as more people need advanced therapies and complex treatments. This channel is important for giving high-value biologics, injectables, specialty drugs, and acute-care medicines that need professional supervision and controlled settings. Growth is also helped by more hospitalizations, better healthcare infrastructure, and greater use of specialty pharmacy services.
Regional Insights
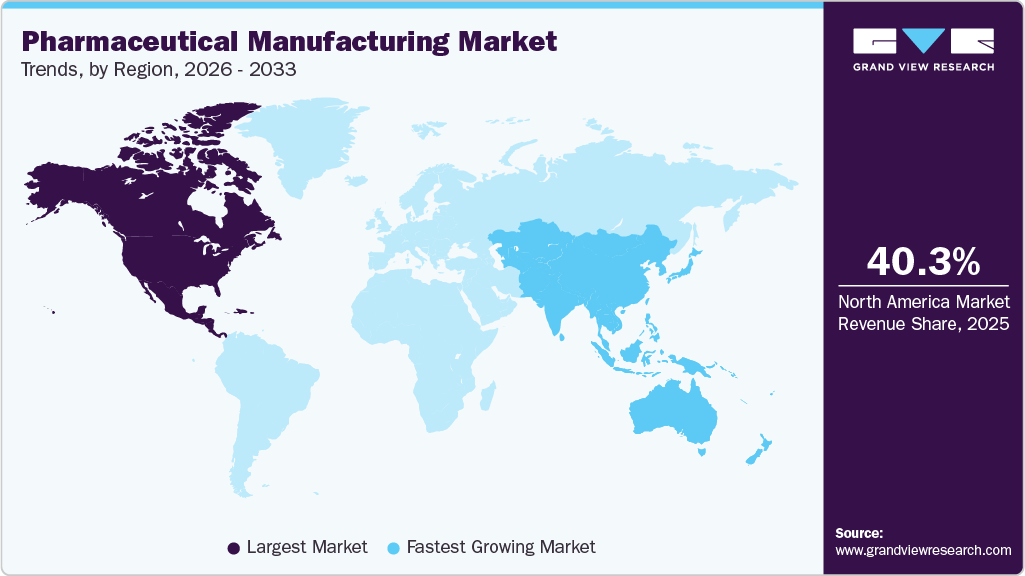
The North America pharmaceutical manufacturing industry held the largest revenue share in 2025 and accounted for more than 40.0% in 2025, driven by advanced production facilities, strong research and development, and a well-established regulatory system that supports innovation. Increasing investments in this region are likely to facilitate market growth during the forecast period. For instance, in April 2026, Novartis AG announced its plans to establish a new 56,200-square-foot facility in North Carolina, U.S., focusing on manufacturing of active pharmaceutical ingredients (APIs).
 To learn more about this report, Download Free Sample Report
U.S. Pharmaceutical Manufacturing Market Trends
The U.S. pharmaceutical manufacturing industry accounted for the largest share in North America in 2025, driven by a strong biotech sector, active clinical research, and high spending on specialty treatments. Leading companies and CDMOs are investing in large-scale biologics and sterile manufacturing plants. Government support, new patents, and growing demand for advanced therapies also help the region grow. Investments in pharmaceutical manufacturing and associated activities, such as packaging across the U.S., highlight the growth potential of this industry. Regulatory support and government initiatives in the country also contribute to the market growth. For instance, in February 2026, the U.S. FDA, announced commencement of accepting applications to participate in the its PreCheck pilot program. Phase I of the FDA PreCheck pilot program is set to select participants engaged in development of new pharmaceutical manufacturing facilities in the U.S., and begin conducting FDA PreCheck in 2026. Companies designated for the program are going to get benefits from communication and feedback program by the FDA during the facility development.
Europe Pharmaceutical Manufacturing Market Trends
The pharmaceutical manufacturing industry in Europe represented a significant market growth in 2025, supported by strong regulatory standards, a well-established pharmaceutical industry, and increasing emphasis on quality manufacturing practices. Countries such as Germany, Switzerland, and the UK serve as major production hubs for biologics and specialty drugs.
Asia Pacific Pharmaceutical Manufacturing Market Trends
The pharmaceutical manufacturing industry in the Asia Pacific is expected to grow at the fastest CAGR during the forecast period, driven by expanding healthcare infrastructure, rising local production capabilities, and increasing government support for domestic pharmaceutical manufacturing. The region benefits from rapid industrialization and growing demand for generics and biosimilars. International companies are also forming strategic partnerships to leverage regional capacity and strengthen supply chain flexibility.
China pharmaceutical manufacturing industry held the largest revenue share in the Asia-Pacific region, driven by strong government incentives, expanding biologics production, and significant investments in advanced manufacturing technologies. The country is rapidly increasing its capabilities in APIs, generics, and high-value biologics. Improved regulatory reforms and rising domestic healthcare demand continue to accelerate market growth.
The pharmaceutical manufacturing industry in India plays a crucial role in global pharmaceutical supply, particularly in generics and bulk drug manufacturing, supported by competitive costs and a strong base of skilled professionals. Government initiatives to boost API self-reliance and expand biopharmaceutical production are strengthening the country’s manufacturing capabilities.
Latin America Pharmaceutical Manufacturing Market
The pharmaceutical manufacturing industry in Latin America is growing due to rising healthcare demand, increasing prevalence of chronic diseases, and strong expansion of generic drug production. Countries such as Brazil and Mexico are emerging as regional manufacturing hubs as governments promote local drug production and attract foreign investment. In addition, cost advantages compared with North America and Europe are encouraging multinational pharmaceutical companies to outsource manufacturing and contract development activities to the region. The growing adoption of biologics and biosimilars, along with expanding middle-class populations and improving healthcare infrastructure, is further supporting pharmaceutical production and export capabilities across LATAM.
MEA Pharmaceutical Manufacturing Market Trends
The pharmaceutical manufacturing industry in the Middle East & Africa is expanding due to strong government initiatives aimed at improving healthcare access and reducing reliance on imported medicines. Many countries are investing in domestic manufacturing infrastructure, promoting generic drug production, and supporting partnerships with contract development and manufacturing organizations (CDMOs). The rising burden of chronic diseases such as cancer and diabetes, combined with growing healthcare expenditure and population growth, is also increasing demand for locally produced medicines. In addition, national strategies such as localization policies and healthcare modernization programs in countries like Saudi Arabia and Egypt are accelerating investment in pharmaceutical manufacturing facilities and biopharmaceutical capabilities across the region.
Key Pharmaceutical Manufacturing Company Insights
Leading companies in the industry have implemented strategic initiatives to enhance their market presence and gain a competitive advantage. These key players are actively involved in various activities, such as product development, collaboration & partnership models, agreements, business expansion, and mergers & acquisitions. These initiatives aim to strengthen their product portfolio and meet the growing demand for pharmaceutical products.
- Pfizer, Inc. is a leading global biopharmaceutical company known for its extensive portfolio spanning vaccines, oncology, immunology, and rare diseases, supported by strong R&D capabilities and large-scale manufacturing. The company continues to invest in innovative therapies and strategic collaborations to strengthen its global healthcare impact.
Key Pharmaceutical Manufacturing Companies
The following key companies have been profiled for this study on the pharmaceutical manufacturing market:
-
F. Hoffmann-La Roche Ltd.
-
Novartis AG
-
GSK plc
-
Pfizer, Inc.
-
Merck & Co., Inc.
-
AstraZeneca
-
Johnson & Johnson
-
Sanofi SA
-
Eli Lilly and Company
-
AbbVie, Inc.
-
Thermo Fisher Scientific, Inc.
-
Wuxi Apptec
-
Samsung Biologics
-
FUJIFILM Biotechnologies
-
Lonza
-
Catalent, Inc.
-
Jubilant Pharmova Limited
Recent Developments
-
In February 2026, Novo Nordisk A/S announced plans to significantly expand its global manufacturing capacity for GLP-1 drugs, including semaglutide-based therapies such as Ozempic and Wegovy, to address growing global demand for diabetes and obesity treatments.
-
In January 2026, Pfizer Inc. announced investments to expand sterile injectable manufacturing capabilities at its U.S. facilities, aimed at strengthening supply chain resilience and supporting the production of complex injectable medicines.
-
In August 2025, BioMed X and Novo Nordisk collaborated to develop novel oral formulation technologies enabling site-specific, prolonged peptide drug retention in the lower small intestine.
Pharmaceutical Manufacturing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 616.1 billion
Estimated market size in 2026
USD 664.0 billion
Projected market size by 2033
USD 990.5 billion
Growth rate
CAGR of 5.8% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Molecule, drug development, formulation, route of administration, therapy area, prescription, age group, sales channel, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
F. Hoffmann-La Roche Ltd.; Novartis AG; GSK plc; Pfizer, Inc.; Merck & Co., Inc.; AstraZeneca; Johnson & Johnson; Sanofi SA; Eli Lilly and Company; AbbVie, Inc.; Thermo Fisher Scientific, Inc.; Wuxi Apptec; Samsung Biologics; FUJIFILM Biotechnologies; Lonza; Catalent, Inc.; Jubilant Pharmova Limited
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Pharmaceutical Manufacturing Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pharmaceutical manufacturing market report based on molecule, drug development, formulation, route of administration, therapy area, prescription, age group, sales channel, and region:
-
Molecule Outlook (Revenue, USD Billion, 2021 - 2033)
-
Biologics & Biosimilars (Large Molecules)
-
Monoclonal Antibodies
-
Vaccines
-
Cell & Gene Therapy
-
Others
-
-
Conventional Drugs (Small Molecules)
-
-
Drug Development Outlook (Revenue, USD Billion, 2021 - 2033)
-
In-house
-
Outsource
-
-
Formulation Outlook (Revenue, USD Billion, 2021 - 2033)
-
Tablets
-
Capsules
-
Injectable
-
Sprays
-
Suspensions
-
Powders
-
Other Formulations
-
-
Route of Administration Outlook (Revenue, USD Billion, 2021 - 2033)
-
Oral
-
Topical
-
Parenteral
-
Inhalations
-
Other Routes of Administration
-
-
Therapy Area Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cardiovascular Diseases (CVDs)
-
Pain
-
Diabetes
-
Cancer
-
Respiratory Diseases
-
Other Diseases
-
-
Prescription Outlook (Revenue, USD Billion, 2021 - 2033)
-
Prescription Medicines
-
Over-the-counter (OTC) Medicines
-
-
Age Group Outlook (Revenue, USD Billion, 2021 - 2033)
-
Children & Adolescents
-
Adults
-
Geriatric
-
-
Sales Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Retail
-
Non-retail
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Norway
-
Denmark
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
Key factors that are driving the pharmaceutical manufacturing market growth include the rise in pharmaceutical R&D spending, advancements in technologies, rise in focus towards healthcare needs of emerging nations, and growth in the geriatric population and incidence rate of chronic disorders.
The global pharmaceutical manufacturing market size was valued at USD 616.2 billion in 2025 and is estimated at USD 664.0 billion for 2026.
The global pharmaceutical manufacturing market is expected to grow at a CAGR of 5.8% from 2026 to 2033, reaching USD 990.5 billion by 2033.
Some key players operating in the pharmaceutical manufacturing market include F. Hoffmann-La Roche Ltd.; Novartis AG; GSK plc; Pfizer, Inc.; Merck & Co., Inc.; AstraZeneca; Johnson & Johnson; Sanofi SA; Eli Lilly and Company; AbbVie, Inc.; Thermo Fisher Scientific, Inc.; Wuxi Apptec; Samsung Biologics; FUJIFILM Biotechnologies; Lonza; Catalent, Inc.; Jubilant Pharmova Limited
North America dominated with a 40.2% revenue share in 2025.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


