
- Home
- »
- Plastics, Polymers & Resins
- »
-
Plastic Recycling Services Market Size Report, 2026-2033GVR Report cover

Plastic Recycling Services Market (2026 - 2033)
Size, Share & Trends Analysis Report By Process (Mechanical Recycling, Chemical Recycling), By Type (Plastic Bottles, Plastic Films, Polymer Foam), By Region, And Segment Forecasts
Market Size, 2025
$13.8BMarket Estimate, 2026
$15.3BMarket Forecast, 2033
$36.4BCAGR, 2026–2033
13.2%Plastic Recycling Services Market Summary
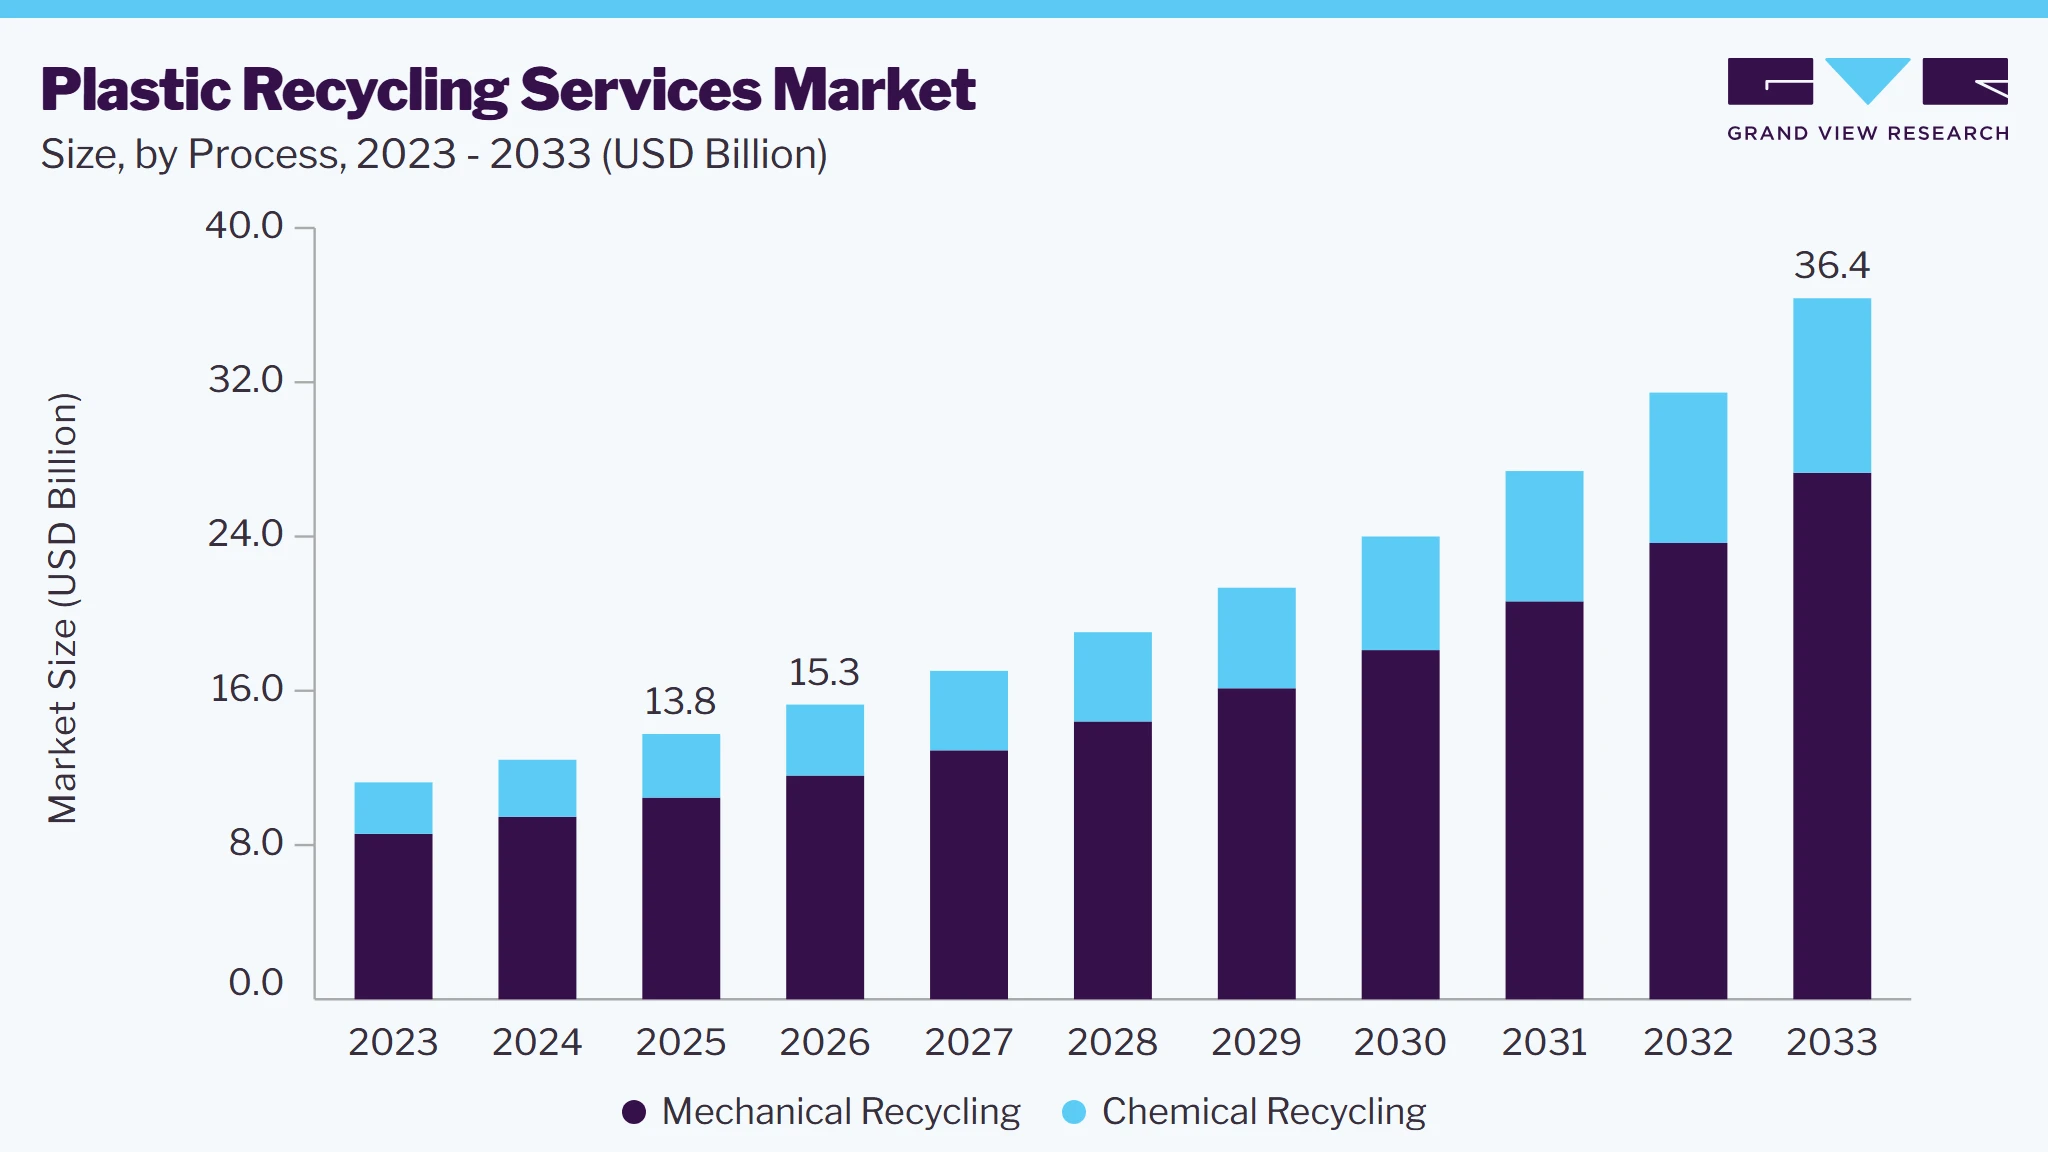
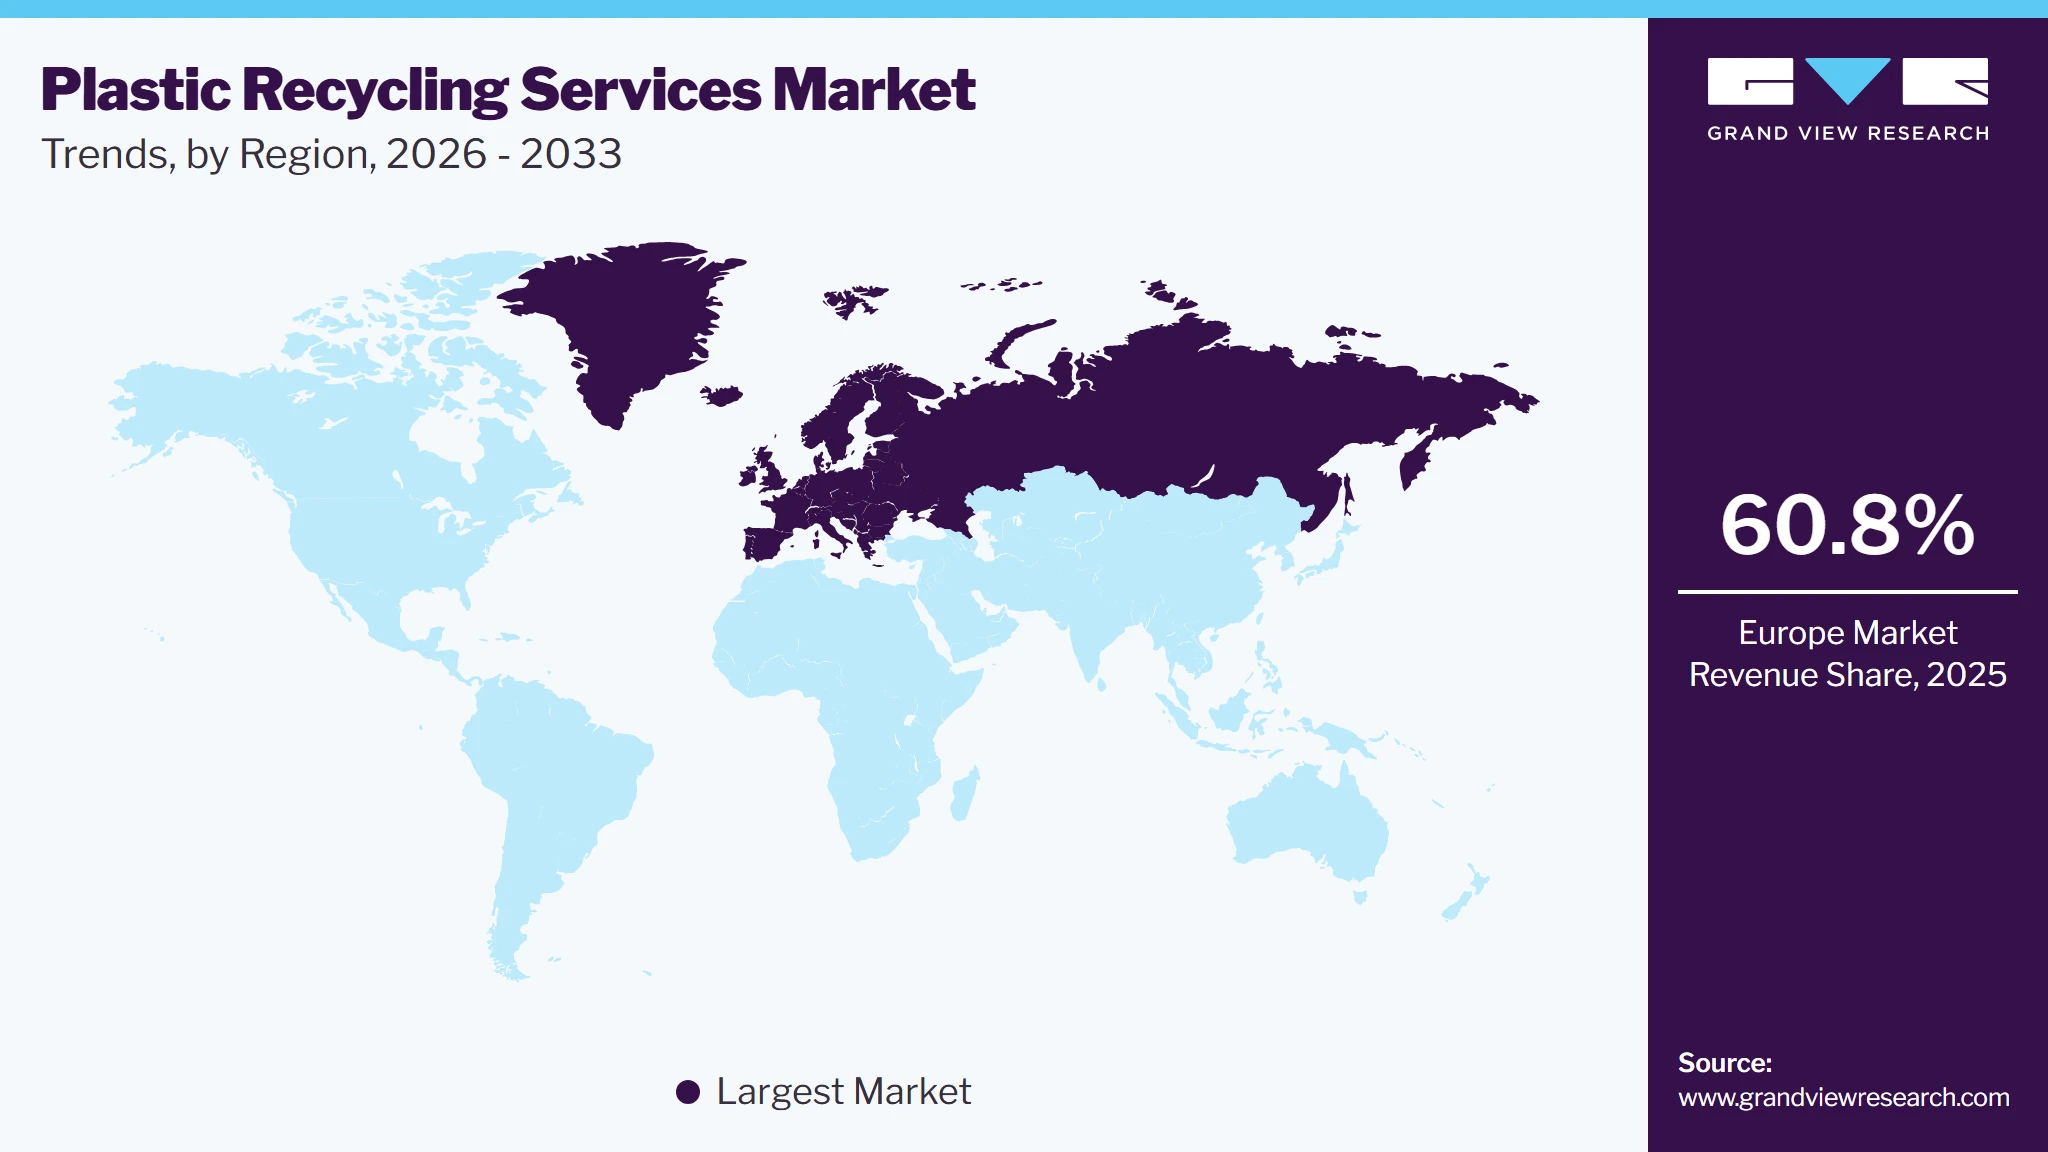
The global plastic recycling services market size was estimated at USD 13.8 billion in 2025 and is projected to grow from USD 15.3 billion in 2026 to USD 36.4 billion by 2033, growing at a CAGR of 13.2% from 2026 to 2033. In terms of region, Europe dominated the global plastic recycling services market and accounted for the largest revenue share of 60.8% in 2025. The global plastic recycling services market is driven by the rising threat of non-degradable plastic pollution, increasing the need for effective waste management and environmental protection.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By process: Mechanical recycling segment led the market with the largest revenue share of 76.0% in 2025.
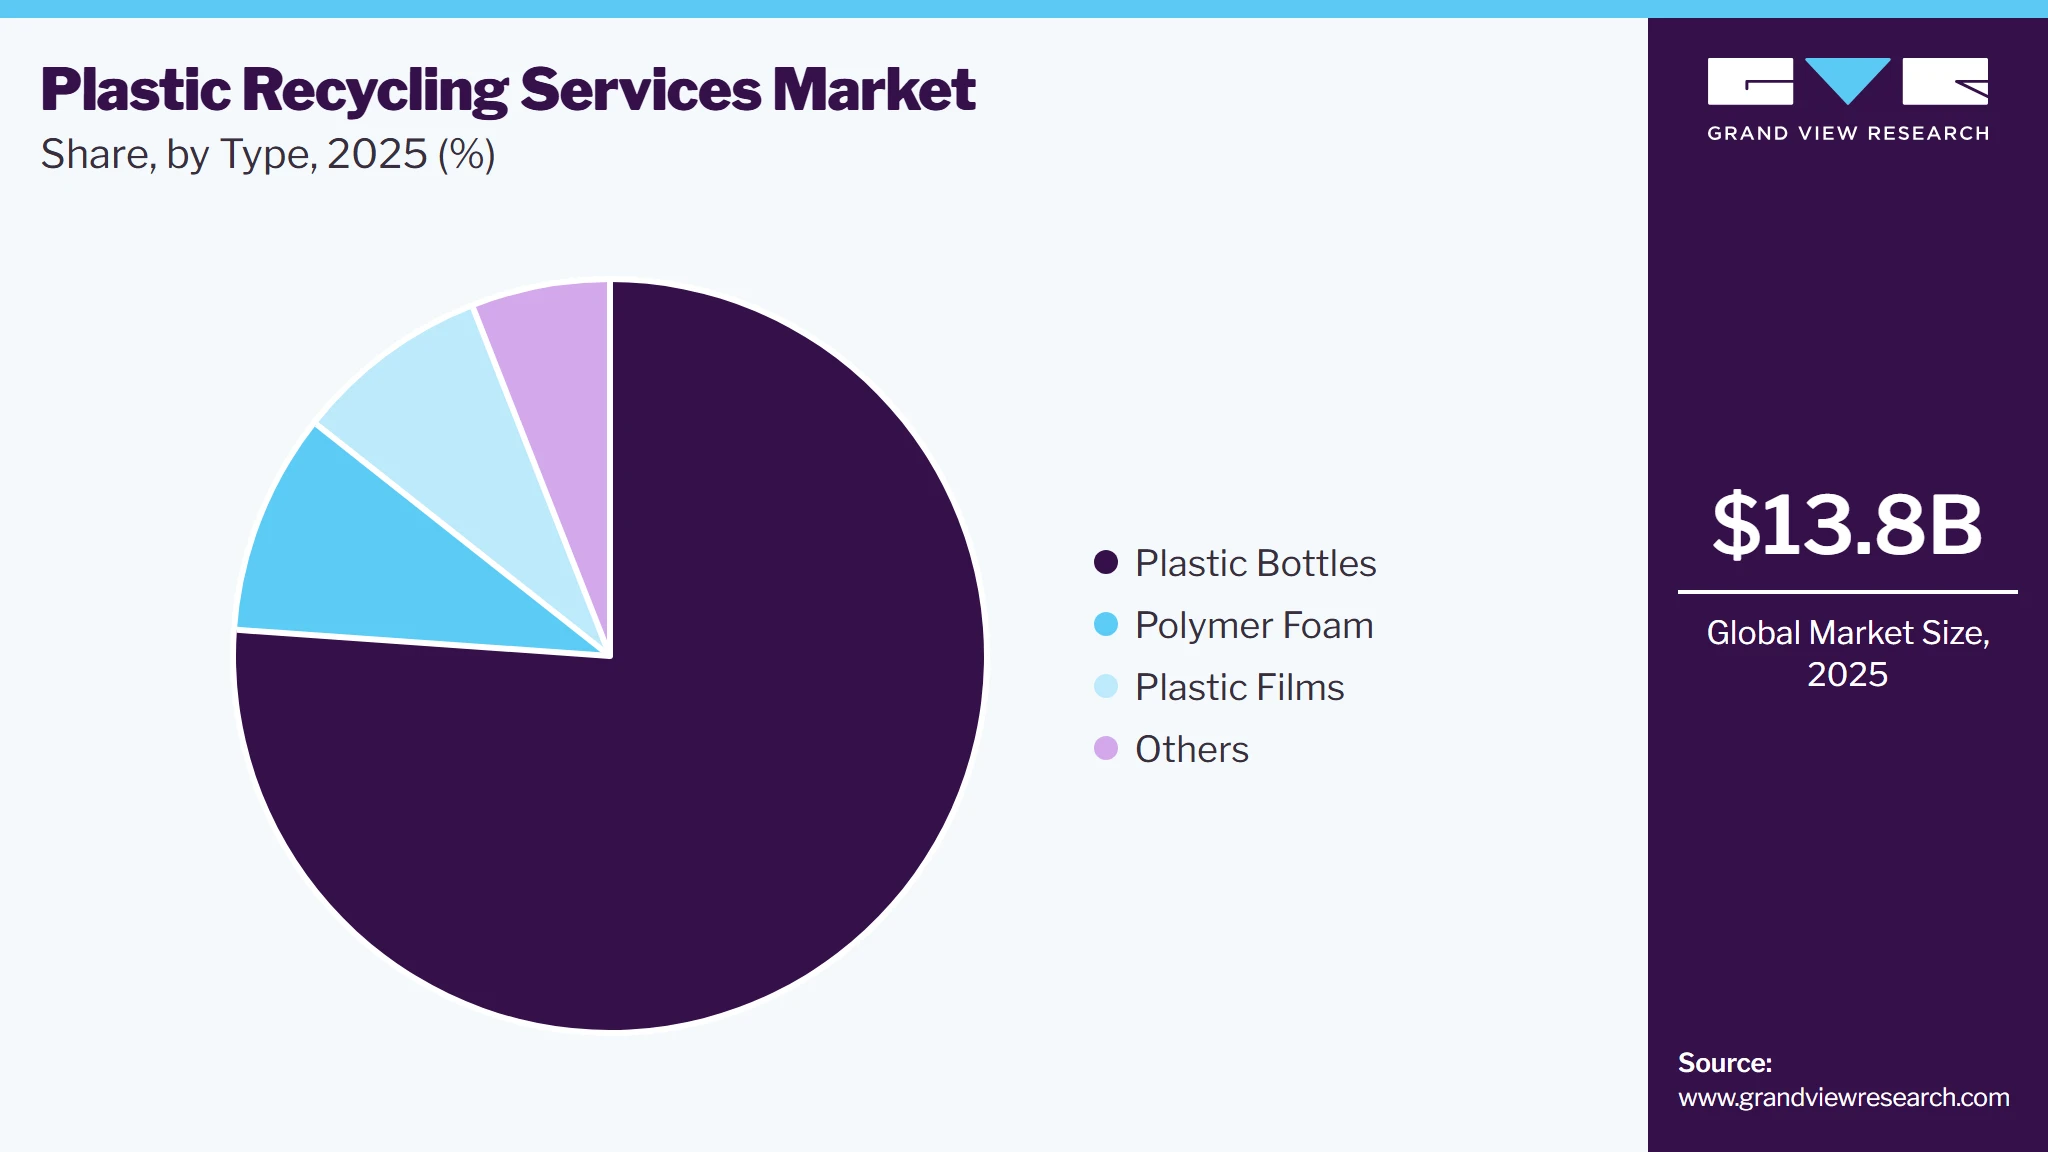
- By thickness: Plastic bottles segment led the market with the largest revenue share of 76.1% in 2025.
Regional Highlights
- Largest regional market: Europe (60.8% revenue share, 2025)
- By country: The Germany held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 13.8 Billion
- Estimated market size in 2026: USD 15.3 Billion
- Projected market size by 2033: USD 36.4 Billion
- CAGR (2026-2033): 13.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Growing concerns over the adverse environmental impacts of plastic waste, stricter sustainability initiatives, and expanding recycling infrastructure are accelerating market growth. Increasing emphasis on circular economy practices, resource conservation, and reducing landfill waste further supports the adoption of plastic recycling services throughout the forecast period. Such ill effects caused by this pollution lead to a surge the demand for the recycling services to manage plastic pollution effectively. A significant trend in the plastic recycling services market is the growing emphasis on the circular economy. Governments and companies are shifting towards recycling models that help to reduce waste and reuse of plastic materials. This trend is driven by the global sustainability movement, where industries are adopting practices to minimize their carbon footprint. Large corporations, especially in packaging, automotive, and consumer goods, are integrating recycled plastic into their products, driving demand for high-quality recycling services. The adoption of extended producer responsibility (EPR) programs also reflects the increased accountability for plastic waste management, contributing to market growth.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The plastic recycling services market is witnessing strong growth, driven by the increasing emphasis on circular economy practices and sustainable plastic waste management. Growing adoption of recycling models that promote plastic reuse, resource recovery, and waste reduction is accelerating market expansion. Rising integration of recycled plastics across packaging, automotive, and consumer goods industries is increasing demand for high-quality plastic recycling services. Furthermore, expanding implementation of extended producer responsibility (EPR) programs, supportive government regulations, and corporate sustainability initiatives is strengthening recycling infrastructure, improving resource efficiency, and supporting the long-term growth of the global plastic recycling services market.
The plastic recycling services market is experiencing steady growth, driven by the implementation of stringent government regulations aimed at reducing plastic waste and promoting sustainable waste management practices across packaging, automotive, consumer goods, and industrial sectors. Plastic recycling services are increasingly adopted to comply with single-use plastic bans, mandatory recycling targets, and waste reduction policies, enabling industries to improve resource efficiency, minimize landfill disposal, and support circular economy objectives. These regulatory initiatives are significantly accelerating the adoption of advanced recycling services across global markets.
Market growth is further supported by expanding extended producer responsibility (EPR) programs, ambitious plastic recycling targets, and increasing investments in recycling infrastructure and advanced processing technologies. Regulatory initiatives such as the European Union's objective of making all plastic packaging recyclable are strengthening demand for efficient recycling solutions, while similar legislative measures across North America and Asia are encouraging industries to adopt sustainable waste management practices. As governments continue to prioritize environmental protection, resource conservation, and carbon emission reduction, plastic recycling services are expected to witness sustained demand throughout the forecast period.
High operational costs remain a significant restraint for the plastic recycling services market. Plastic recycling requires substantial investments in waste collection, sorting, cleaning, processing equipment, advanced technologies, and skilled labor, increasing overall operating expenses. In addition, virgin plastic production often remains more cost-competitive, particularly during periods of low crude oil prices, reducing the economic attractiveness of recycled plastics. Limited recycling infrastructure in several regions further restricts processing capacity, operational efficiency, and market expansion. These financial and infrastructure challenges constrain the broader adoption of plastic recycling services, particularly among small-scale recyclers and developing economies.
Continuous advancements in plastic recycling technologies are creating significant growth opportunities for the plastic recycling services market. Rising adoption of chemical recycling technologies capable of processing difficult-to-recycle plastics is expanding the production of high-quality recycled materials for diverse industrial applications. Market growth is further supported by increasing deployment of AI-driven sorting systems, automation technologies, and advanced waste processing solutions that improve recycling efficiency, reduce contamination, and maximize material recovery. Additionally, ongoing innovation in recycling infrastructure and processing technologies is expected to enhance operational capacity, support circular economy initiatives, and drive long-term market growth during the forecast period.
Analyst Perspective
The plastic recycling services market is expected to undergo a structural transition over the next decade, shifting from a capacity-driven industry toward a technology- and value-driven circular economy ecosystem. Growth will be supported by rising plastic waste generation, stringent recycling regulations, extended producer responsibility (EPR) programs, and increasing recycled content commitments across packaging, automotive, construction, consumer goods, and electronics industries. Mechanical recycling will remain the dominant process for established waste streams, while chemical recycling, AI-enabled sorting, robotics, and digital waste traceability will create new value by improving recovery rates and enabling the recycling of complex plastics. Market leaders are expected to differentiate themselves through integrated collection and processing networks, advanced recycling technologies, strategic partnerships with municipalities and brand owners, geographic expansion, and the ability to consistently deliver high-quality recycled polymers. However, profitability will continue to be influenced by feedstock availability, contamination levels, volatile virgin polymer prices, infrastructure limitations, and evolving environmental regulations. Companies that invest in innovation, automation, supply chain integration, and application-specific recycled materials will be best positioned to capitalize on growing demand for sustainable plastic management solutions and strengthen their long-term competitive advantage.
Process Insights
Based on process, themechanical recycling segment led the market with the largest revenue share of 76.0% in 2025 owing to the growing demand for recycled plastics in various manufacturing sectors. As industries such as automotive, electronics, and packaging look to reduce their reliance on virgin plastics, they are increasingly turning to mechanically recycled plastics to meet sustainability goals. Many large corporations are incorporating recycled content into their products to align with eco-friendly consumer preferences and corporate social responsibility (CSR) initiatives. Major packaging companies are committing to using a certain percentage of recycled plastics in their products.
The chemical recycling segment is expected to grow at a significant rate over the forecast period. The segment is driven by the growing ability to process complex and contaminated plastics that mechanical recycling cannot handle. Chemical recycling, which breaks down plastics into their original chemical components, is gaining traction because it can recycle mixed, multi-layered, and contaminated plastics-such as food packaging, agricultural films, and medical waste-that typically end up in landfills. Unlike mechanical recycling, which can degrade plastic quality over multiple cycles, chemical recycling restores plastic to its virgin-grade quality, making it highly valuable for industries requiring high-performance materials. This technology also addresses the global challenge of plastic waste pollution by enabling more types of plastic to be recycled.
Type Insights
Based on thickness, the plastic bottles segment led the market with the largest revenue share of 76.1% in 2025, driven bythe high recycling rates of polyethylene terephthalate (PET) bottles and the growing demand for recycled PET (rPET). PET is widely used for beverage and water bottles, making it one of the most easily collected and recyclable plastics. Many regions have established bottle deposit schemes and curbside collection programs that encourage consumers to return used bottles for recycling. Additionally, the increasing use of rPET in packaging and textiles is propelling demand, as brands seek to meet sustainability goals and reduce plastic waste. Major companies, particularly in the food and beverage sector, are committing to using a significant portion of rPET in their packaging as part of their environmental pledges.
 To learn more about this report, Download Free Sample Report
The flame retardants segment is poised to grow at the fastest rate from 2024 to 2033. This can be attributed to the rising need for a safe environment and safe fire-resistant materials in industries such as construction, electronics, and automotive. As traditional flame retardants are often associated with harmful environmental and health effects, the demand for biodegradable alternatives that provide the same fire-resistance properties without toxic by-products is growing. Regulatory pressures to reduce the use of hazardous chemicals, combined with increasing consumer and industry focus on sustainability, are driving the adoption of biodegradable flame retardants. These additives allow manufacturers to meet stringent fire safety standards while aligning with eco-friendly production practices, making them crucial for high-performance, sustainable types.
Regional Insights
Europe dominated the plastic recycling services market with the largest revenue share of 31.9% in 2025. In North America, the plastic recycling services market is being driven by increasing corporate sustainability initiatives. Many large companies across various sectors, including retail, packaging, and consumer goods, are committing to ambitious recycling goals and circular economy models. These companies are partnering with recycling service providers to integrate recycled plastic into their products and packaging. Furthermore, growing consumer awareness and preference for eco-friendly products have put pressure on businesses to adopt recycled materials. This has led to a significant increase in demand for plastic recycling services, as companies aim to meet these sustainability standards and reduce their environmental impact.
 To learn more about this report, Download Free Sample Report
U.S. Plastic Recycling Services Market Trends
The plastic recycling services market in the U.S. is being driven by government incentives and legislative action aimed at reducing plastic waste. States like California have implemented strict recycling mandates, including bans on single-use plastics and requirements for producers to use recycled content in their packaging. Federal-level initiatives are also gaining momentum, such as the Break Free from Plastic Pollution Act, which seeks to increase recycling rates and reduce plastic waste. These legislative efforts, combined with tax incentives and grants for recycling infrastructure, encourage businesses to invest in and utilize plastic recycling services across the country.
Europe Plastic Recycling Services Market
Europe dominated the global plastic recycling services market and accounted for the largest revenue share of 47. 8% in 2023, owing to the strong regulatory focus on the circular economy and the implementation of Extended Producer Responsibility (EPR) programs. The European Union’s Green Deal and Plastics Strategy have set ambitious recycling targets, requiring all plastic packaging to be recyclable by 2033. EPR programs mandate that manufacturers are responsible for the recycling and disposal of their plastic products, pushing them to collaborate with recycling service providers. This regulatory framework is accelerating investment in advanced recycling technologies and infrastructure across the region, with industries such as packaging, automotive, and consumer goods being key contributors to the demand for plastic recycling services.
The plastic recycling services market in Germany accounted for the largest market revenue share in the Europe in 2025. Germany plastic recycling services market is a prominent country in the plastic recycling services market, driven by its technological advancements and efficient waste management systems. The country has one of the highest plastic recycling rates in the world, thanks to its comprehensive collection and sorting infrastructure. Germany’s focus on innovation in recycling technologies, such as advanced sorting systems and chemical recycling, enables it to process a wide range of plastic types with minimal contamination. Additionally, Germany’s strong industrial base, including the automotive and packaging sectors, heavily relies on high-quality recycled plastics, further boosting demand for sophisticated recycling services.
Asia Pacific Plastic Recycling Services Market Trends
In the Asia Pacific region, the plastic recycling services market is driven by the growing government focus on improving waste management systems to tackle plastic pollution. Countries like China, Japan, and India have introduced stricter regulations on plastic waste disposal and are investing in recycling infrastructure. China’s ban on the import of foreign plastic waste has shifted attention toward domestic recycling efforts, creating opportunities for local recycling services to expand. Additionally, rapid urbanization and industrial growth in the region are generating large amounts of plastic waste, increasing the need for efficient recycling services. Government campaigns promoting plastic waste reduction and recycling awareness are further stimulating demand for plastic recycling solutions across Asia Pacific.
Key Plastic Recycling Services Company Insights
The plastic recycling services market is highly competitive, with several key players dominating the landscape. The plastic recycling services market is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their products.
Key Plastic Recycling Services Companies:
The following key companies have been profiled for this study on the plastic recycling services market.
-
Deluxe Recycling
-
Shakti Plastics Industries
-
KW Plastics
-
Loop Industries
-
Birch Plastics
-
PureCycle Technologies
-
Mura Technology
-
Pellenc ST
-
Rekart Innovations Private Limited
-
Banyan Nation
Delivered Customizations
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (KW Plastics, Shakti Plastics Industries, Deluxe Recycling, Pellenc ST)
Focus on strengthening their position in the plastic recycling services market through the collection, sorting, processing, and commercialization of high-quality recycled plastics using advanced mechanical recycling technologies and automated waste management solutions.
Strong emphasis is placed on expanding recycling capacity, improving material recovery rates, developing food-grade and industrial recycled resins, and enhancing digital waste sorting capabilities.
Continuous investments in recycling infrastructure, processing technologies, strategic partnerships with municipalities, brand owners, and waste management companies support global market expansion and long-term commercial growth.
Extensive expertise in plastic waste collection, mechanical recycling, automated sorting technologies, and large-scale processing enables the production of high-quality recycled polymers for packaging, automotive, construction, and consumer goods applications.
Strong research and development capabilities, integrated recycling facilities, established supplier and customer networks, advanced material recovery technologies, and broad operational experience provide sustainable competitive differentiation and recurring revenue opportunities across major recycling markets.
High capital requirements for recycling infrastructure, dependence on consistent plastic waste feedstock availability, and fluctuations in recycled polymer prices expose companies to operational and financial risks.
Market growth is influenced by evolving environmental regulations, recycled content mandates, and competition from low-cost virgin plastics.
Additionally, continuous investments in advanced recycling technologies, automation, and facility modernization may pressure profitability and long-term market share.
Emerging Players (Loop Industries, PureCycle Technologies, Mura Technology, Birch Plastics, Rekart Innovations Private Limited, Banyan Nation)
Focus on expanding their presence in the plastic recycling services market through advanced chemical recycling technologies, AI-enabled waste sorting, circular plastic solutions, and high-purity recycled polymer production.
Emphasis is placed on scaling innovative recycling processes, expanding regional operations, strengthening collaborations with consumer brands and packaging manufacturers, and developing customized recycling solutions for complex plastic waste streams.
Strategic investments in technology commercialization, pilot facilities, and circular economy partnerships support market penetration and long-term growth.
Strong expertise in next-generation recycling technologies, flexible business models, AI-driven waste identification, advanced depolymerization processes, and innovative plastic recovery solutions enables these companies to address difficult-to-recycle plastics and produce high-quality recycled feedstocks.
Their operational agility, rapid technology development, sustainability-focused business strategies, and close partnerships with global brand owners strengthen their competitive positioning in high-growth recycling markets.
Limited commercial-scale processing capacity, relatively lower financial resources, and ongoing dependence on technology validation and commercialization may restrict rapid global expansion.
High capital expenditure requirements, evolving regulatory standards, feedstock quality variability, and reliance on strategic partnerships can constrain long-term growth.
Additionally, significant investments in plant scale-up, technology optimization, and international market expansion are required to compete effectively with established plastic recycling service providers.
Recent Developments
-
In August 2024, Honeywell and Hinergy launched an advanced plastic recycling program to improve the sustainability of plastic waste management. This initiative will utilize innovative technologies to convert plastic waste into valuable materials, thereby reducing environmental impact. The collaboration seeks to enhance the circular economy by ensuring that plastics are recycled more effectively and can be reused in various applications.
-
In August 2023, Polyplastics launched a new recycling service aimed at engineering plastics. This initiative is designed to help companies manage their plastic waste more effectively by providing a solution for recycling materials that are typically difficult to process. The service will allow businesses to send their used engineering plastics to Polyplastics, where they will be recycled and repurposed into new products.
Plastic Recycling Services Market Report Scope
Report Attribute
Details
Market size in 2025
USD 13.8 billion
Estimated market size in 2026
USD 15.3 billion
Projected market size by 2033
USD 36.4 billion
Growth rate
CAGR of 13.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Process, type, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; South Korea; Indonesia; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Deluxe Recycling; Shakti Plastics Industries; KW Plastics; Loop Industries; Birch Plastics; PureCycle Technologies; Mura Technology; Pellenc ST; Rekart Innovations Private Limited; Banyan Nation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Plastic Recycling Services Market Report Segmentation
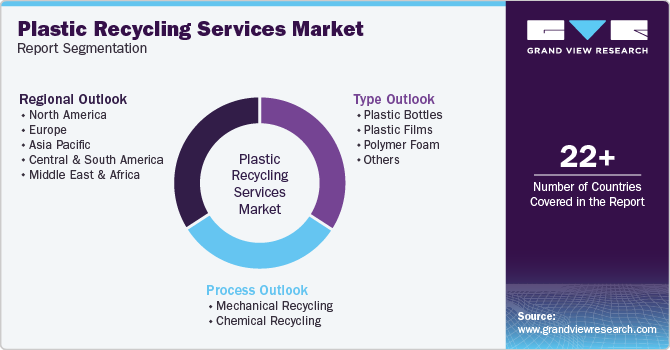
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented Plastic Recycling Services market report based on process, type, and region:
 To learn more about this report, Download Free Sample Report
-
Process Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Mechanical Recycling
-
Chemical Recycling
-
-
Type Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Plastic Bottles
-
Plastic Films
-
Polymer Foam
-
Others
-
-
Regional Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Indonesia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The plastic recycling services market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each plastic recycling services segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Process
Revenue capture definition
Mechanical Recycling
Revenue is captured through the collection, sorting, washing, shredding, and reprocessing of plastic waste into recycled plastic resins for packaging, construction, automotive, consumer goods, and industrial applications. Demand is driven by cost-effectiveness, established recycling infrastructure, lower energy consumption, regulatory support, and increasing adoption of circular economy practices.
Chemical Recycling
Revenue is captured through the commercialization of chemical recycling services that convert plastic waste into monomers, feedstocks, fuels, or virgin-quality polymers through advanced depolymerization, pyrolysis, and gasification technologies. Growth is supported by the ability to process mixed and difficult-to-recycle plastics, improve material recovery, produce high-quality recycled feedstocks, and meet rising sustainability and recycled content requirements.
Segment - Type
Revenue capture definition
Plastic Bottles
Revenue is captured through the collection, sorting, processing, and recycling of post-consumer plastic bottles into recycled resins for packaging, textiles, automotive, and consumer goods applications. Demand is driven by high bottle consumption, deposit return schemes, recycled content mandates, well-established collection systems, and increasing demand for food-grade recycled plastics.
Plastic Films
Revenue is captured through the recycling of post-industrial and post-consumer plastic films generated from packaging, agriculture, retail, and industrial applications. Growth is supported by increasing demand for flexible packaging recycling, advancements in film collection and washing technologies, regulatory pressure to reduce plastic waste, and expanding adoption of recycled film materials across industries.
Polymer Foam
Revenue is captured through the collection and recycling of polymer foam waste, including expanded and extruded foam materials, into reusable raw materials for packaging, construction, insulation, and consumer products. Demand is driven by rising foam waste generation, technological advancements in densification and recycling processes, landfill diversion initiatives, and increasing focus on resource recovery.
Others
Revenue is captured through the recycling of rigid plastics, industrial plastic scrap, automotive plastics, household products, containers, crates, pipes, and other plastic waste streams into recycled materials for diverse end-use industries. Growth is supported by expanding waste segregation programs, advancements in recycling technologies, increasing industrial sustainability initiatives, and broader adoption of circular economy practices across global markets.
Estimation Model
Layer Name
Key Question
Description
Top-Down Plastic Recycling Services Demand Assessment Layer
What defines market boundaries?
This layer begins with global plastic waste generation across packaging, automotive, construction, electrical & electronics, textiles, agriculture, consumer goods, and industrial sectors. Demand is filtered based on plastic consumption, post-consumer and post-industrial waste generation, recycling rates, waste collection infrastructure, sustainability initiatives, circular economy adoption, and government regulations promoting plastic waste management across major regional markets.
Waste Stream and End-Use Validation Layer
Where is demand generated?
This layer evaluates demand distribution across plastic bottles, plastic films, polymer foam, rigid plastics, and other recyclable plastic waste streams. Market revenue is aligned with critical processing requirements including efficient collection, sorting, washing, contamination removal, material recovery, recycled resin quality, regulatory compliance, and increasing demand for recycled plastics across packaging, automotive, construction, consumer goods, and industrial applications.
Process and Technology Conversion Layer
Who captures market revenue?
This layer converts waste stream demand into the plastic recycling services market revenue by applying process mix ratios across mechanical recycling, chemical recycling, and other advanced recycling technologies. Revenue allocation considers recycling technology, processing efficiency, feedstock quality, operational costs, material recovery rates, recycled polymer quality, technology adoption, service pricing, value-added recycling capabilities, and competitive positioning across the global plastic recycling value chain.
Regional Commercial Cross-Check Layer
How are assumptions validated?
This layer validates demand concentration by comparing Asia Pacific's leadership in plastic consumption, manufacturing activities, and recycling capacity; Europe's demand driven by stringent environmental regulations, circular economy initiatives, and recycled content mandates; and North America's growth supported by advanced recycling infrastructure, corporate sustainability commitments, and increasing investments in recycling technologies. It also evaluates emerging opportunities across Latin America and the Middle East & Africa, supported by expanding waste management infrastructure, rising environmental awareness, government recycling initiatives, and increasing investments in sustainable plastic waste management systems.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed market analysis across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, including country-level demand assessment, recycling infrastructure maturity, regulatory landscape, waste generation trends, recycling capacity, and end-use industry adoption.
Enables identification of high-growth regions, investment hotspots, regulatory impacts, and regional expansion strategies while supporting market entry and resource allocation decisions.
Cross-Segmentation
Comprehensive analysis across Process (Mechanical Recycling, Chemical Recycling), Type (Plastic Bottles, Plastic Films, Polymer Foam, Others), Source, End-use Industry, and Region, with detailed revenue contribution and growth potential for each combination.
Identifies the most attractive market niches, demand clusters, and high-value application areas, enabling targeted product development and commercial strategy optimization.
Opportunity Assessment
Strategic assessment of emerging growth opportunities across advanced recycling technologies, chemical recycling, food-grade recycled plastics, AI-enabled sorting systems, circular economy initiatives, EPR programs, and high-growth end-use industries including packaging, automotive, construction, and consumer goods.
Enables stakeholders to prioritize high-return investment areas, evaluate future technology trends, capitalize on evolving regulatory requirements, and strengthen long-term competitive positioning.
Frequently Asked Questions About This Report
The global plastic recycling services market size was estimated at USD 13.8 billion in 2025 and is expected to reach USD 15.3 billion in 2026.
The global plastic recycling services market is expected to grow at a compound annual growth rate (CAGR) of 8.11% from 2024 to reach USD 36.4 billion in 2033.
Some of the key players Deluxe Recycling; Shakti Plastics Industries; KW Plastics; Loop Industries; Birch Plastics; PureCycle Technologies; Mura Technology; Pellenc ST; Rekart Innovations Private Limited; and Banyan Nation.
Rising non-degradable plastic pollution globally is increasing the threat of various ill effects caused by this pollution leading to a surge in the demand for recycling services to effectively manage plastic pollution.
Europe dominated the global plastic recycling services market and accounted for largest revenue share of 60.8% in 2025, owing to the strong regulatory focus on the circular economy and the implementation of Extended Producer Responsibility (EPR) programs. The European Union’s Green Deal and Plastics Strategy have set ambitious recycling targets, requiring all plastic packaging to be recyclable by 2030.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


