
- Home
- »
- Consumer F&B
- »
-
U.S. Coffee Creamer Market Size, Share Report, 2026-2033GVR Report cover

U.S. Coffee Creamer Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Dairy-based, Non-dairy), By Type (High-fat, Low-fat (<3 grams)), By Form (Liquid, Powder), By Nature, By Flavor, By Packaging Type, By Distribution Channel, And Segment Forecasts
Market Size, 2025
$1.0BMarket Estimate, 2026
$1.1BMarket Forecast, 2033
$1.6BCAGR, 2026–2033
5.2%U.S. Coffee Creamer Market Summary
The U.S. coffee creamer market size was valued at USD 1.0 billion in 2025 and is projected to grow from USD 1.1 billion in 2026 to USD 1.6 billion by 2033, at a CAGR of 5.2% from 2026 to 2033. The market growth is primarily driven by the growing demand for convenient, ready-to-use coffee products and the increasing popularity of at-home coffee consumption. Rising consumer preference for flavored, plant-based, and low-sugar creamers is also fueling market growth.
Key Market Trends & Insights
- By product: Non-dairy coffee creamer held the largest market share of 57.4% in 2025
- By type: Fat-free (<0.5 grams) coffee creamer is expected to grow at the fastest CAGR of 5.9% from 2026 to 2033
- By form: Liquid coffee creamer held the largest market share of 57.3% in 2025
- By nature: Conventional coffee creamer held the largest market share of 87.8% in 2025
- By flavor: Flavored coffee creamers held the largest revenue share of 64.4% in 2025
- By packaging type: PET bottles held the largest revenue share of 43.3% in 2025
- By distribution channel: B2B channels held the largest market share of 54.3% in 2025
Market Size & Forecast
- Market size in 2025: USD 1.0 Billion
- Estimated market size in 2026: USD 1.1 Billion
- Projected market size by 2033: USD 1.6 Billion
- CAGR (2026-2033): 5.2%
Prism AI by Grand View Research Free to tryAsk a question about the U.S. coffee creamer marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Continuous innovation in product formulations, including functional creamers enriched with protein, collagen, and vitamins, is supporting market expansion. Expanding retail and e-commerce distribution channels have improved product accessibility, while changing consumer lifestyles continue to encourage premium and specialty coffee experiences at home.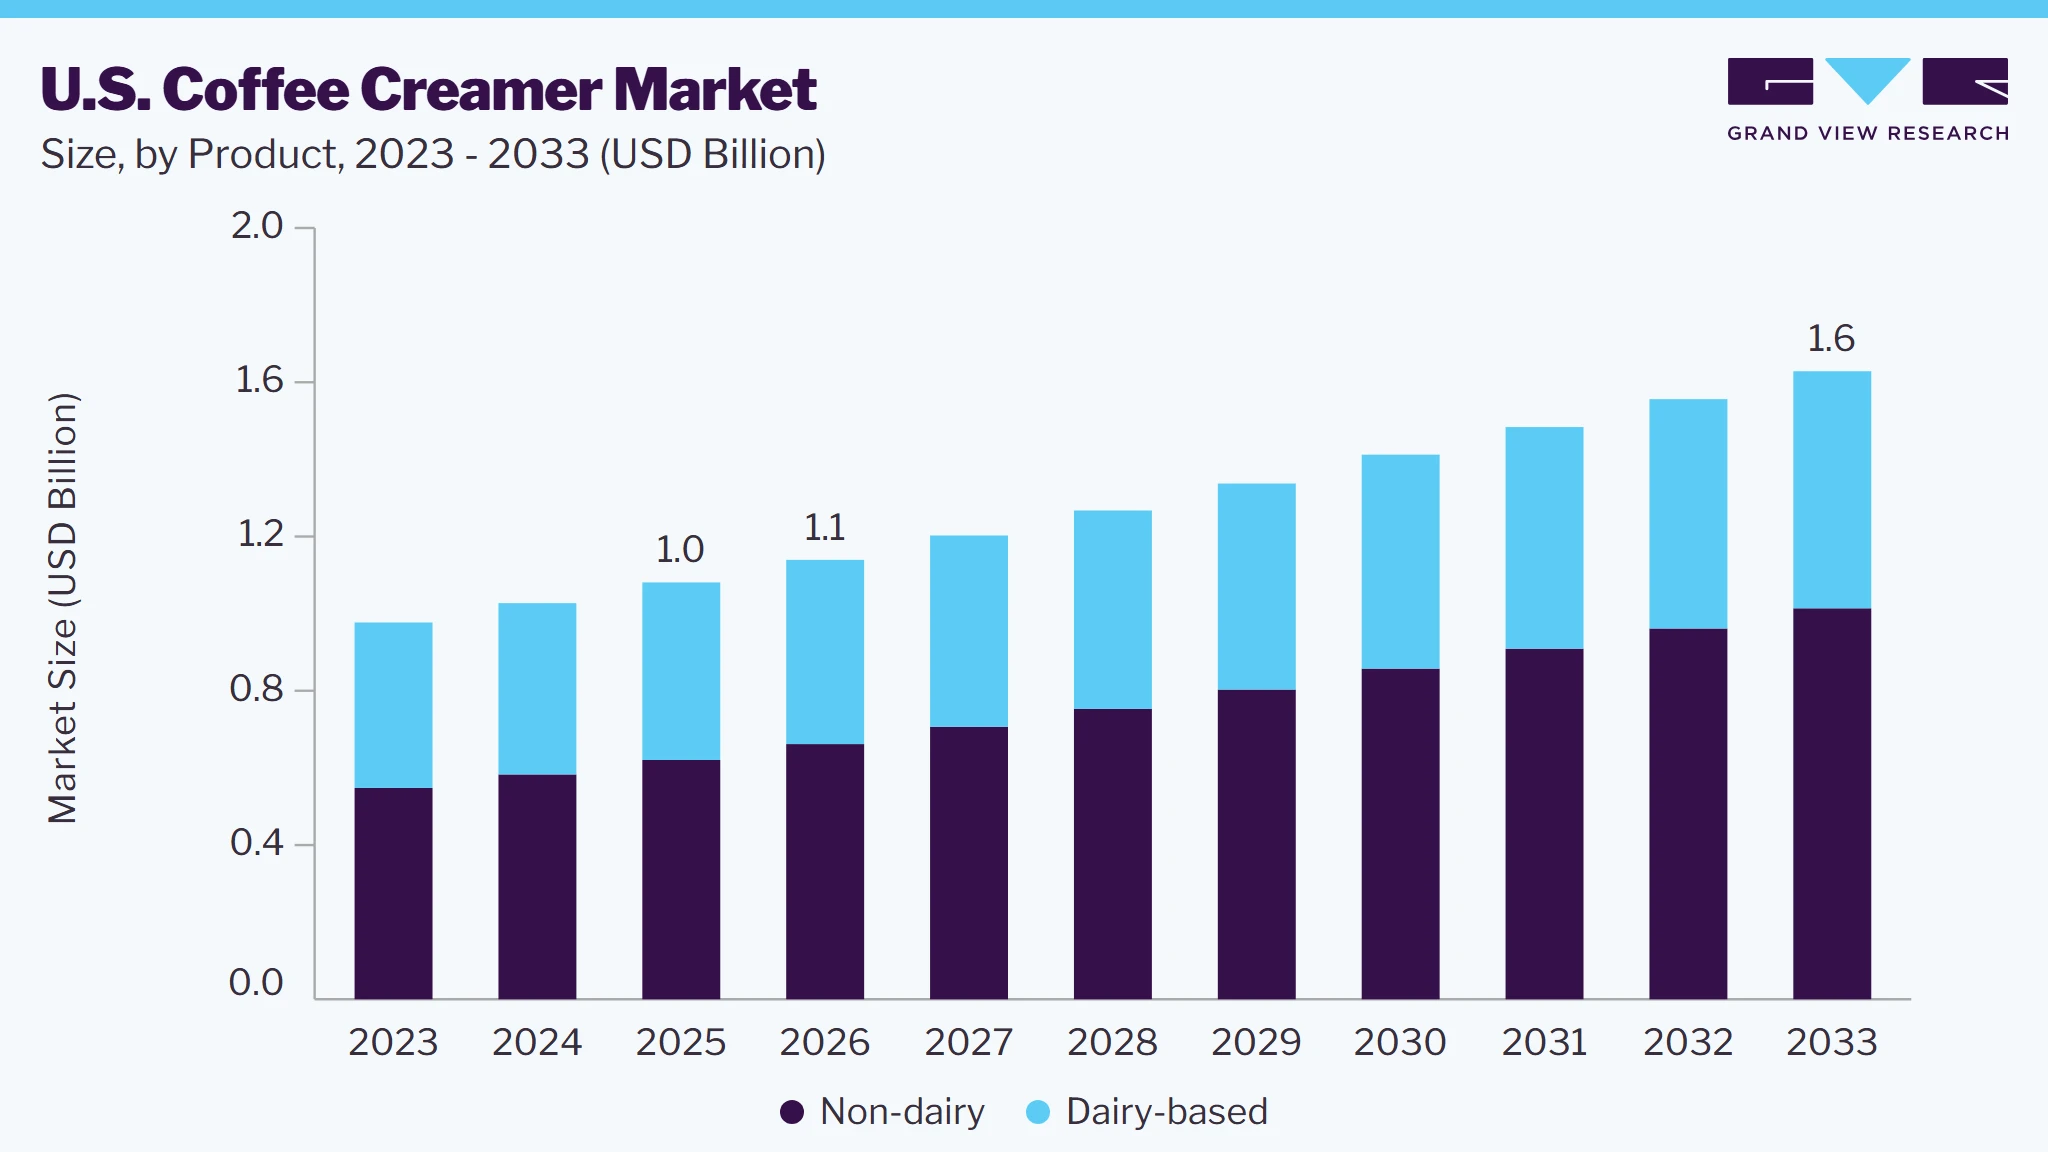 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Product manufacturers are increasingly focusing on clean-label ingredients and sustainable packaging to align with evolving consumer expectations. Strategic collaborations, new product launches, and marketing initiatives are helping brands strengthen their market presence. Additionally, the growing influence of café culture is encouraging consumers to experiment with a wider variety of coffee creamer options at home. In January 2026, Nestlé expanded its Natural Bliss line with three new coffee creamers: Chai Vanilla Latte, Chocolate Caramel Truffle, and Hazelnut Cookie Crumble (Zero Sugar), all made with just four simple ingredients. They’re available nationwide in 32-ounce bottles for about USD 5.99 and are designed for coffee as well as recipes like smoothies, frosting, and yogurt.
Market Dynamics
Consumers are increasingly seeking café-style coffee experiences within their homes, boosting the use of creamers as an easy way to customize beverages. The availability of diverse flavors and specialty options is encouraging experimentation among coffee drinkers. This trend is further supported by busy lifestyles that favor quick and personalized beverage solutions. In January 2026, Chobani launched a new Raspberry Rose coffee creamer, blending fruity raspberry notes with floral rose flavors to offer consumers a unique, premium at-home coffee experience. The limited-edition creamer expands Chobani’s coffee portfolio, targeting growing demand for innovative and indulgent coffee additions. The expansion of home brewing equipment and coffee subscription services is also strengthening demand for complementary products. Premiumization trends are encouraging consumers to explore innovative creamer varieties that enhance their daily coffee routines.
A shift toward simpler coffee habits and awareness of ingredient transparency is limiting demand among some consumer groups. Health-focused consumers are reducing the use of products perceived as adding extra calories, sugar, or processed components. This preference may challenge market growth by encouraging alternatives to traditional coffee creamers. Growing interest in natural beverage choices is influencing purchasing decisions among health-conscious buyers. Manufacturers face pressure to reformulate products to meet changing nutritional expectations and consumer preferences.
Analyst Perspective
The U.S. coffee creamer market is expected to remain competitive, supported by continued consumer interest in convenient, at-home coffee experiences. Product innovation across flavors, formats, and cold-foam offerings is helping brands deliver café-style experiences and encourage consumer engagement. Demand for plant-based, lower-sugar, clean-label, and other lifestyle-oriented options is also influencing product development. Seasonal flavors, brand collaborations, and premium formulations are creating opportunities for differentiation and stronger shelf appeal.
Product Insights
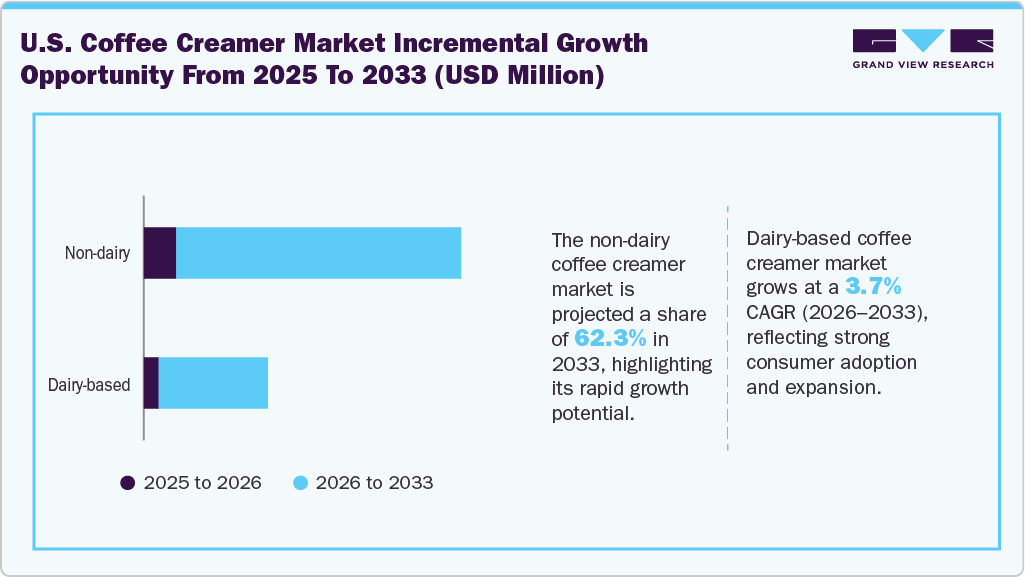
The non-dairy coffee creamer market segment accounted for the largest revenue share of 57.4% in 2025. Non-dairy creamers are gaining traction due to increasing demand for lactose-free and vegan-friendly beverage options. Consumers seeking alternatives to animal-derived ingredients are driving interest in plant-based formulations made from sources such as almonds, oats, and soy. Product innovation in flavors, nutritional profiles, and improved taste performance is expanding their consumer base. In February 2024, Oatly expanded its North American beverage portfolio by launching four flavored oatmilk creamers, Sweet & Creamy, Vanilla, Caramel, and Mocha, targeting consumers seeking indulgent, plant-based coffee experiences at home. The launch taps into rising demand for plant-based creamers, with the category showing sales growth and strengthening Oatly’s position in the non-dairy coffee creamer market.
 To learn more about this report, Download Free Sample Report
The dairy-based coffee creamer market segment is projected to grow significantly at a CAGR of 3.7% from 2026 to 2033. Dairy-based creamers benefit from their traditional appeal, familiar taste, and ability to provide a rich texture to coffee beverages. Strong consumer trust in milk-derived products continues to support their adoption among conventional coffee drinkers. Their widespread availability through supermarkets and grocery retailers further strengthens market penetration. The preference for creamy and indulgent coffee experiences also contributes to segment growth.
Type Insights
The high-fat coffee creamer market segment accounted for the largest share of 62.7% in 2025. High-fat creamers are driven by consumer preference for rich mouthfeel, smooth texture, and a more indulgent coffee experience. They are widely used by customers who prioritize taste enhancement and a premium beverage feel. Demand is driven by their ability to replicate the richness of specialty coffee preparations. The segment continues to attract consumers seeking a fuller and more satisfying coffee flavor profile.
The fat-free (<0.5 grams) coffee creamer market segment is projected to grow significantly at a CAGR of 5.9% from 2026 to 2033. Fat-free creamers are gaining popularity among consumers focused on calorie management and healthier dietary choices. Their appeal is supported by growing interest in lighter beverage options without sacrificing convenience. Manufacturers are introducing improved formulations to maintain flavor quality while meeting nutritional preferences. The segment benefits from increasing awareness of balanced lifestyles and reduced fat consumption.
Form Insights
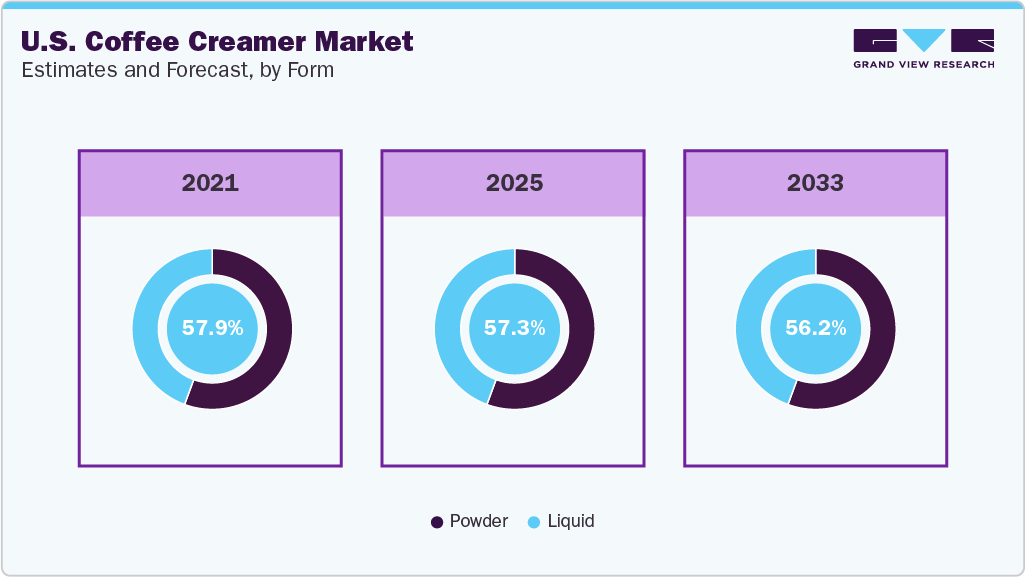
The liquid coffee creamer market segment accounts for the largest share of 57.3% in 2025. Liquid creamers are driven by their ease of use, quick mixing ability, and ability to provide consistent flavor in every serving. Consumers prefer them for their smooth incorporation into hot and cold coffee beverages without additional preparation. Their availability in multiple bottle sizes and refrigerated or shelf-stable formats supports broader usage. The segment benefits from strong demand among households seeking convenient coffee customization.
 To learn more about this report, Download Free Sample Report
The powder coffee creamers are projected to grow significantly at a CAGR of 5.6% from 2026 to 2033. Powder creamers are supported by their longer shelf stability and suitability for storage without refrigeration. They are widely preferred in workplaces, travel settings, and regions that value extended product durability. Their lightweight packaging and easy transport make them a practical choice for bulk consumption. The segment also benefits from cost efficiency and reduced storage requirements for consumers and businesses.
Nature Insights
The conventional coffee creamers market segment accounted for the largest share of 87.8% in 2025. Conventional creamers continue to hold strong demand due to their affordability, wide availability, and established presence in everyday coffee routines. They appeal to price-sensitive consumers seeking practical options for regular use. Extensive distribution networks and broad product variety support their continued market presence. The segment benefits from consistent purchasing patterns among mainstream coffee consumers.
The organic coffee creamers market segment is projected to grow at the fastest CAGR of 6.1% from 2026 to 2033. Organic creamers are driven by growing consumer interest in products made with naturally sourced ingredients and produced with environmentally conscious practices. Demand is supported by shoppers who prioritize cleaner ingredient lists and certified organic offerings. Premium positioning and perceived health benefits allow brands to attract consumers willing to pay higher prices. The segment is further strengthened by the expansion of organic product availability across retail channels.
Flavor Insights
The flavored coffee creamers market segment accounted for the largest share of 64.4% in 2025. Flavored creamers are gaining momentum due to rising interest in personalized and diverse coffee experiences. Consumers are attracted to options with seasonal, dessert-inspired, and unique flavor profiles. Continuous introduction of new flavors helps brands capture changing preferences and encourage product trial. The segment benefits from the growing trend of experimenting with customized beverages. In July 2026, Coffee Mate introduced a limited-time Situation-Sip Mixed Fruit Flavored Creamer, blending strawberry, citrus, and berry flavors and inspired by the playful and unexpected moments of summer “situationships.” The brand collaborated with TV personality Carl Radke and launched a lighthearted, social-focused campaign to engage consumers looking for distinctive seasonal coffee options.
The regular/unflavored coffee creamers market segment is projected to grow at the fastest CAGR of 6.1% from 2026 to 2033. Regular or unflavored creamers are driven by consumers who prefer a classic coffee taste and a smooth, balanced texture. They appeal to users seeking simple beverage enhancements without altering the original coffee profile. Strong familiarity and compatibility with different coffee varieties support their consistent demand. The segment remains popular among consumers who value traditional coffee preparation methods.
Packaging Type Insights
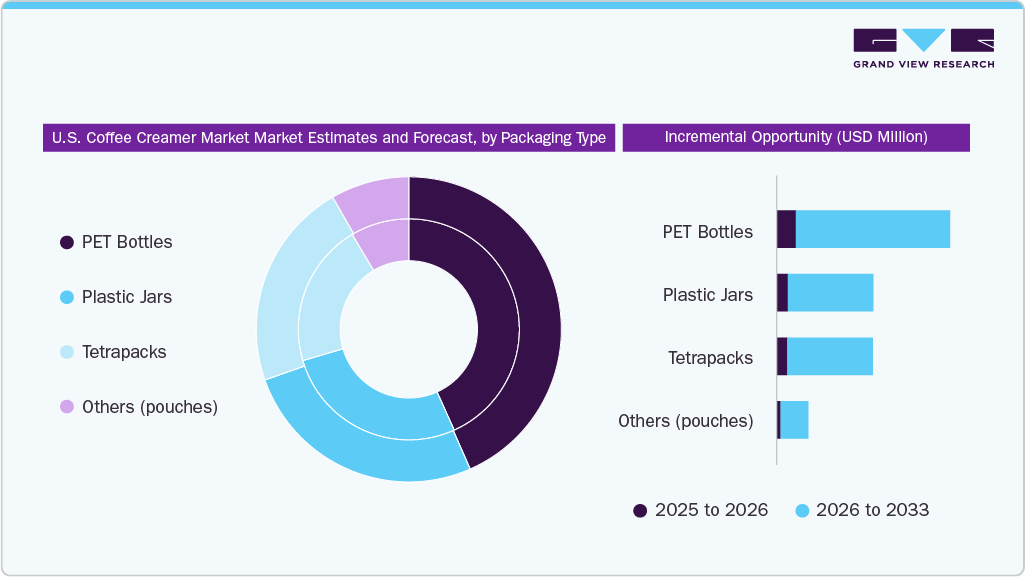
Coffee creamers packaged in PET bottles dominated the U.S. coffee creamer industry, accounting for the largest share of 43.3% in 2025. PET bottles are popular for their convenience, durability, and user-friendly design, making them well-suited for frequent household use. Their lightweight structure makes them easier to handle, store, and transport compared with heavier packaging alternatives. The format supports attractive branding through clear visibility and flexible design options. Strong consumer familiarity with plastic beverage packaging continues to support its adoption.
 To learn more about this report, Download Free Sample Report
Coffee creamers packaged in tetra packs are projected to grow at the fastest CAGR of 6.1% from 2026 to 2033. Tetra Pak packaging is gaining in demand due to its ability to extend shelf life and protect product quality. The aseptic technology allows creamers to be stored efficiently without relying heavily on refrigeration during distribution. The format appeals to brands focusing on sustainability through reduced material usage and efficient logistics. Growing preference for convenient, shelf-stable products is further supporting segment growth.
Distribution Channel Insights
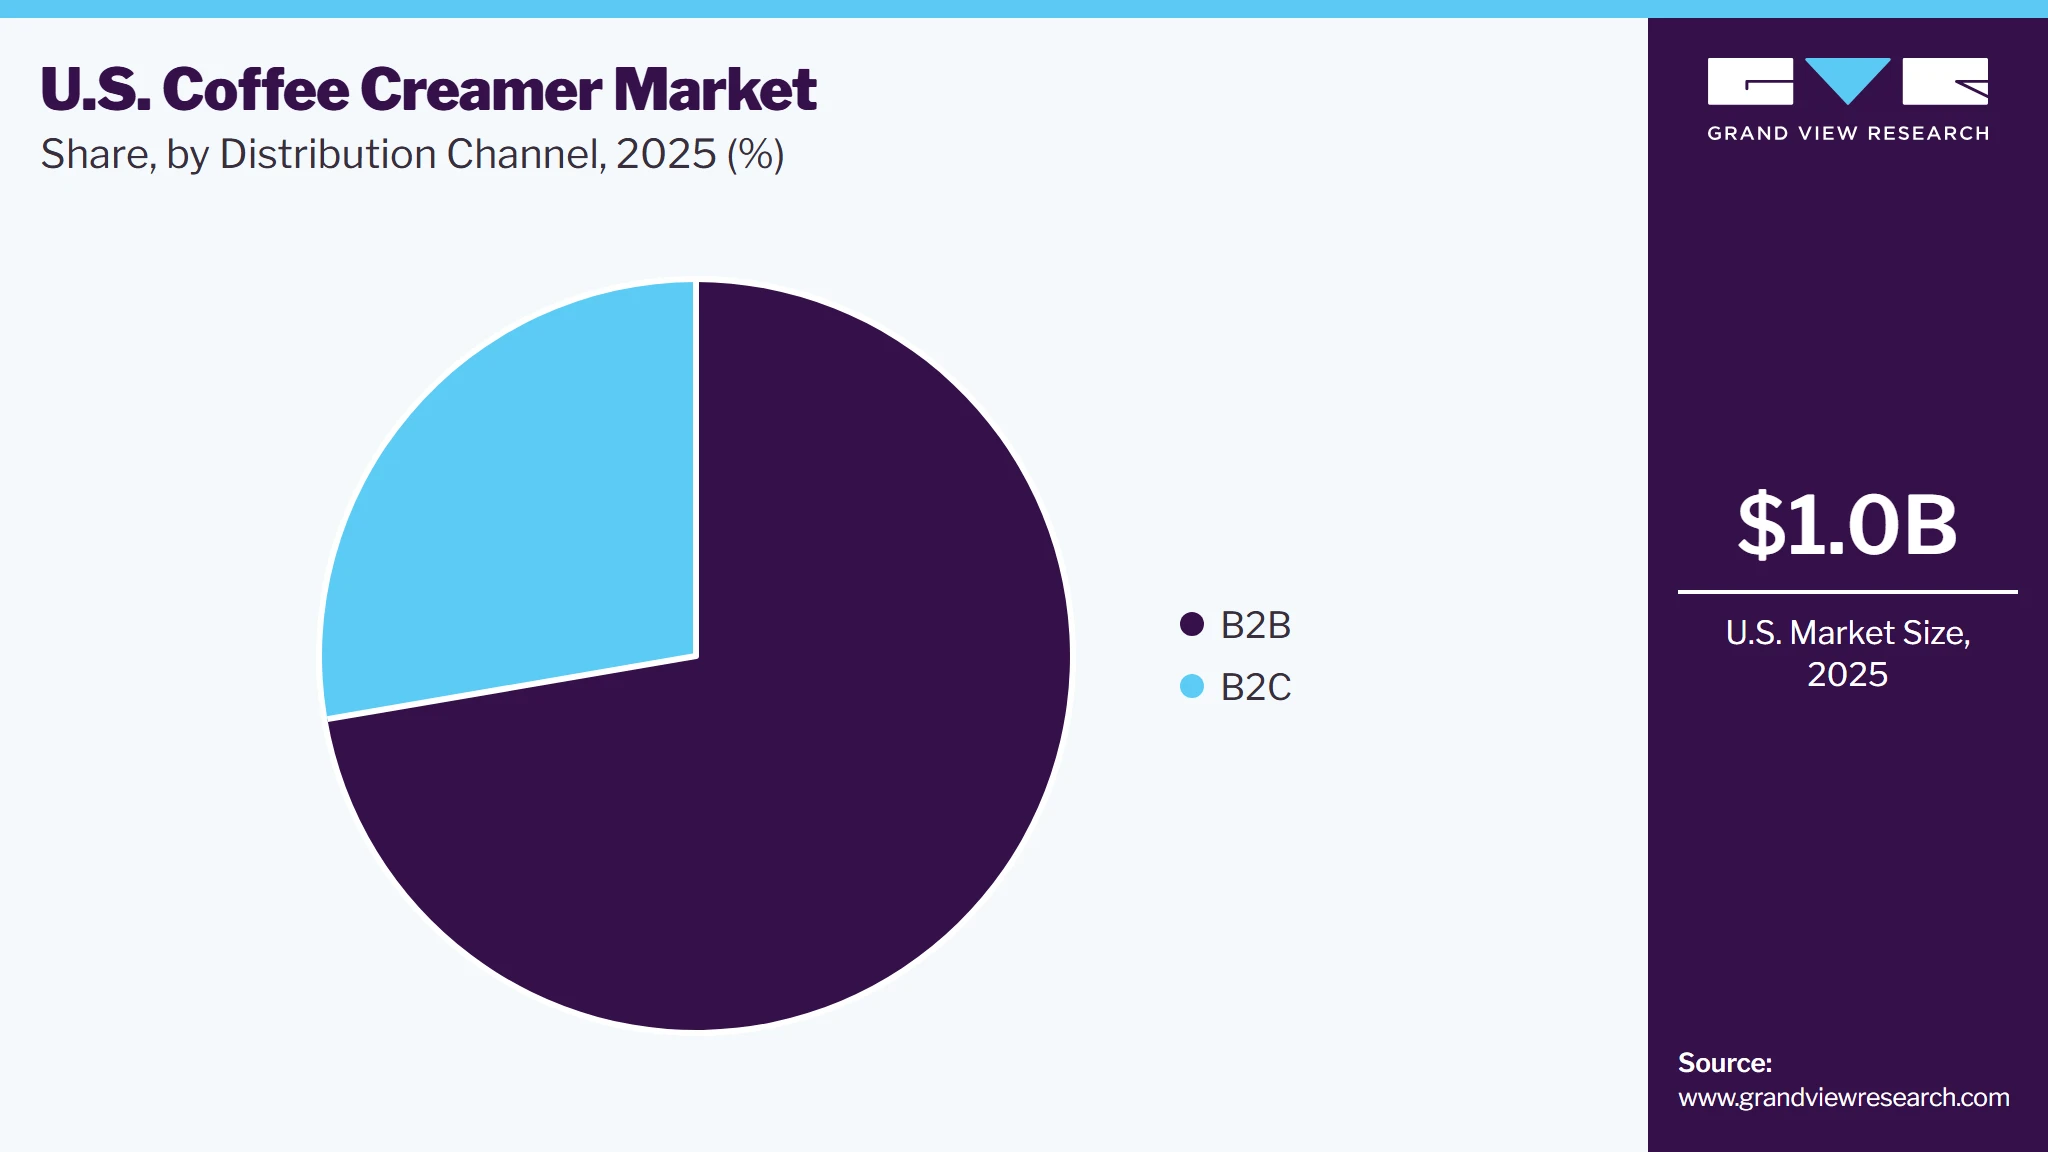
The B2B channel in the U.S. coffee creamer market accounts for the largest revenue share of 54.3% in 2025. The segment growth is driven by rising demand from offices, cafés, restaurants, hotels, and institutional foodservice providers. Coffee creamers offer businesses a convenient solution for serving consistent beverage experiences across large customer groups. Bulk purchasing and operational efficiency make creamers an attractive option for commercial users. Growth in workplace beverage programs and hospitality services further supports this channel.
 To learn more about this report, Download Free Sample Report
The B2C distribution channel in the U.S. coffee creamer industry is projected to grow at the fastest CAGR of 5.6% from 2026 to 2033. The segment growth is supported by the increasing consumer preference for purchasing coffee creamers through supermarkets, convenience stores, and online platforms. Easy product accessibility and a wide range of choices enable households to select products based on taste, dietary needs, and budget. Digital retail growth is improving product reach and purchase convenience. Direct engagement between brands and consumers through marketing initiatives is also strengthening this channel. In October 2025, Starbucks launched new at-home coffee creamers, including Salted Pecan Creamer and Caramel Macchiato Creamer, expanding its retail coffee portfolio with popular café-inspired flavors. The creamers are available at Walmart, targeting consumers seeking convenient ways to recreate premium coffeehouse experiences at home.
Country Insights
Growth in the U.S. coffee creamer market is driven by continuous product innovation and the introduction of new formulations that meet changing consumer expectations. Increasing interest in enhanced coffee experiences is encouraging manufacturers to develop differentiated offerings with improved taste and functionality. The growing presence of coffee-focused trends and lifestyle-oriented beverage choices is supporting market expansion. Companies are also investing in branding and promotional activities to strengthen consumer engagement. Additionally, rising competition among manufacturers is encouraging greater variety and creativity within the market.
Key U.S. Coffee Creamer Company Insights
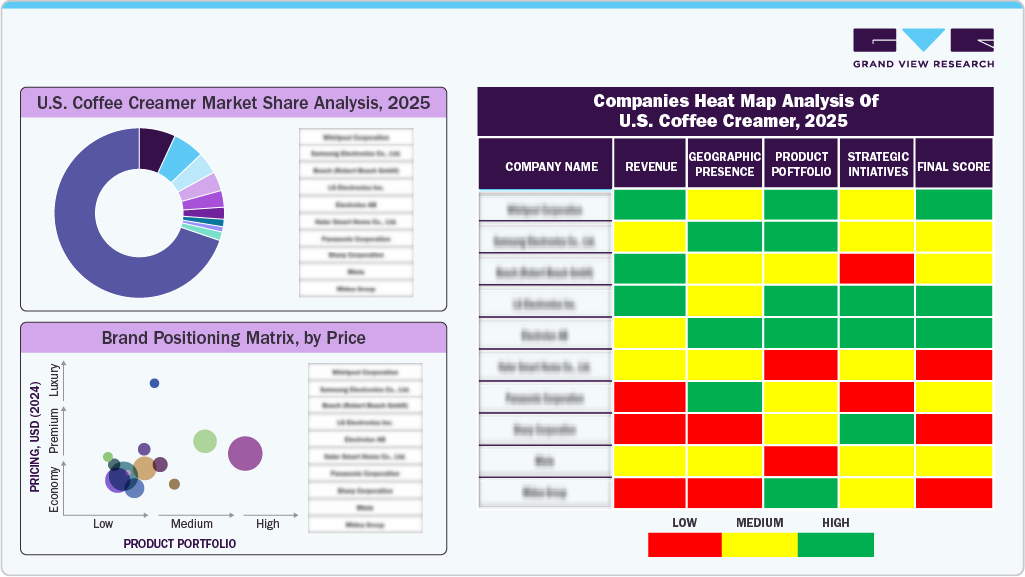
The U.S. coffee creamer industry is characterized by the presence of established multinational companies and regional brands competing across various product categories. Leading players maintain strong market positions through extensive distribution networks, brand recognition, and continuous product development.
The market share is influenced by consumer preferences for diverse product formats, flavors, and ingredient profiles. Companies are focusing on innovation, strategic partnerships, and marketing initiatives to strengthen their competitive advantage. The increasing entry of specialty and emerging brands is also contributing to a more dynamic and competitive market landscape.
 To learn more about this report, Download Free Sample Report
Key U.S. Coffee Creamer Companies
-
Nestlé S.A.
-
Danone
-
Chobani LLC
-
Land O’Lakes, Inc.
-
Heartland Food Products Group
-
Leaner Creamer LLC
-
Califia Farms, LLC
-
nutpods
-
Starbucks Coffee Company
-
Laird Superfood
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Nestlé S.A., Danone, Chobani)
- Expand flavor portfolios, invest in capacity, and launch plant-based & premium formats.
- Strong brands, extensive retail distribution, and high innovation capabilities.
- High marketing costs, intense competition, and exposure to input-cost volatility.
Emerging Players (nutpods, Laird Superfood)
- Focus on plant-based, clean-label, organic, and health-oriented creamers; expand retail presence.
- Differentiated products, agile innovation, and strong appeal among health-conscious consumers.
- Smaller distribution footprint, lower brand awareness, and higher unit costs.
Recent Developments
-
In July 2026, Coffee Mate introduced a limited-time Situation-Sip Mixed Fruit Flavored Creamer with a blend of strawberry, citrus, and berry flavors, drawing inspiration from the playful and unexpected moments of summer “situationships.” The brand collaborated with TV personality Carl Radke and launched a lighthearted, social-focused campaign to engage consumers looking for distinctive seasonal coffee options
-
In January 2026, Nestlé expanded its Natural Bliss line with three new coffee creamers: Chai Vanilla Latte, Chocolate Caramel Truffle, and Hazelnut Cookie Crumble (Zero Sugar), all made with just four simple ingredients. They’re available nationwide in 32-ounce bottles for about USD 5.99 and are designed for coffee as well as recipes like smoothies, frosting, and yogurt.
-
In October 2025, Starbucks launched new at-home coffee creamers, including Salted Pecan Creamer and Caramel Macchiato Creamer, expanding its retail coffee portfolio with popular café-inspired flavors. The creamers are available at Walmart, targeting consumers seeking convenient ways to recreate premium coffeehouse experiences at home.
U.S. Coffee Creamer Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.0 billion
Estimated market size in 2026
USD 1.1 billion
Projected market size by 2033
USD 1.6 billion
Growth rate
CAGR of 5.2% from 2026 to 2033
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, type, form, nature, flavor, packaging type, and distribution channel
Regional Scope
U.S.
Key companies profiled
Nestlé S.A.; Danone; Chobani LLC; Land O’Lakes, Inc.; Heartland Food Products Group; Leaner Creamer LLC; Califia Farms, LLC; nutpods; Starbucks Coffee Company; Laird Superfood
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Coffee Creamer Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the U.S. coffee creamer market report based on product, type, form, nature, flavor, packaging type, and distribution channel:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Dairy-based
-
Non-dairy
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
High-fat
-
Low-fat (<3 grams)
-
Fat-free (<0.5 grams)
-
-
Form Outlook (Revenue, USD Million, 2021 - 2033)
-
Liquid
-
Powder
-
-
Nature Outlook (Revenue, USD Million, 2021 - 2033)
-
Organic
-
Conventional
-
-
Flavor Outlook (Revenue, USD Million, 2021 - 2033)
-
Regular/Unflavored
-
Flavored
-
-
Packaging Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Plastic Jars
-
Tetrapacks
-
PET Bottles
-
Others (pouches)
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
B2B
-
B2C
-
Supermarkets and Hypermarkets
-
Convenience Stores
-
Online
-
Others
-
-
Research Methodology
The U.S. coffee creamer market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. coffee creamer segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Dairy-based
Coffee creamer companies generate revenue through the sale of dairy-based creamers to households, cafés, restaurants, and foodservice operators. Revenue is captured through retail bottles, multipacks, and larger foodservice formats. Different fat levels, flavors, and formulations allow manufacturers to address varied consumer preferences and usage occasions. Premium, flavored, and specialty dairy-based creamers can support higher selling prices and increase revenue per unit.
Non-dairy
Coffee creamer companies generate revenue through the sale of non-dairy creamers made from plant-based ingredients such as almond, oat, coconut, or soy across retail and foodservice channels. Revenue is captured through individual retail packs, multipacks, and commercial formats. Different plant bases, flavors, and formulations enable companies to target consumers seeking dairy alternatives and specific dietary preferences. Premium ingredients, clean-label positioning, and specialty formulations can support product differentiation and higher revenue potential.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
U.S. Coffee Creamer Consumer & Occasion Analysis
Mapped consumers by coffee preparation habits, purchase occasions, flavor preferences, health priorities, and willingness to trade up. Assessed how needs differ across daily at-home consumption, convenience-led usage, and café-style coffee occasions.
Enables sharper targeting by identifying which consumer occasions offer the strongest growth potential, helping brands align pack sizes, propositions, messaging, and innovation with specific usage moments.
U.S. Coffee Creamer Innovation & White-Space Assessment
Evaluated emerging opportunities across flavors, plant-based formulations, clean-label propositions, functional benefits, and new delivery formats. Benchmarked current offerings to identify areas where consumer expectations are not yet fully addressed.
Helps uncover innovation white spaces and differentiation opportunities, reducing reliance on incremental flavor launches and supporting a more focused product-development pipeline.
U.S. Coffee Creamer Pricing, Channel & Portfolio Strategy
Assessed price tiers, pack architecture, retailer/channel dynamics, promotional positioning, and the role of branded versus private-label products. Identified where premium, mainstream, and value propositions can coexist within the portfolio.
Supports portfolio optimization and revenue growth, helping determine where to premiumize, where to compete on value, and how channel-specific strategies can improve shelf productivity and margins.
Frequently Asked Questions About This Report
The liquid coffee creamer led the market with a 57.3% revenue share in 2025.
The B2B coffee creamer market is projected to grow at a CAGR of 5.6% from 2026 to 2033.
Key players include Nestlé S.A., Danone, Chobani LLC, Land O’Lakes, Inc., Heartland Food Products Group, Leaner Creamer LLC, Califia Farms, LLC, nutpods, Starbucks Coffee Company, and Laird Superfood.
The dairy coffee creamer market is projected to grow at the fastest CAGR of 3.7% from 2026 to 2033.
Non-dairy coffee creamer held the largest market share of 57.4% in 2025.
The U.S. coffee creamer market size was valued at USD 1.0 billion in 2025 and is estimated at USD 1.1 billion for 2026.
The U.S. coffee creamer market is expected to grow at a CAGR of 5.2% from 2026 to 2033, reaching USD 1.6 billion.
Key factors driving the U.S. coffee creamer market include rising at-home coffee consumption, demand for convenient and flavorful coffee experiences, growing popularity of plant-based and clean-label options, and increasing product innovation in flavors, formats, and functional ingredients.
The non-dairy coffee creamer market led with a 57.4% revenue share in 2025.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


