
- Home
- »
- Medical Devices
- »
-
U.S. Ophthalmic Devices And Eye Care Market Report, 2030GVR Report cover

U.S. Ophthalmic Devices And Eye Care Market (2025 - 2030) Size, Share & Trends Analysis Report By Product (Ophthalmic Devices, Eye Care), By Application (Cataract, Glaucoma, Refractive Disorders, Vitreo Retinal Disorders), By End-use, And Segment Forecasts
Market Size & Trends
The U.S. ophthalmic devices and eye care market size was estimated at USD 12.39 billion in 2024 and is projected to grow at a CAGR of 3.32% from 2025 to 2030. The U.S. market is growing due to the increasing prevalence of eye disorders such as cataracts, glaucoma, diabetic retinopathy, and refractive errors, fueled by the rising geriatric population more susceptible to these conditions. For instance, according to the CDC WONDER, Single-Race Population Estimates, 2023, around 17.7% of the country’s population was aged 65 years and above in 2023. In addition, growing awareness of eye health and strategic industry initiatives, such as innovative product launches and collaborations, contribute to market expansion.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
A primary driver for the market’s growth is the rapidly aging population. Individuals aged 65 and older are disproportionately affected by age-related eye conditions such as cataracts, age-related macular degeneration (AMD), glaucoma, and presbyopia, necessitating increased demand for diagnostic services, surgical interventions, and vision correction. According to the data published by the CDC in October 2024, in 2022, an estimated 4.22 million US adults (1.62%) had glaucoma, and 1.49 million (0.57%) had vision-affecting glaucoma. Similarly, the rising prevalence of systemic diseases such as diabetes contributes significantly to the burden of eye disease, particularly diabetic retinopathy, further boosting the need for specialized eye care and related devices. According to the International Diabetes Federation, the prevalence of diabetes in the U.S. is estimated to be around 13.7% in 2024, with approximately 38.5 million people living with the disease.
National Prevalence of Glaucoma in 2022 (95% Uncertainty Interval*)
All
Any Glaucoma
Vision-Affecting Glaucoma
Non-Vision-Affecting Glaucoma
4,225,000 (3,461,000-5,234,000)
1,488,000 (1,168,000-1,904,000)
2,737,000 (1,861,000-3,755,000)
Sex
Female
2,287,000 (1,774,000-2,872,000)
803,000 (607,000-1,052,000)
1,484,000 (910,000-2,135,000)
Male
1,938,000 (1,534,000-2,438,000)
685,000 (509,000-899,000)
1,253,000 (804,000-1,771,000)
Age
0-39 years
84,000 (55,000-119,000)
22,000 (0-77,000)
62,000 (6,000-114,000)
40-64 years
1,137,000 (874,000-1,452,000)
407,000 (289,000-560,000)
731,000 (430,000-1,066,000)
65-84 years
2,458,000 (1,912,000-3,118,000)
830,000 (616,000-1,094,000)
1,628,000 (1,010,000-2,345,000)
85 years and older
546,000 (380,000-756,000)
229,000 (156,000-320,000)
316,000 (134,000-542,000)
Source: CDC, Grand View Research Analysis
Moreover, the increasing product innovation by market players investing heavily in R&D to meet evolving clinical needs and consumer expectations significantly contributes to the growth of the U.S. ophthalmic devices and eye care industry. Market players are developing innovative solutions, leading to the development of innovative technologies, which is significantly increasing the adoption of advanced ophthalmic devices and eye care solutions in the U.S. For instance, in April 2025, BVI Medical received FDA 510(k) clearance for Leos, a breakthrough laser endoscopy ophthalmic system for glaucoma treatment. Leos offers superior eye visualization and minimally invasive pressure reduction, enhancing surgical precision. This device targets early-stage glaucoma and diverse types, with the U.S. commercial launch planned for 2025. Similarly, in January 2025, Norlase received FDA 510(k) clearance for LYNX, the world’s first battery-powered pattern scanning laser indirect ophthalmoscope. LYNX offers surgeons untethered, portable laser treatment with an ergonomic headset, wireless interface, and voice control, enhancing efficiency, comfort, and treatment speed in ophthalmic practices.
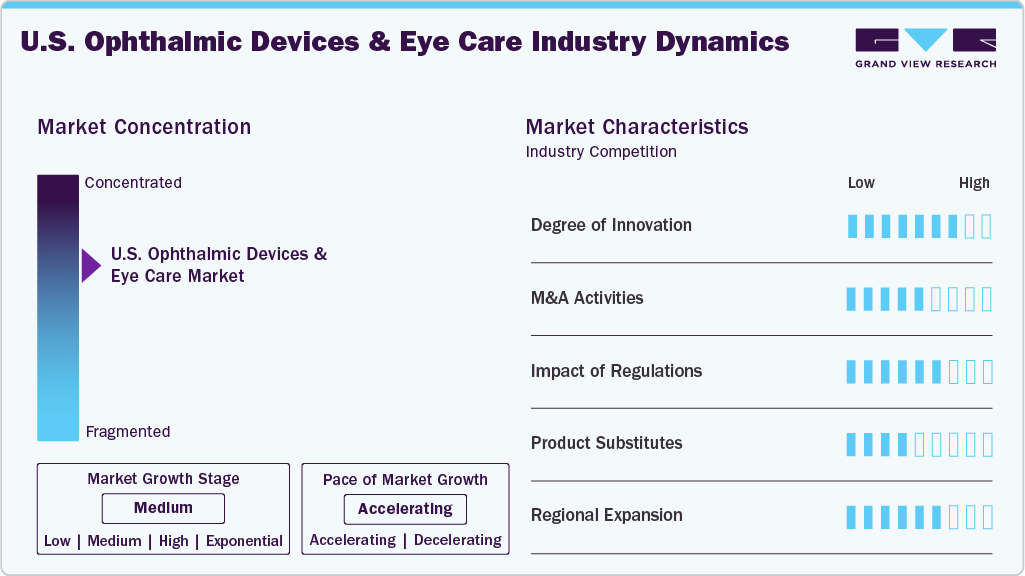
Market Concentration & Characteristics
The U.S. ophthalmic devices and eye care industry is characterized by increasing investments, a supportive regulatory framework, a growing focus on innovation, and an evolving competitive landscape. Moreover, the high prevalence of high disorders and an aging population in the country significantly increases the growth opportunities for the market.
The high degree of innovation in the U.S. ophthalmic devices and eye care industry is driven by advancements in technology and increasing demand for effective vision correction solutions. The integration of artificial intelligence (AI) in diagnostic tools has revolutionized how conditions such as diabetic retinopathy are detected, allowing for earlier intervention and improved patient outcomes. For instance, in May 2024, AEYE Health received FDA clearance for the first fully autonomous AI to diagnose diabetic retinopathy using handheld retinal cameras. The system demonstrated high sensitivity and specificity in trials and requires only one image per eye. It enables point-of-care, reimbursable screenings without dilation, enhancing accessibility and potentially preventing blindness. Furthermore, the rise of telemedicine platforms has expanded access to eye care services, enabling remote consultations and monitoring, which is significantly beneficial in underserved areas.
 To learn more about this report, Download Free Sample Report
The U.S. ophthalmic devices and eye care industry has witnessed a significant rise in mergers and acquisitions (M&A) activities, driven by technological advancements and an increasing demand for innovative solutions. For instance, in August 2024, Advancing Eyecare (AEC) acquired Eyefficient, expanding its ophthalmic equipment offerings and nationwide reach. Eyefficient, known for quality, affordable diagnostic instruments, will leverage AEC’s infrastructure to enhance customer support. This partnership strengthens AEC’s offerings in eyecare instrumentation, benefiting distributors and independent sales representatives with broader product access and services. The M&A landscape is also shaped by strategic partnerships that aim to address evolving consumer needs while enhancing competitive positioning within the market.
The regulatory landscape for U.S. ophthalmic devices and the eye care industry is primarily governed by the Food and Drug Administration (FDA), which classifies these devices into three categories based on risk: Class I, II, and III. This classification impacts market entry, as Class III devices require premarket approval (PMA), a process that can be lengthy and costly due to extensive clinical trials and data requirements. In addition, regulations surrounding reimbursement policies from Medicare and private insurers significantly influence market dynamics; devices that demonstrate clear clinical benefits are more likely to receive favorable reimbursement rates. Thus, companies need to manage regulatory hurdles and market access challenges to successfully launch new products in this competitive sector.
The U.S. ophthalmic devices and eye care industry faces significant threats from substitutes as advancements in technology and consumer preferences evolve. The increasing use of telemedicine for eye care consultations, which allows patients to receive assessments and prescriptions without traditional in-person visits offers a substitute for these devices as this shift reduces the demand for conventional eye examinations and encourages the adoption of home-based diagnostic tools, such as smartphone apps that can assess vision quality or detect common ocular conditions.
The U.S. ophthalmic devices and eye care industry is witnessing significant regional expansion, driven by increasing demand for advanced eye care solutions and a growing aging population. Companies are strategically enhancing their presence across various states to address the increasing demand for ophthalmic devices and eye care solutions. For instance, in March 2023, CooperVision announced that the company had increased the delivery times of Biofinity toric multifocal contact lenses by over 50% for U.S. and Canadian customers after moving the manufacturing to its advanced facility in Scottsville, New York, in late 2022. These made-to-order lenses ship within approximately one week, enhancing patient care with faster follow-ups and prescription adjustments. This move improves accessibility and satisfaction for eye care professionals and patients. As competition intensifies, these companies are expected to continue expanding their footprint across the U.S., aiming to capture a larger share of the market.
Product Insights
The eye care segment dominated the market with the largest revenue share of around 79.01% in 2024, owing to consistent demand for corrective and therapeutic products, especially contact lenses and intraocular lenses (IOLs). The contact lens demand is fueled by a large base of myopic and astigmatic patients, particularly in younger, working-aged populations seeking alternatives to eyeglasses for aesthetic and functional reasons. Similarly, intraocular lenses witness demand owing to the high volume of cataract surgeries, one of the most frequently performed procedures in the U.S. Compared to diagnostic or surgical ophthalmic devices, eye care products are consumables with repetitive usage patterns, which increases their demand in the market.
The ophthalmic devices segment is expected to witness significant CAGR growth over the forecast period, driven by rising demand for advanced diagnostic and surgical instruments. The increasing prevalence of age-related eye conditions such as cataracts, glaucoma, and age-related macular degeneration (AMD) fuels the need for precision equipment such as optical coherence tomography (OCT) systems, fundus cameras, and others. Moreover, the rising integration of AI-based image analysis for early detection of diabetic retinopathy and glaucoma in ophthalmic devices further fuels the segment growth. For instance, in January 2025, AI Optics’ portable Sentinel Camera received FDA 510(k) clearance. This handheld retinal imaging device captures high-quality images without eye dilation, integrates with EHR systems, and aims to improve retinal disease screening accessibility.
Application Insights
Cataract dominated the application segment in 2024 and is expected to witness the fastest CAGR owing to the high prevalence of age-related cataract among the aging population, which drives significant procedural volume and device demand. An estimated 20.5 million Americans aged 40 and older, representing 17.2% of this population, have cataracts in one or both eyes, and approximately 6.1 million (5.1%) have undergone surgery to remove their lens, according to CDC data from May 2024. This high prevalence of cataracts in the country’s population contributes to the segment growth in the market.
Refractive disorders is expected to witness significant CAGR owing to their high global prevalence and increasing diagnosis rates, particularly among younger populations. The widespread use of digital screens reduced outdoor activity, and aging demographics have led to a surge in conditions like myopia, hyperopia, and astigmatism. In response, there has been rapid innovation in both surgical and non-surgical corrective technologies-such as LASIK, SMILE, intraocular lenses, and advanced contact lenses-that offer improved safety, precision, and convenience.
End-use Insights
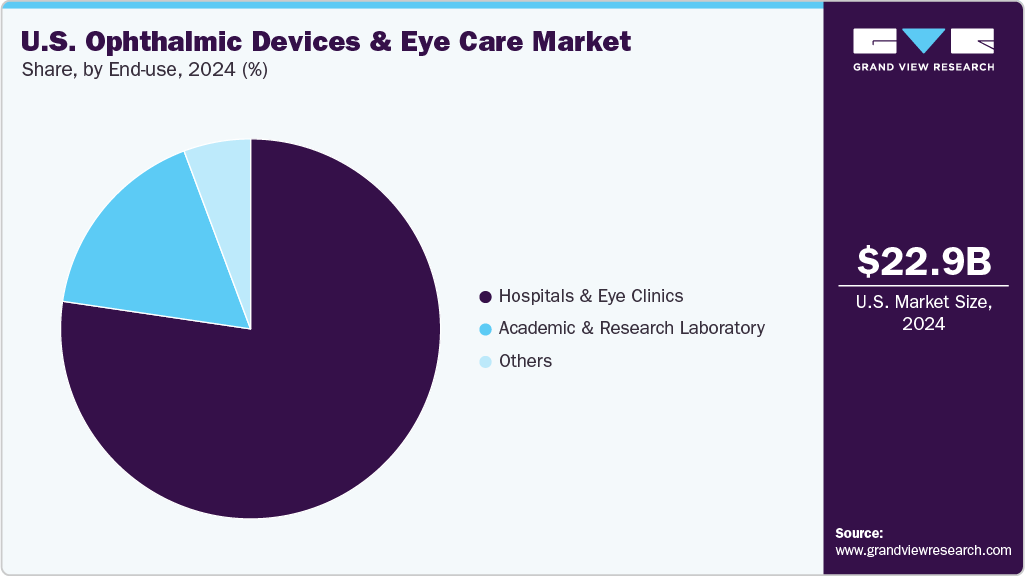
The retail & direct-to-consumer (DTC) segment dominated the market with the largest revenue share in 2024, owing to their convenience, accessibility, and growing consumer preference for at-home and self-service healthcare solutions. With the rise of online platforms and optical retail chains, consumers can easily access vision correction products like eyeglasses, contact lenses, and eye drops without visiting clinics. In addition, personalized eye care, subscription-based models, and digital eye exams have expanded the appeal of DTC options, especially among younger, tech-savvy demographics.
 To learn more about this report, Download Free Sample Report
The hospitals and eye clinics segment is expected to witness significant growth due to their central role in delivering advanced diagnostic and surgical eye care. These facilities are equipped with specialized instruments like OCT systems, phacoemulsification units, and laser platforms, enabling them to handle complex conditions such as cataracts, glaucoma, and retinal disorders. The rising number of ophthalmic surgeries, availability of skilled professionals, and expanding access to outpatient procedures are further driving demand in this segment.
Key U.S. Ophthalmic Devices And Eye Care Company Insights
Some of the leading market players include Alcon Vision, LLC; Johnson & Johnson Vision Care; and Bausch + Lomb, among others. These companies have utilized their technological expertise to establish a significant presence in this growing market. Their strategies include user-friendly solutions, emphasis on affordability, and improved accessibility, which ensure widespread adoption of their advanced products.
Key U.S. Ophthalmic Devices And Eye Care Companies:
- Johnson & Johnson Vision Care
- Alcon Vision LLC
- Carl Zeiss Meditec AG
- Bausch & Lomb Incorporated
- Essilor International
- Carl Zeiss Meditec AG
- Ziemer Ophthalmic Systems AG
- TOPCON Corporation
- Haag-Streit Group
- CooperVision, Inc.
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2025–2030 annual, 2024 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Recent Developments
-
In June 2025, Johnson & Johnson Vision Care launched Acuvue Oasys Max 1-Day, the first daily disposable contact lens designed for both astigmatism and presbyopia. Now available in the U.S., it offers all-day hydration, blue light filtering, and stable vision. A non-multifocal version will follow, expanding globally by next year.
-
In February 2025, Alcon Vision, LLC launched Voyager DSLT in the U.S., the first fully automated Direct Selective Laser Trabeculoplasty device for glaucoma and ocular hypertension. Eliminating the need for a gonio lens, Voyager streamlines treatment delivery.
-
In October 2024, Visionix launched the VX 610, a nonmydriatic automated fundus camera requiring only a 2-mm pupil and no dilation, using cross-polarized light. It features auto alignment, tablet control, a 45-degree field of view, and 90-degree mosaic imaging. Telehealth-ready, it supports diabetic retinopathy screening and integrates with EMRs.
-
In May 2024, Reichert Technologies announced the availability of the Reichert Tono-Vera Tonometer in the U.S. It offers objective, accurate intraocular pressure measurement with an ergonomic design and digital alignment. This device aims to improve glaucoma screening and management by providing reliable results and enhancing patient comfort during eye examinations.
-
In January 2024, Nidek Inc. commercially launched the Mirante Scanning Laser Ophthalmoscope (SLO) in the U.S. This multimodal platform integrates high-definition SLO and OCT with ultra-wide field imaging, capturing high-quality color, indocyanine green angiography, fluorescein angiography, Retro mode, fundus autofluorescence, and OCT images in a single capture. The device supports dynamic blood flow imaging and detailed retinal structure evaluation, enhancing diagnosis and management of retinal disease.
U.S. Ophthalmic Devices And Eye Care Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 12.82 billion
Revenue forecast in 2030
USD 15.10 billion
Growth rate
CAGR of 3.32% from 2025 to 2030
Actual Data
2018 - 2024
Forecast period
2025 - 2030
Quantitative units
Revenue in USD million/billion, and CAGR from 2025 to 2030
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end-use
Regional scope
U.S.
Key companies profiled
Johnson & Johnson Vision Care, Alcon Vision LLC, Carl Zeiss Meditec AG, Bausch & Lomb Incorporated, Essilor International, Ziemer Ophthalmic Systems AG, Nidek Co. Ltd, TOPCON Corporation, Haag-Streit Group, CooperVision, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Ophthalmic Devices And Eye Care Market Report Segmentation
This report forecasts revenue growth at a country level and analyzes the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the U.S. ophthalmic devices and eye care market report based on product, application, and end-use:
-
Product Outlook (Revenue, USD Million, 2018 - 2030)
-
Ophthalmic Devices
-
Optical Coherence Tomography Scanners
-
Fundus Cameras
-
Perimeters/Visual Field Analyzers
-
Autorefractors and Keratometers
-
Ophthalmic Ultrasound Imaging Systems
-
Tonometers
-
Slit Lamps
-
Phoropters
-
Wavefront Aberrometers
-
Optical Biometry Systems
-
Ophthalmoscopes
-
Lensmeters
-
Corneal Topography Systems
-
Specular Microscopes
-
Retinoscopes
-
-
Eye Care
-
Contact Lenses
-
Intraocular Lenses
-
Ocular Health Products
-
Others
-
-
-
Application Outlook (Revenue, USD Million, 2018 - 2030)
-
Cataract
-
Vitreo retinal disorders
-
Glaucoma
-
Refractive Disorders
-
-
End-use Outlook (Revenue, USD Million, 2018 - 2030)
-
Hospitals and Eye Clinics
-
Retail & Direct-to-Consumer (DTC)
-
Others
-
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


