
- Home
- »
- Biotechnology
- »
-
Apoptosis Assay Market Size And Share Report, 2026-2033GVR Report cover

Apoptosis Assay Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Kits, Reagents, Instruments), By Technique (Flow Cytometry, Spectrophotometry), By Type, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$7.0BMarket Estimate, 2026
$7.6BMarket Forecast, 2033
$13.9BCAGR, 2026–2033
9.1%Apoptosis Assay Market Summary
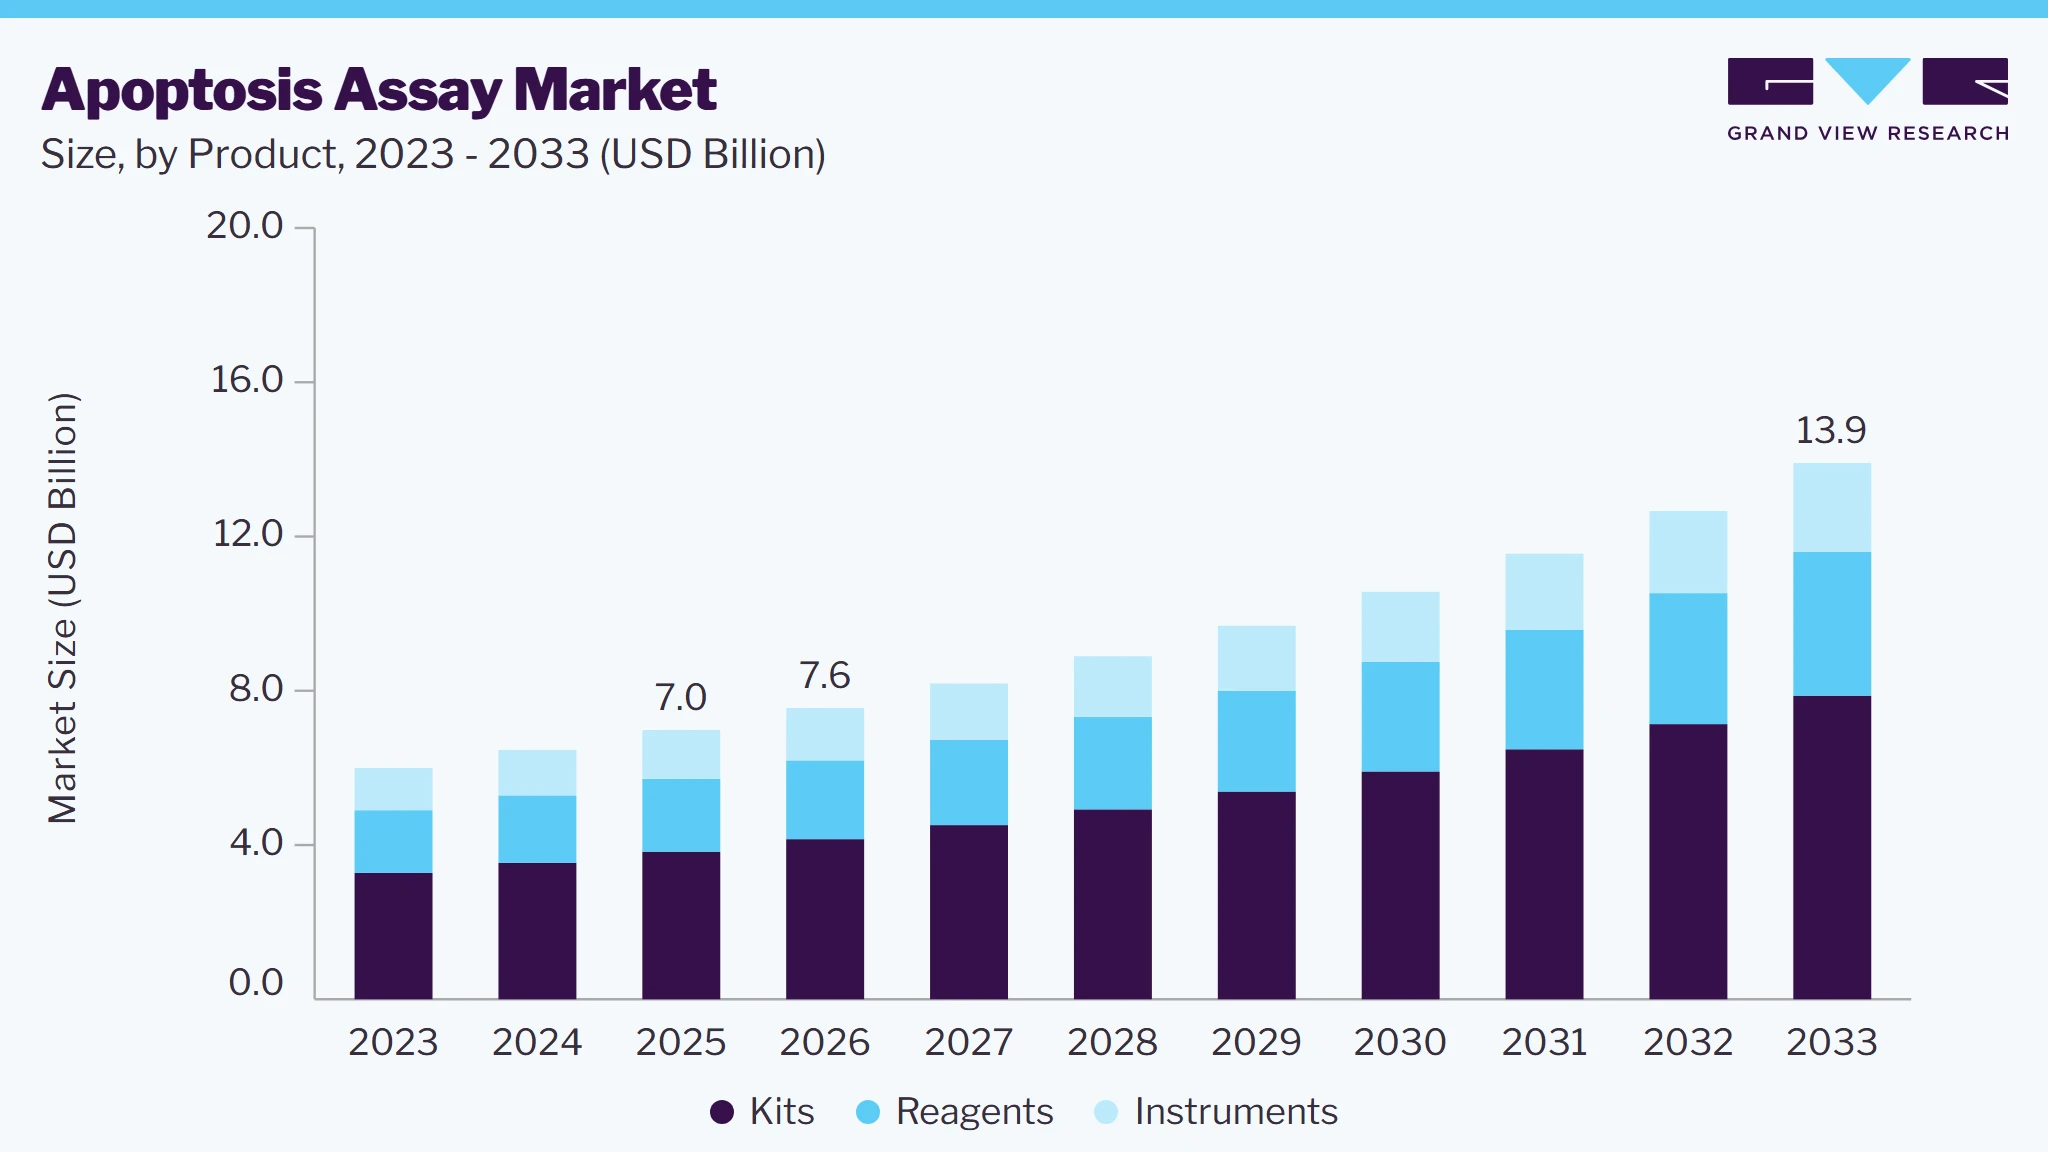
The global apoptosis assay market size was valued at USD 7.0 billion in 2025 and is projected to grow from USD 7.6 billion in 2026 to USD 13.9 billion by 2033, at a CAGR of 9.1% from 2026 to 2033. North America dominated the apoptosis assay market with the largest revenue share of 46.5% in 2025. The increasing prevalence of chronic diseases, including cancer and neurodegenerative disorders, is driving the expansion of the apoptosis assay industry.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Kits segment held the largest market share of 54.8% in 2025.
- By technique: Flow cytometry segment held the largest market share of 33.9% in 2025.
- By type: Caspase assays segment held the largest market share of 28.4% in 2025.
- By end use: Pharmaceutical and biotechnology companies segment held the largest market share of 49.6% in 2025.
Regional Highlights
- Largest regional market: North America (46.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 7.0 Billion
- Estimated market size in 2026: USD 7.6 Billion
- Projected market size by 2033: USD 13.9 Billion
- CAGR (2026-2033): 9.1%
Prism AI by Grand View Research Free to tryAsk a question about the apoptosis assay marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →As the demand for effective drug discovery and development rises, researchers rely on apoptosis assays to study cell death mechanisms and develop targeted therapies. Pharmaceutical and biotechnology companies are investing in advanced assay technologies to enhance precision and efficiency in evaluating therapeutic compounds. The growing need for personalized medicine further fuels market growth, as apoptosis is crucial in understanding disease progression and treatment responses. Advancements in molecular biology techniques are also contributing to the market's expansion.
 To learn more about this report, Download Free Sample Report
Moreover, technological innovations in apoptosis detection methods are driving the market forward. The introduction of high-throughput screening and flow cytometry-based assays enables researchers to analyze cell viability more accurately and quickly. Similarly, fluorescence and luminescence-based assays are gaining popularity due to their sensitivity and ability to detect early apoptotic events. Integrating artificial intelligence and automation in laboratory workflows enhances data analysis and minimizes human error. These advancements improve research outcomes, leading to a higher adoption rate of apoptosis assays across various scientific domains.
Another key growth driver is the increasing application of apoptosis assays in toxicology and drug safety assessment. Pharmaceutical companies use these assays to evaluate the cytotoxic effects of drug candidates during preclinical studies. The ability to detect apoptotic cell death helps identify potential adverse effects and optimize drug formulations. In addition, researchers in environmental sciences are utilizing apoptosis assays to assess the impact of pollutants and chemicals on human health. The expanding scope of applications across different industries supports market growth and innovation in assay development.
Market Dynamics
The apoptosis assay market is experiencing steady growth, driven by the increasing focus on drug discovery, toxicology studies, and disease pathogenesis research. Rising prevalence of cancer and other chronic diseases, coupled with growing investments in pharmaceutical and biotechnology R&D, is supporting the adoption of apoptosis assays across research and preclinical applications. Moreover, technological advancements in multiplex assay platforms, expanding biomarker research, and increasing demand for high-throughput screening solutions are expected to sustain market growth over the forecast period.
The growing adoption of flow cytometry, fluorescence imaging, and ELISA-based apoptosis detection methods is driving the apoptosis assay market by enabling rapid, accurate, and quantitative analysis of programmed cell death. Flow cytometry remains the preferred platform for Annexin V-based apoptosis detection, while fluorescence imaging enables real-time visualization of apoptotic events and ELISA-based assays support biomarker quantification. The increasing use of these technologies in oncology, drug discovery, immunology, and toxicology research is accelerating demand for high-throughput, sensitive, and reproducible apoptosis assays.
To address this growing demand, market participants are increasingly focusing on the development of advanced apoptosis detection products with enhanced multiplexing capabilities, analytical accuracy, and workflow efficiency. For instance, in May 2025, BioLegend updated its APC, PE, and FITC Annexin V Apoptosis Detection Kits with 7-AAD/PI, enhancing compatibility with multicolor flow cytometry and enabling improved discrimination of viable, early apoptotic, late apoptotic, and necrotic cells for research applications. This product enhancement strengthens multiplex cell analysis capabilities and supports high-throughput apoptosis detection workflows in oncology, immunology, and drug discovery research. Such advancements are improving assay sensitivity, workflow efficiency, and analytical accuracy, thereby accelerating the adoption of apoptosis assays across pharmaceutical, biotechnology, and academic research laboratories.
The technical complexity associated with apoptosis assays and the lack of standardized protocols remain key restraint for market growth. Different detection methods such as flow cytometry, fluorescence microscopy, ELISA, and caspase activity assays requires specialized instrumentation, optimized experimental conditions, and skilled personnel. Variations in sample preparation, assay selection, and data interpretation can affect the accuracy and reproducibility of results.
In addition, the absence of universally accepted assay protocols makes it difficult to compare results across laboratories and research studies. Differences in reagent quality, staining procedures, and analytical workflows may lead to inconsistent outcomes, limiting confidence in experimental data. These challenges increase validation time and operational costs, thereby restraining the global adoption of apoptosis assays, particularly in smaller research laboratories and resource-limited settings.
Analyst Perspective
Rising demand for reliable cell death analysis in pharmaceutical and biotechnology research is accelerating the adoption of advanced apoptosis assay kits, reagents, and detection platforms. Continuous advancements in fluorescence and flow cytometry-based assays, coupled with growing investments in precision medicine and biopharmaceutical R&D, are expected to support long-term market expansion. Market participants are focusing on developing highly sensitive, reproducible, and workflow-efficient assay solutions to meet the evolving needs of research and clinical laboratories.
Rising Prevalence Of Cancer And Chronic Diseases
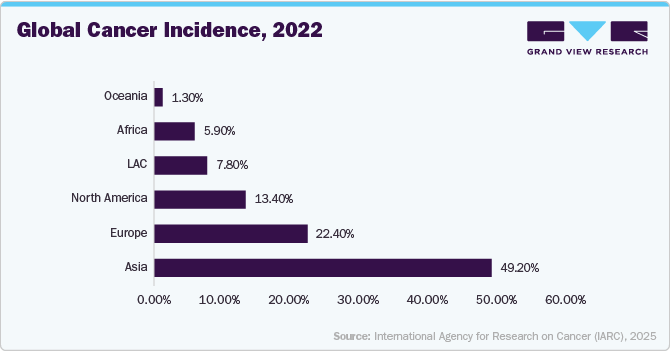
The increasing prevalence of cancer and other chronic diseases has significantly boosted the demand for apoptosis assays in research and diagnostics. According to the American Cancer Society, the number of cancer cases is predicted to reach 35 million by 2050 million. Apoptosis, or programmed cell death, plays a crucial role in understanding cancer progression and drug resistance.
 To learn more about this report, Download Free Sample Report
Source: International Agency for Research on Cancer (IARC), 2025
Researchers rely on apoptosis assays to develop targeted therapies that selectively induce cell death in cancerous cells. In addition, neurodegenerative diseases such as Alzheimer's and Parkinson's involve apoptosis dysregulation, further driving research in this field. As the global burden of these diseases rises, the need for apoptosis detection tools continues to grow.
Advancements in Molecular Biology And Drug Discovery
Technological advancements in molecular biology have led to the development of more precise and efficient apoptosis assay techniques. Flow cytometry, fluorescence microscopy, and high-throughput screening have improved the sensitivity and accuracy of apoptosis detection. These innovations allow researchers to study cell death mechanisms more effectively, accelerating drug discovery. Pharmaceutical and biotech companies increasingly use apoptosis assays to evaluate the efficacy of new cancer therapies. As new technologies emerge, the demand for advanced apoptosis assay solutions is expected to rise.
However, the high cost of apoptosis assay kits, reagents, and specialized instruments presents a barrier to market growth. Flow cytometers, fluorescence imaging systems, and other advanced tools required for apoptosis studies are expensive. Many small research laboratories and academic institutions struggle to afford these technologies, limiting their adoption. In addition, maintaining and calibrating these instruments adds to the overall expense. As a result, budget constraints in developing countries slow down market expansion to a certain extend.
Market Concentration & Characteristics
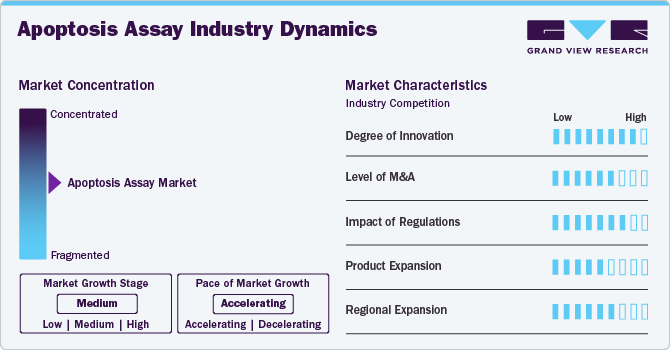
The apoptosis assay industry is marked by continuous innovation, with advancements in high-throughput screening, flow cytometry, and live-cell imaging techniques. Companies are integrating AI-driven analytics and automation to enhance accuracy and efficiency. Developing novel biomarkers and assay kits tailored for specific applications, such as cancer and neurodegenerative diseases, is driving differentiation. In addition, the emergence of 3D cell culture models further revolutionizes apoptosis research.
The apoptosis assay industry has witnessed moderate-to-high merger and acquisition (M&A) activity, with major biotech and pharmaceutical companies acquiring innovative assay developers and niche technology firms. These acquisitions help expand assay portfolios, enhance R&D capabilities, and strengthen market presence. Strategic collaborations with academic institutions and research organizations are also common. Such consolidations aim to accelerate product innovation and commercialization.
 To learn more about this report, Download Free Sample Report
Regulatory frameworks significantly influence the apoptosis assay industry, particularly in clinical research and drug discovery applications. Agencies such as the FDA and EMA impose strong guidelines to ensure assay validation, reproducibility, and accuracy. Compliance with Good Laboratory Practice (GLP) and ISO standards is crucial for manufacturers. Stringent regulations can extend product development timelines and enhance credibility and adoption in regulated sectors.
Companies diversify their product portfolios by offering multiplex assay kits, cell-based assays, and real-time apoptosis detection solutions. The demand for customized assays tailored to specific research needs is driving expansion. Innovations in reagent stability, automation, and assay sensitivity have broadened applications in oncology, immunology, and stem cell research. A growing demand for personalized medicine and drug screening also fuels this expansion.
Leading companies in the apoptosis assay industry are actively expanding their global footprint through acquisitions, partnerships, and direct investments. Major players such as Thermo Fisher Scientific, Bio-Rad, and Merck have strengthened their presence in Asia-Pacific by establishing research facilities and distribution networks in China, India, and South Korea. Similarly, European biotech firms are entering North America through strategic collaborations with research institutions. Emerging markets in Latin America and the Middle East also witness increased investments as companies seek to capitalize on growing biomedical research and healthcare infrastructure.
Product Insights
Based on product, the kits segment held the largest revenue share of over 54.8% in 2025, and it is expected to grow with the fastest CAGR over the forecast period, driven by the growing demand for ready-to-use solutions that simplify experimental workflows. Researchers prefer assay kits due to their convenience, reproducibility, and ability to generate reliable results. The increasing focus on drug discovery and personalized medicine has further accelerated the adoption of these kits. Advancements in assay technologies have led to the development of more sensitive and specific detection methods. Expanding research activities in academic institutions and pharmaceutical companies has increased market growth.
The reagents segment is projected to grow at a significant CAGR over the forecast period, fueled by the increasing demand for flexible and customizable assay solutions. Researchers prefer individual reagents to design experiments tailored to specific study requirements. The growing focus on mechanistic studies of apoptosis pathways in disease progression has increased the adoption of high-quality reagents. The expanding applications of apoptosis assays in cell-based research and drug screening have further supported this growth. The availability of a wide range of fluorogenic and colorimetric reagents has enhanced the sensitivity and accuracy of apoptosis detection. Continuous innovations in reagent formulations are expected to improve assay performance and drive market expansion.
Technique Insights
Based on technique, the flow cytometry segment held the largest revenue share of over 33.9% in 2025, which can be attributed to its ability to provide rapid and quantitative single-cell analysis. Researchers favor this technique for its capability to detect multiple apoptotic markers simultaneously. High-throughput capabilities have made flow cytometry an essential pharmaceutical and clinical research tool. Advancements in laser and detection technologies have improved sensitivity and accuracy, further increasing its adoption.
The fluorescence microscopy segment is projected to grow at the fastest CAGR over the forecast period due to the increasing adoption of live-cell imaging techniques in apoptosis research. Researchers use fluorescence microscopy to visualize apoptotic processes in real time, providing valuable insights into cellular responses. Advancements in fluorescent probes and imaging software have improved the resolution and specificity of apoptosis detection. The expanding use of this technique in neuroscience, oncology, and regenerative medicine has contributed to market growth. The ability to analyze spatial distribution and morphological changes in apoptotic cells has made fluorescence microscopy a preferred choice in research. The rising investment in high-content screening technologies is expected to drive further adoption of fluorescence-based apoptosis assays.
Type Insights
Based on type, the caspase assays segment held the largest revenue share of over 28.4% in 2025, which can be attributed to its critical role in measuring apoptotic activity. Caspases are key enzymes in programmed cell death, making their detection essential for apoptosis studies. Researchers widely use caspase assays in drug discovery and cancer research to evaluate therapeutic responses. The availability of highly sensitive luminescent and fluorometric caspase assays has improved detection accuracy. The increasing prevalence of cancer and inflammatory diseases has fueled demand for caspase-based apoptosis detection. Advancements in assay design have led to the development of multiplex platforms, further enhancing market adoption.
The mitochondrial assays segment is projected to grow at the fastest CAGR over the forecast period, due to the rising focus on mitochondrial dysfunction in disease pathology. Mitochondria play a central role in apoptosis, making their analysis crucial for understanding cell death mechanisms. Researchers utilize mitochondrial assays to investigate metabolic changes associated with apoptosis. The increasing application of these assays in neurodegenerative diseases and metabolic disorders has supported market expansion. Technological advancements have improved the sensitivity and specificity of mitochondrial membrane potential and cytochrome c release assays. The growing use of mitochondrial assays in drug toxicity screening has further accelerated their adoption.
End Use Insights
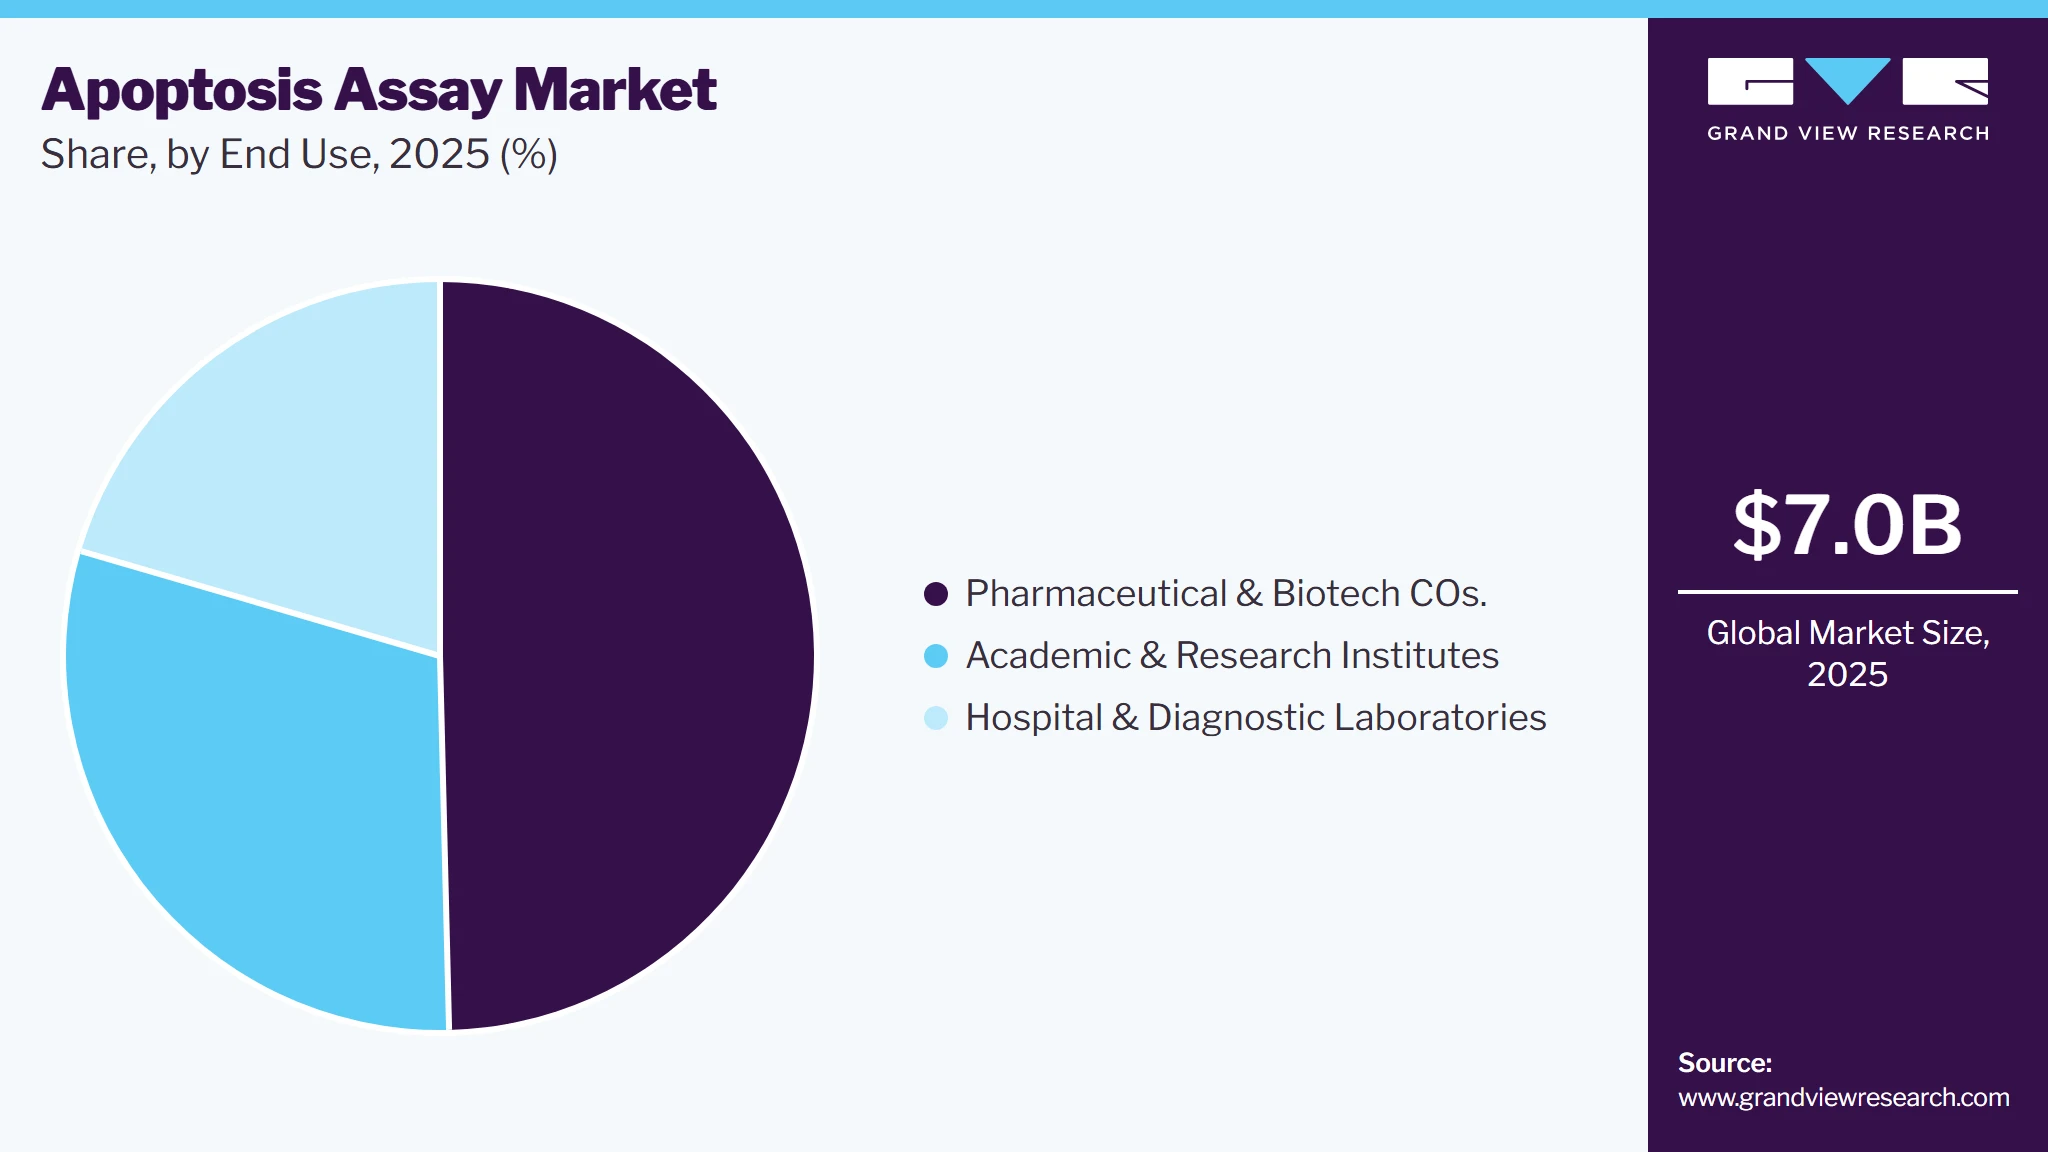
Based on end use, the pharmaceutical and biotechnology companies segment held the largest revenue share of over 49.6% in 2025, driven by the increasing need for apoptosis-based drug development and screening. Researchers in these industries rely on apoptosis assays to evaluate the efficacy and safety of new therapeutics. The rising demand for targeted cancer therapies has intensified the use of apoptosis assays in preclinical and clinical studies. Expanding research in immuno-oncology and neuropharmacology has further increased assay adoption. Integrating automation and high-throughput screening technologies has enhanced workflow efficiency in pharmaceutical research. The growing investment in biopharmaceutical innovation has contributed to the strong market presence of this segment.
 To learn more about this report, Download Free Sample Report
The hospital and diagnostic laboratories segment is projected to grow at the fastest CAGR over the forecast period, fueled by the rising adoption of apoptosis assays in clinical diagnostics. The increasing prevalence of cancer and autoimmune diseases has driven demand for apoptosis-based diagnostic tests. Researchers and clinicians use apoptosis assays to assess disease progression and treatment response. Technological advancements have improved assay sensitivity, enabling early detection of apoptotic markers in patient samples. The growing shift toward personalized medicine has led to increased adoption of apoptosis assays in clinical laboratories. Expanding diagnostic applications in hematology, oncology, and infectious diseases will drive market growth.
Regional Insights
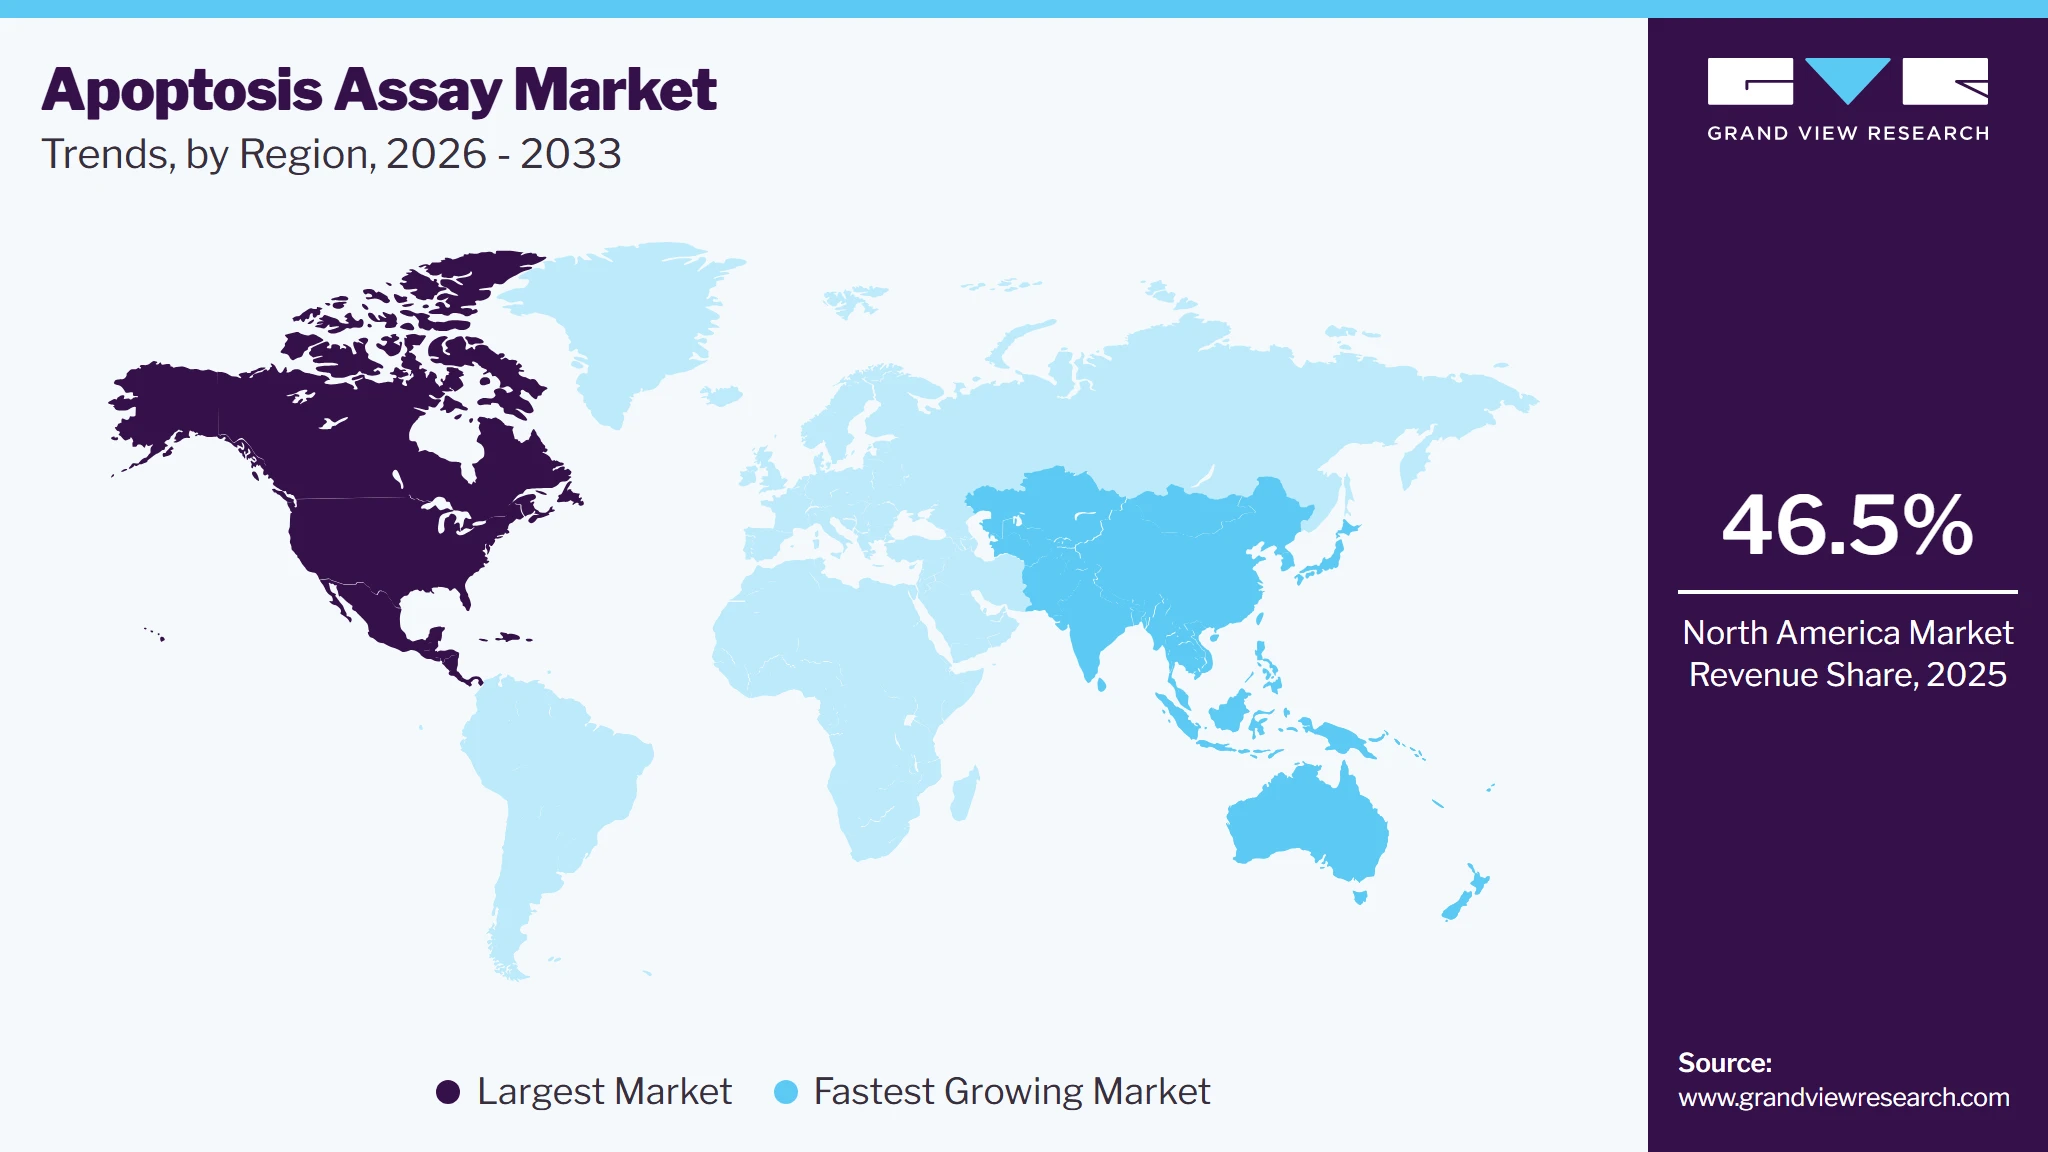
North America dominated the apoptosis assay market with the largest revenue share of 46.5% in 2025, due to the strong presence of pharmaceutical and biotechnology companies. Rising investments in cancer research and personalized medicine contribute to market expansion. The increasing prevalence of chronic diseases fuels the demand for advanced apoptosis detection methods. Technological advancements in flow cytometry and imaging systems enhance research efficiency. The availability of skilled professionals supports the adoption of apoptosis assays in research institutes. The region’s well-established healthcare infrastructure accelerates innovation and product adoption.
 To learn more about this report, Download Free Sample Report
U.S. Apoptosis Assay Market Trends
The apoptosis assay market in the U.S. held the largest share in the North America region in 2025. The apoptosis assay market in the U.S. holds a significant share, driven by high healthcare spending. The presence of leading biotech firms ensures continuous research and development in apoptosis-related studies. The growing burden of cancer and neurodegenerative disorders increases the demand for apoptosis assays. Academic institutions and research organizations actively explore novel apoptosis pathways. The expansion of drug discovery programs boosts assay adoption in preclinical studies. Advanced laboratory facilities enable accurate and efficient apoptosis analysis.
Europe Apoptosis Assay Market Trends
The apoptosis assay market in Europe exhibits steady growth due to increasing cancer prevalence. Rising investments in pharmaceutical research drive the demand for apoptosis-based diagnostic tools. The adoption of high-throughput screening methods enhances apoptosis research in drug discovery. Growing awareness about cell-based assays supports their usage in toxicology studies. The expansion of biotechnology firms strengthens apoptosis-related advancements. Improvements in laboratory automation accelerate apoptosis assay adoption across research facilities.
The UK apoptosis assay market significantly contributes to expanding biopharmaceutical sector. The rise in clinical trials for targeted therapies necessitates precise apoptosis detection techniques. The growing interest in regenerative medicine drives research in apoptosis modulation. The increasing burden of chronic diseases fuels apoptosis-related drug development efforts. Advanced microscopy and imaging systems improve assay sensitivity and accuracy. Strong academic collaborations foster innovation in apoptosis assay methodologies.
The apoptosis assay market in Germany is a well-established pharmaceutical industry and has strengthens its position in the German market. Continuous advancements in molecular biology techniques enhance apoptosis detection capabilities. The presence of leading life science companies supports the development of innovative assay technologies. The rising demand for personalized medicine increases apoptosis research applications. Expanding toxicology and safety assessment studies fuel the adoption of apoptosis assays. Investments in automation improve workflow efficiency in apoptosis-based research.
Asia Pacific Apoptosis Assay Market Trends
The apoptosis assay market in Asia Pacific is anticipated to grow at the fastest CAGR during the forecast period, due to rapid healthcare advancements. Increasing investments in biotechnology research accelerate apoptosis assay adoption. The rising incidence of cancer and infectious diseases drives demand for early detection tools. Expanding pharmaceutical manufacturing boosts the need for apoptosis-based drug screening. The region's growing clinical research sector enhances apoptosis assay utilization. Improvements in laboratory infrastructure support the development of novel apoptosis-based therapies.
The China apoptosis assay market is expanding due to a surge in biopharmaceutical research. Increasing cancer cases necessitate advanced apoptosis detection techniques for early diagnosis. The growing presence of contract research organizations accelerates apoptosis assay adoption. Rising investments in precision medicine strengthen apoptosis-related drug development. Expanding academic research initiatives enhances apoptosis pathway studies. The availability of cost-effective laboratory solutions supports overall market growth.
The apoptosis assay market in Japan strong focus on biomedical research drives the demand for apoptosis assays. The increasing prevalence of age-related diseases elevates apoptosis-related therapeutic developments. Technological innovations in imaging systems improve apoptosis detection accuracy. Expanding collaborations between research institutes and pharmaceutical companies boost assay utilization. The presence of advanced healthcare facilities enhances apoptosis-based clinical studies. Automation in laboratory workflows optimizes apoptosis assay performance.
Middle East and Africa Apoptosis Assay Market Trends
The apoptosis assay market in the Middle East and Africa is growing due to increasing investments in life sciences. Rising cancer prevalence fuels demand for apoptosis-based diagnostic tools. Expanding pharmaceutical and biotechnology industries accelerate apoptosis assay adoption. The development of specialized research centers strengthens apoptosis-based studies. Improvements in laboratory infrastructure enhance assay efficiency. Increasing clinical trials for targeted therapies drive the need for advanced apoptosis detection methods.
The Saudi Arabia apoptosis assay market is advancing with the expansion of biomedical research. The rising demand for precision medicine contributes to the adoption of apoptosis-based studies. Increasing investments in healthcare infrastructure support apoptosis research initiatives. The growing prevalence of chronic diseases elevates the need for apoptosis detection tools. Advancements in laboratory technologies improve the accuracy of apoptosis assays. Expanding pharmaceutical manufacturing enhances the adoption of apoptosis-based drug screening.
The apoptosis assay market in Kuwait is growing focus on healthcare research strengthens its apoptosis assay industry. The increasing incidence of cancer and metabolic disorders drives assay adoption. Expanding collaborations with international research organizations enhance apoptosis-based studies. The demand for high-throughput screening in drug discovery accelerates apoptosis assay utilization. Improvements in diagnostic laboratories contribute to efficient apoptosis detection. Rising investment in biomedical research supports apoptosis-based clinical applications.
Key Apoptosis Assay Company Insights
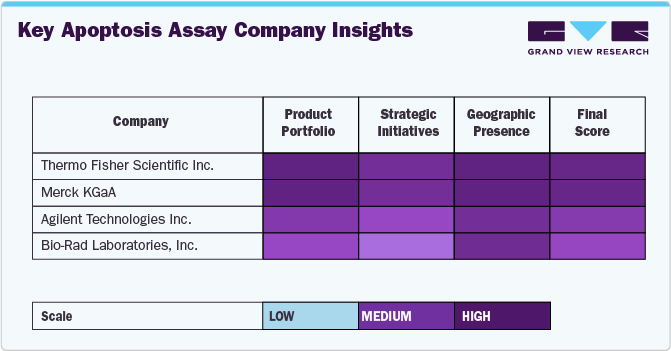
The below figure provides a comparative analysis of four major players in the apoptosis assays industry. Thermo Fisher Scientific Inc. scores high across all parameters, indicating a strong overall market position. Comprehensive product offerings, aggressive expansion strategies, and broad global reach make it a market leader. Merck KGaA is also positioned high in all three categories, reflecting significant investment in R&D and expansion. Agilent Technologies Inc.'s company positioning indicates a strong core offering but may be less aggressive in partnerships, acquisitions, or pipeline expansion. Whereas, Bio-Rad Laboratories, Inc. displays medium-to-high performance, particularly in strategic initiatives.
 To learn more about this report, Download Free Sample Report
Partnerships, collaborations, and product launches were the most adopted strategies by key players. Companies such as Bio-Rad Laboratories launched Annexin V conjugated to eight StarBright Dyes to enhance apoptosis detection via flow cytometry to expand their market reach globally.
Key Apoptosis Assay Companies
The following key companies have been profiled for this study on the apoptosis assay market.
-
Thermo Fisher Scientific, Inc.
-
Bio-Rad Laboratories
-
Bio-Techne
-
Biotium
-
GeneCopoeia, Inc.
-
Becton, Dickinson & Company (BD)
-
Promega Corporation
-
Sartorius AG
-
Merck KGaA
-
Abcam plc.
-
Takara Bio Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Thermo Fisher Scientific, Merck KGaA, BD, Bio-Rad Laboratories, etc.)
Strengthen market presence through strategic collaborations, product innovations, and integrated workflow solutions supporting oncology, immunology, and pharmaceutical research.
Broad product portfolios, established global distribution networks, and strong customer relationships across pharmaceutical, biotechnology, academic, and clinical research laboratories.
Intense competition and rapid technological advancements requiring continuous product innovation and portfolio upgrades.
Emerging Players (Biotium, GeneCopoeia, Abcam plc.)
Focus on specialized apoptosis detection reagents, fluorescent dyes, antibodies, and customized assay solutions for research applications.
Strong expertise in niche assay technologies and high-quality research reagents for apoptosis analysis.
Greater dependence on research-based demand and increasing competitive pressure from larger integrated market players.
Recent Developments
-
In August 2024, Bio-Rad Laboratories launched Annexin V conjugated to eight StarBright Dyes to enhance apoptosis detection via flow cytometry. These conjugates optimized laser utilization, minimized spillover, and improved data resolution. Hilary Mavor, Marketing Director of Bio-Rad’s Life Science Group, highlighted that this expansion provided researchers with greater flexibility and accuracy in apoptosis detection.
-
In January 2024, Thermo Fisher Scientific and C-CAMP announced a collaboration to establish a Centre of Excellence in Bengaluru and equip it with advanced flow cytometry and molecular biology solutions. This initiative aimed to accelerate biotechnology innovation and provide research and training opportunities for scientists in academia, start-ups, and biopharma.
-
In September 2022, Merck KGaA, Darmstadt, Germany, announced that xevinapant, an IAP inhibitor, enhanced apoptotic signaling and significantly improved survival in patients with unresected locally advanced squamous cell carcinoma of the head and neck when combined with chemoradiotherapy (CRT). The Phase II trial demonstrated that xevinapant promoted tumor cell apoptosis, leading to a five-year survival rate of 53% versus 28% in the placebo group.
Apoptosis Assay Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.0 billion
Estimated market size in 2026
USD 7.6 billion
Projected market size by 2033
USD 13.9 billion
Growth rate
CAGR of 9.1% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, technique, type, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, China, Japan, India, South Korea, Australia, Thailand, Brazil, Argentina, Saudi Arabia, South Africa, UAE, and Kuwait
Key companies profiled
Thermo Fisher Scientific, Inc.; Bio-Rad Laboratories; Bio-Techne; Biotium; GeneCopoeia, Inc.; Becton, Dickinson & Company (BD); Promega Corporation; Sartorius AG; Merck KGaA; Abcam plc.; Takara Bio Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Apoptosis Assay Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global apoptosis assay market report based on product, technique, assay type, end use, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Kits
-
Reagents
-
Instruments
-
-
Technique Outlook (Revenue, USD Billion, 2021 - 2033)
-
Flow Cytometry
-
Fluorescence Microscopy
-
Spectrophotometry
-
Other Techniques
-
-
Assay Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Caspase Assays
-
DNA Fragmentation Assays
-
Cell Permeability Assays
-
Mitochondrial Assays
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Pharmaceutical & Biotechnology Companies
-
Hospital & Diagnostic Laboratories
-
Academic & Research Institutes
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
-
Research Methodology
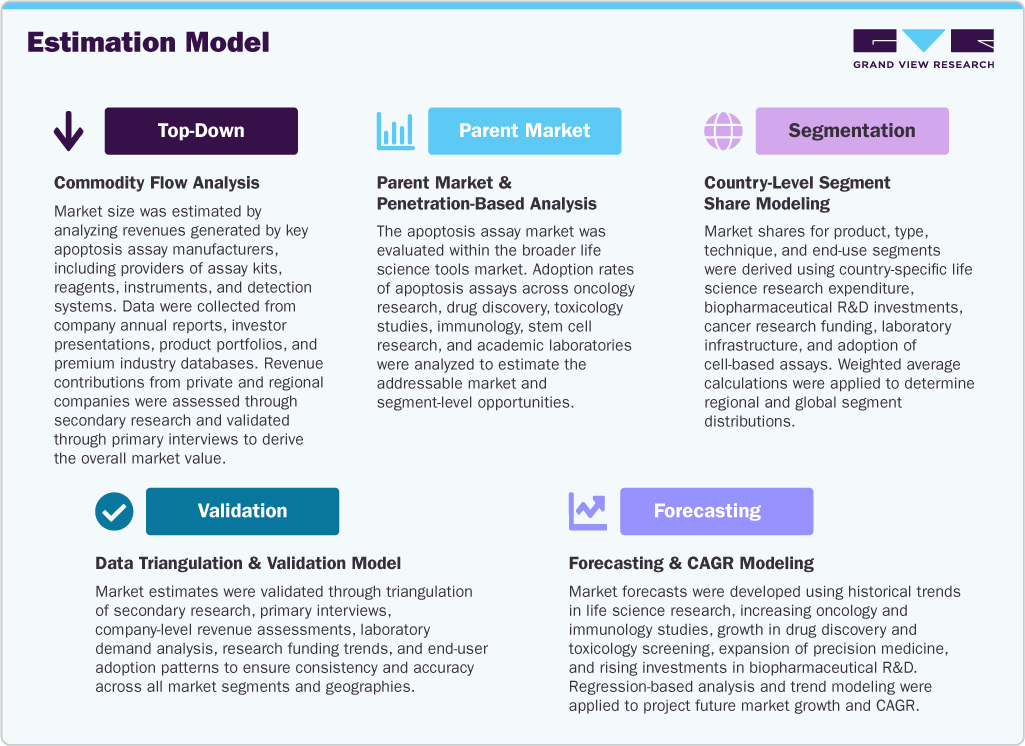
The apoptosis assay market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each apoptosis assay segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue Capture Definition
Kits
Revenue generated from ready-to-use apoptosis assay kits designed to detect and quantify programmed cell death using standardized protocols. These kits typically contain optimized reagents, controls, buffers, and detection components that support applications across basic research, drug discovery, toxicology studies, and clinical investigations.
Reagents
This segment captures income from consumable reagents used throughout apoptosis detection workflows, including fluorescent dyes, antibodies, enzymes, substrates, buffers, probes, and staining solutions. These products enable the identification and measurement of apoptotic biomarkers using multiple analytical techniques.
Instruments
Market value in this category stems from laboratory instruments utilized to perform, analyze, and interpret apoptosis assays. These systems support quantitative and qualitative assessment of apoptotic events and are widely employed in life science research, pharmaceutical development, and clinical laboratories.
Segment- Technique
Revenue Capture Definition
Flow Cytometry
Revenue generated from apoptosis assays performed using flow cytometry, enabling rapid multiparametric analysis of cell populations based on apoptosis-related biomarkers such as phosphatidylserine exposure, membrane integrity, mitochondrial potential, and intracellular protein expression.
Fluorescence Microscopy
This segment captures income from apoptosis detection methods that utilize fluorescence microscopy to visualize cellular morphology, nuclear condensation, membrane alterations, and other apoptotic features at the single-cell level.
Spectrophotometry
Market value in this category stems from spectrophotometric techniques used to quantify apoptosis-related enzymatic activity, colorimetric reactions, and absorbance-based cellular responses during programmed cell death studies.
Other Techniques
Revenue originates from apoptosis assay methods beyond conventional analytical platforms, including luminescence-based assays, high-content imaging, ELISA, western blotting, and other specialized technologies employed for apoptosis detection and characterization.
Segment- Type
Revenue Capture Definition
Caspase Assays
Revenue generated from assays designed to detect and quantify caspase enzyme activity, enabling the evaluation of apoptosis initiation and progression in research, drug screening, and disease studies.
DNA Fragmentation Assays
This segment reflects earnings from assays used to identify DNA fragmentation, a characteristic feature of programmed cell death, through techniques that assess DNA cleavage and nuclear degradation.
Cell Permeability Assays
Market value arises from assays that evaluate changes in cell membrane integrity and permeability associated with apoptotic and late-stage cell death processes, supporting cytotoxicity assessment and therapeutic evaluation.
Mitochondrial Assays
Revenue originates from assays used to assess mitochondrial membrane potential, cytochrome c release, oxidative stress, and other mitochondrial events involved in apoptosis signaling pathways.
Segment- End Use
Revenue Capture Definition
Pharmaceutical & Biotechnology Companies
Revenue generated from apoptosis assay products utilized by pharmaceutical and biotechnology companies for drug discovery, lead optimization, toxicity testing, mechanism-of-action studies, and development of oncology, immunology, and cell-based therapeutics.
Hospital & Diagnostic Laboratories
This segment captures income from apoptosis assays used in hospitals and diagnostic laboratories for disease research, biomarker evaluation, clinical investigations, and laboratory-based assessment of apoptosis-related disorders.
Academic & Research Institutes
Market value in this category stems from apoptosis assay products employed by universities, government laboratories, and research institutes conducting studies in cancer biology, immunology, neuroscience, molecular biology, regenerative medicine, and other life science disciplines.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis for product at end use level
Provided cross-segmentation analysis mapping product categories against end-use segments to quantify revenue contribution and adoption trends across each end-user group.
Enabled identification of high-growth end-use opportunities, improved competitive benchmarking, and supported targeted go-to-market and investment strategies.
Competitive Benchmarking & Portfolio Assessment of Apoptosis Assay Manufacturers
Comprehensive benchmarking of leading apoptosis assay companies based on assay portfolio, technology capabilities, pricing strategy, geographic presence, innovation pipeline, distribution network, strategic collaborations, product launches, and M&A activities. Includes comparison across kits, reagents, instruments, and advanced apoptosis detection technologies.
Supports competitive positioning, identifies portfolio gaps and whitespace opportunities, benchmarks innovation leadership, and helps clients refine product differentiation, partnership, licensing, and market expansion strategies.
Regional Demand & End-User Opportunity Assessment
Customized regional and country-level assessment covering North America, Europe, Asia Pacific, Latin America, and MEA with analysis of research funding, cancer burden, biopharmaceutical R&D investments, regulatory environment, laboratory infrastructure, and adoption of apoptosis assays by pharmaceutical companies, research institutes, and clinical laboratories.
Helps clients identify high-growth regional markets, optimize commercialization strategies, prioritize country-level investments, and align market expansion plans with evolving research, diagnostic, and drug discovery demand.
Frequently Asked Questions About This Report
The global apoptosis assay market is expected to grow at a CAGR of 9.1% from 2026 to 2033, reaching USD 13.9 billion by 2033.
The caspase assay segment dominated the apoptosis assay market with a share of 28.4% in 2025. This is attributed to the substantial number of research activities that back the significance of caspase in activation of programmed cell death.
Some key players operating in the apoptosis assay market includeThermo Fisher Scientific, Inc.; Bio-Rad Laboratories; Bio-Techne; Biotium; GeneCopoeia, Inc.; Becton, Dickinson & Company (BD); Promega Corporation; Sartorius AG; Merck KGaA; Abcam plc.; Takara Bio Inc.
Key factors that are driving the apoptosis assay market growth include the proven potential of cell-death assays in designing therapeutic strategies, wide acceptance of clinically useful cytoprotective & cytotoxic agents, and the advent of novel radionuclide tracers such as, caspase inhibitors & radiolabeled annexin V.
The kits segment held the largest revenue share of over 54.8% in 2025, and it is expected to grow with the fastest CAGR over the forecast period.
The flow cytometry segment held the largest revenue share of over 33.9% in 2025.
The pharmaceutical and biotechnology companies segment held the largest revenue share of over 49.6% in 2025.
North America dominated the apoptosis assay market with the largest revenue share of 46.5% in 2025.
The global apoptosis assay market size was valued at USD 7.0 billion in 2025 and is estimated at USD 7.6 billion for 2026.
About the Author(s)
Biotechnology Research Team
Healthcare · BiotechnologyThis report was authored by the biotechnology research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the biotechnology segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


