
- Home
- »
- Automotive & Transportation
- »
-
Automotive Instrument Cluster Market Report, 2026-2033GVR Report cover

Automotive Instrument Cluster Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Analog, Digital, Hybrid), By Vehicle Type (Scooter, Buses, Motorcycle, Passenger Car), By Propulsion Type (ICE, Electric), By Region, And Segment Forecasts
Market Size, 2025
$9.1BMarket Estimate, 2026
$9.7BMarket Forecast, 2033
$17.7BCAGR, 2026–2033
8.9%Automotive Instrument Cluster Market Summary
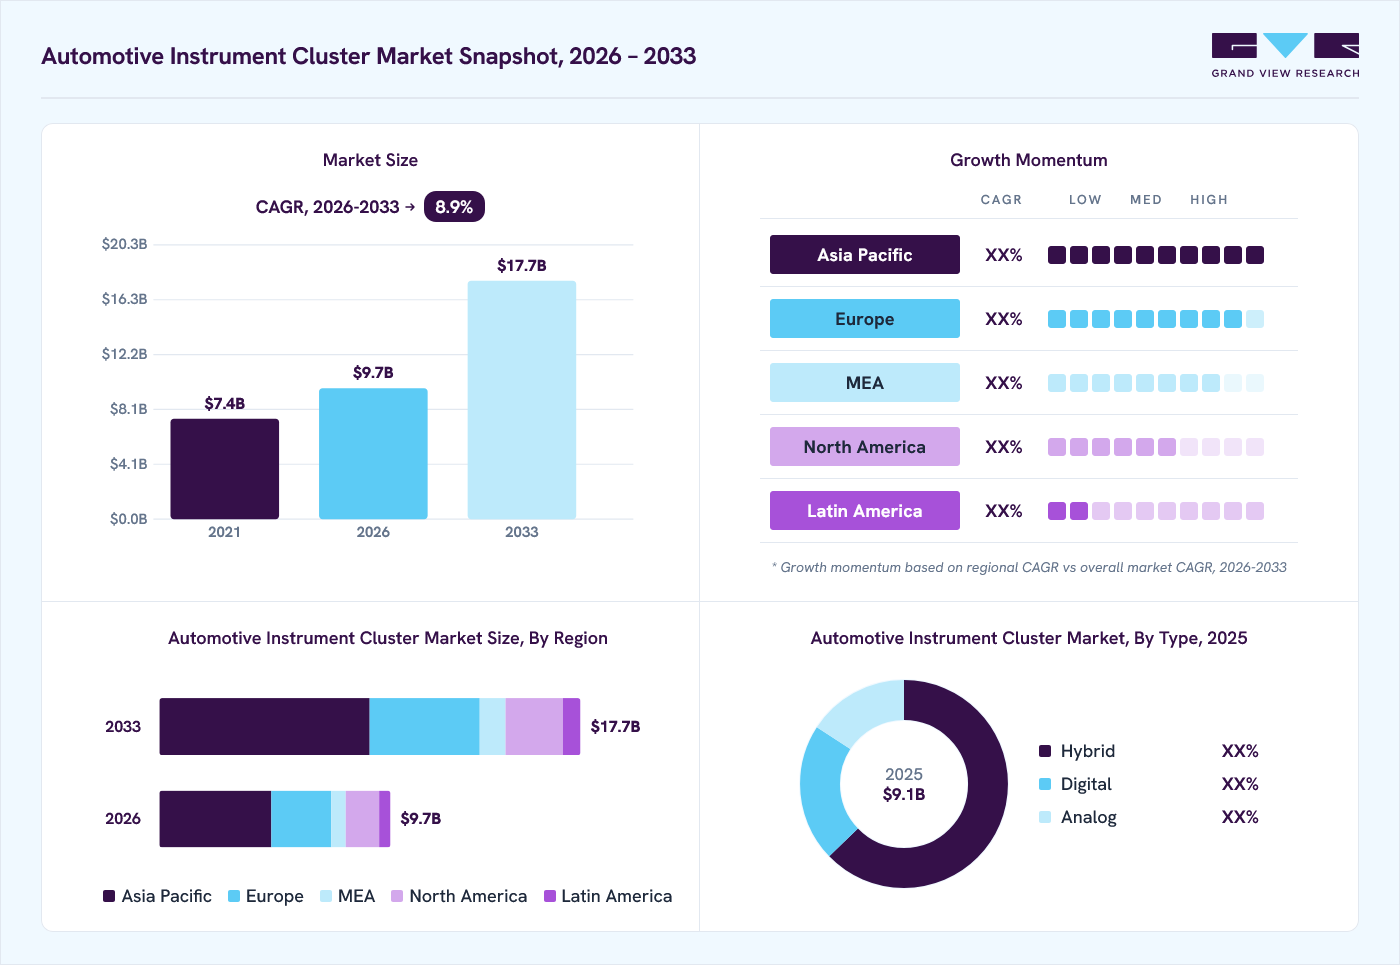
The global automotive instrument cluster market size was valued at USD 9.1 billion in 2025 and is projected to grow from USD 9.7 billion in 2026 to USD 17.7 billion by 2033, at a CAGR of 8.9% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 48.5% in 2025. The rapid pace of technological advancement is a primary factor driving the demand for automotive instrument cluster.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: hybrid segment dominated the market, with a revenue share of 62.7% in 2025.
- By vehicle type: Passenger Cars segment held the largest market share of 53.3% in 2025.
- By propulsion type: ICE segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (48.5% revenue share, 2025)
- By country: The China is the fastest growing country in 2025.
Market Size & Forecast
- Market size in 2025: USD 9.1 Billion
- Estimated market size in 2026: USD 9.7 Billion
- Projected market size by 2033: USD 17.7 Billion
- CAGR (2026-2033): 8.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Innovations in display technology, such as OLED and LCD screens to create high-resolutions and vibrant displays that can convey a wealth of car information are driving the market growth. Furthermore, advancements in microprocessors and software have enabled the development of sophisticated instrument clusters that can process and display data in real-time. Modern consumers have high expectations for their vehicles, seeking features that enhance both functionality and aesthetics. The demand for enhanced user experience is driving manufacturers to develop instrument clusters to develop instrument clusters that are not only informative but also visually appealing and customizable. Consumers expect their vehicle’s interface to be intuitive and easy to use, similar to their smartphones and other personal devices.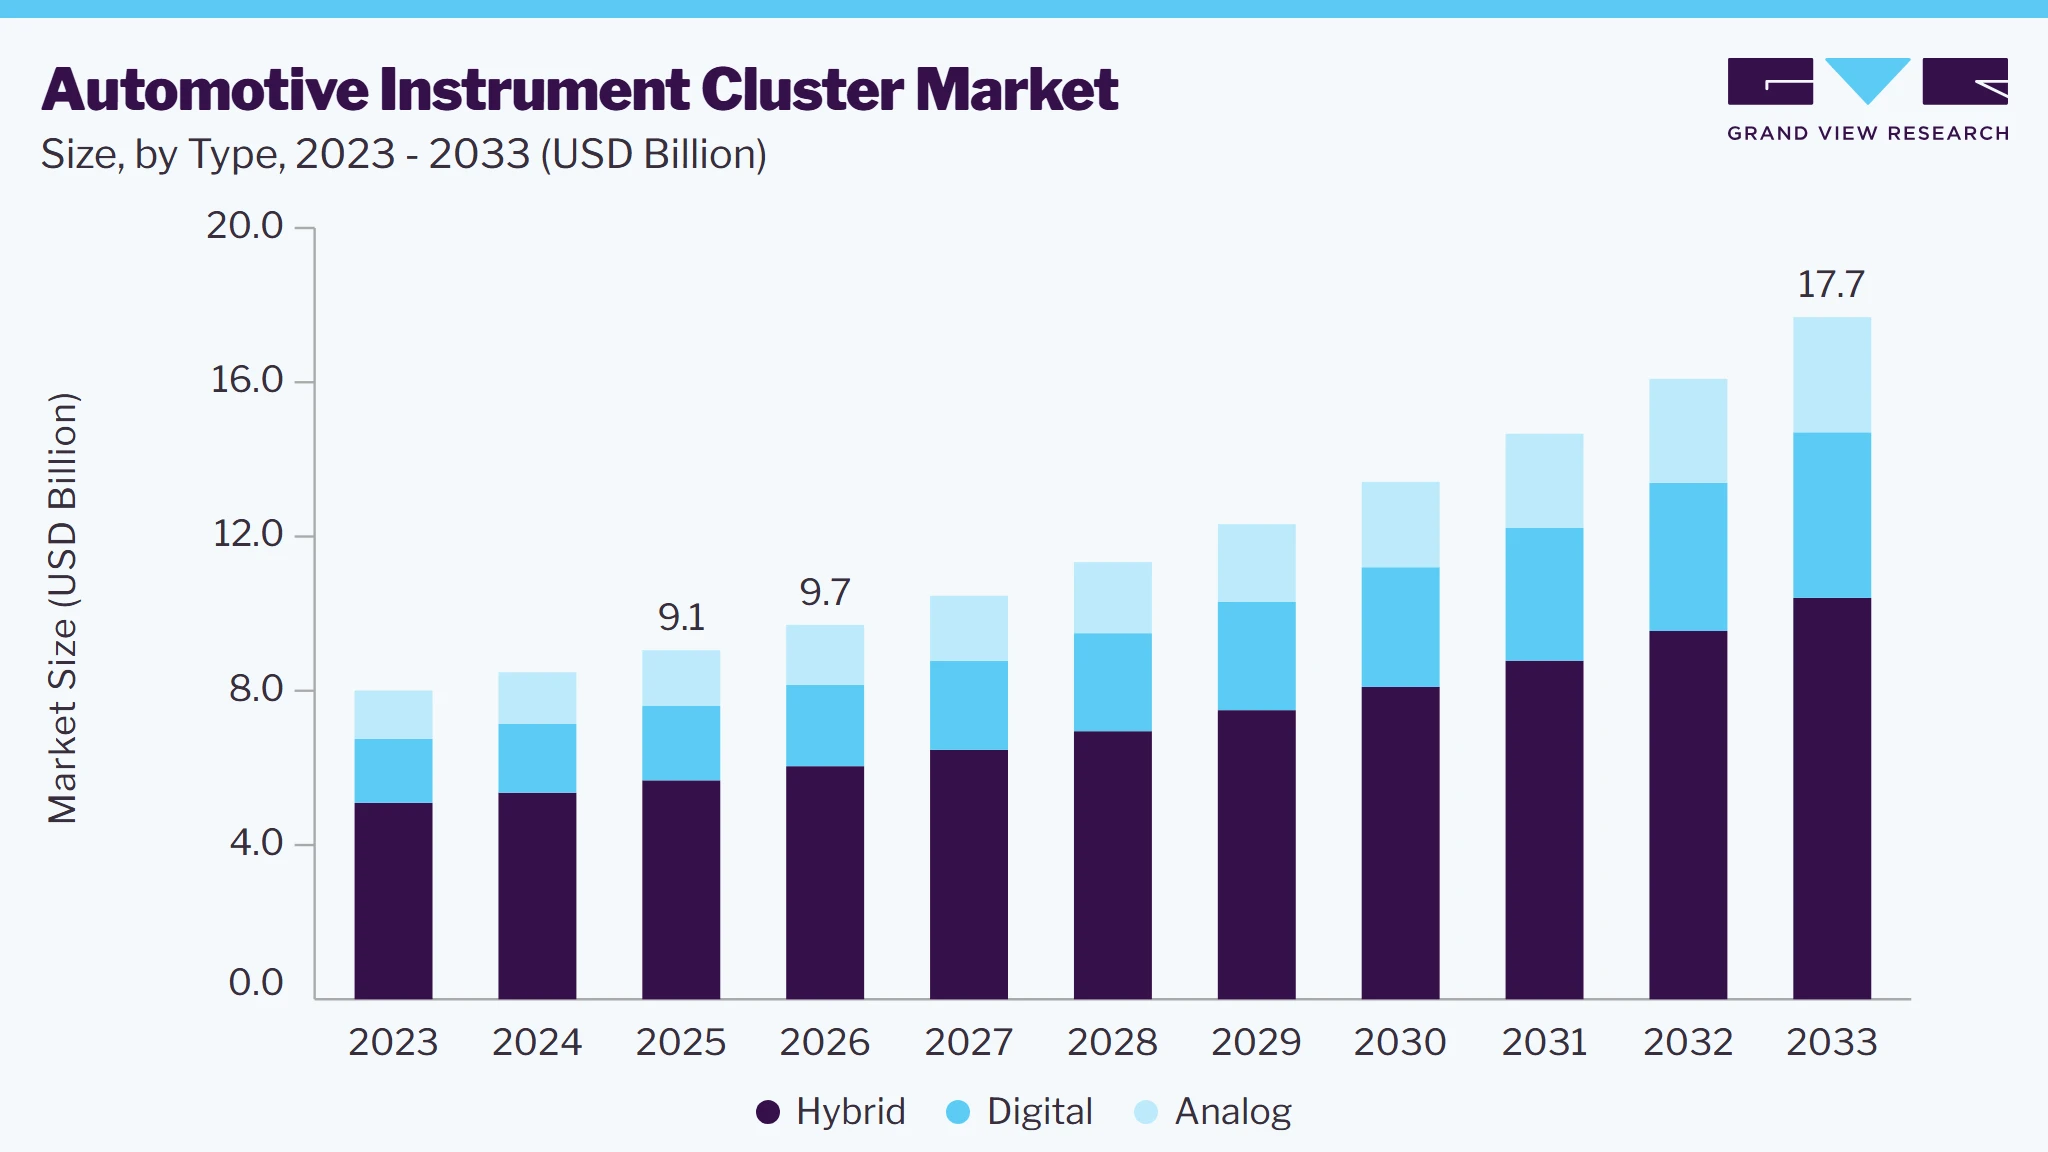 To learn more about this report, Download Free Sample Report
The emphasis on user experience (UX) is increasingly influencing the design and functionality of automotive instrument clusters. Manufacturers are focusing on creating intuitive interfaces that are easy to navigate and reduce driver distraction. Features such as voice recognition, touch-sensitive controls, and haptic feedback are being incorporated to enhance the overall driving experience.
Stringent safety regulations imposed by governments and regulatory bodies are driving the development of advanced instrument clusters. Regulatory standards such as the European New Car Assessment Program (Euro NCAP) and the National Highway Traffic Safety Administration (NHTSA) in the U.S. require vehicles to meet specific safety criteria. Instrument clusters play a vital role in complying with these standards by providing essential safety information and alerts to drivers. The need to adhere to these regulations is pushing manufacturers to innovate and improve their instrument cluster offerings.
Rising concerns about environmental sustainability and the implementation of stringent emission standards are influencing the design of instrument clusters. Modern clusters are equipped with features that promote fuel-efficient driving, such as real-time fuel consumption displays and eco-driving indicators. These features encourage drivers to adopt more sustainable driving practices, contributing to reduced emissions and improved fuel economy. The push for greener vehicles is thus driving the demand for instrument clusters that support eco-friendly driving.
Market Dynamics
Advancements in digital display technologies, human-machine interface (HMI) systems, connected vehicle platforms, artificial intelligence, augmented reality, and advanced driver assistance systems (ADAS) are significantly enhancing the functionality, user experience, safety, and real-time information delivery capabilities of automotive instrument clusters across passenger cars, commercial vehicles, and electric vehicles. The integration of high-resolution TFT-LCD displays, OLED panels, configurable digital cockpits, head-up display (HUD) connectivity, and vehicle telematics enables improved driver awareness, navigation support, vehicle diagnostics, and personalized driving experiences. Furthermore, increasing adoption of software-defined vehicles and over-the-air (OTA) update capabilities is accelerating the transition from conventional analog clusters to fully digital and intelligent cockpit systems.
The increasing integration of digital cockpit systems and connected vehicle technologies is a key factor driving the growth of the automotive instrument cluster market. Automakers are increasingly replacing conventional analog gauges with fully digital and hybrid instrument clusters to enhance driver experience, improve vehicle functionality, and provide real-time access to critical vehicle information. Rising consumer demand for advanced infotainment, navigation, vehicle diagnostics, and personalized driving interfaces is accelerating the adoption of sophisticated instrument cluster solutions across passenger and commercial vehicles.
The market is also benefiting from the growing penetration of advanced driver assistance systems (ADAS), which require instrument clusters to display safety alerts, navigation guidance, collision warnings, lane departure notifications, and other critical driving information in a clear and intuitive manner. As vehicles become more connected and software-driven, instrument clusters are evolving into central information hubs that seamlessly integrate data from multiple vehicle systems, improving driver awareness and operational safety.
The high cost associated with the development, integration, and deployment of advanced automotive instrument cluster systems is a major factor restraining the growth of the automotive instrument cluster market. Modern digital instrument clusters incorporate sophisticated hardware components, including high-resolution displays, graphics processing units (GPUs), sensors, electronic control units (ECUs), and advanced software platforms, significantly increasing system costs compared to conventional analog clusters. These higher costs can limit adoption, particularly in entry-level and budget vehicle segments where cost optimization remains a key purchasing criterion.
The market also faces challenges related to the increasing complexity of vehicle electronics and software integration. Instrument clusters must seamlessly communicate with infotainment systems, ADAS platforms, telematics modules, navigation systems, and other vehicle control units while maintaining high reliability and functional safety standards. Ensuring compatibility across multiple vehicle architectures requires extensive engineering, testing, and validation efforts, increasing development timelines and expenses for automotive OEMs and suppliers.
The rapid growth of electric vehicles (EVs), connected vehicles, and software-defined vehicle architectures is creating significant opportunities for the market. As vehicle manufacturers increasingly focus on delivering enhanced digital experiences, instrument clusters are evolving from basic information displays into intelligent driver interaction platforms capable of presenting real-time vehicle, navigation, safety, and connectivity data. This transformation is driving demand for advanced digital and fully configurable instrument cluster solutions across multiple vehicle categories.
The accelerating adoption of EVs presents a particularly strong growth opportunity. Electric vehicles require instrument clusters that can display battery status, charging information, driving range, energy consumption, regenerative braking performance, and route-based energy management insights. As global EV production continues to expand, demand for specialized digital displays and customized user interfaces is expected to increase substantially.
Analyst Perspective
The automotive instrument cluster market is witnessing strong growth driven by the rising adoption of digital cockpits, connected vehicles, ADAS, and software-defined vehicle architectures. Automakers are replacing traditional analog gauges with digital and hybrid instrument clusters to enhance driver experience, real-time information access, and vehicle functionality. Advancements in TFT-LCD, OLED, 3D displays, augmented reality, and customizable HMI solutions, along with integration of connectivity, telematics, navigation, cloud services, and OTA updates, are transforming instrument clusters into intelligent information hubs in modern vehicles.
Type Insights
Based on type, the hybrid segment led the market with the largest revenue share of 62.7% in 2025. Hybrid instrument clusters offer a range of benefits, including enhanced customization, better aesthetics, and the ability to display a wide variety of information. They allow manufacturers to integrate advanced features such as navigation, multimedia, and connectivity options directly into the dashboards. This transition is driven by consumer demand for modern and tech-savvy vehicles.
The digital segment is projected to witness the highest growth rate from 2026 to 2033. The digital instrument cluster represents a significant technological advancement that has driven substantial innovation in automotive dashboards. It delivers a clear and concise display of vehicle parameters to the driver, strategically timed to minimize driver distraction and enhance the overall driving experience. A digital instrument cluster enhances functionality beyond that of analog and hybrid models, offering a distinct competitive advantage and differentiation in the automotive market. Such benefits offered by digital automotive instrument clusters are expected to contribute to the segment’s growth.
Vehicle Type Insights
Based on vehicle type, the passenger cars segment led the market with the largest revenue share of 53.3% in 2025. Automotive instrument clusters play a crucial role in passenger cars, providing drivers with essential information for safe and efficient driving. These clusters display vital data such as speed, fuel levels, engine temperature, and warning indicators, ensuring the driver is always aware of the vehicle’s status. Passenger car instrument clusters cater to diverse applications, from sedans and SUVs to sports cars and luxury vehicles, each with specific requirements and features. Thus, factors such as technological advancements, increased passenger car production, rising demand for connected and autonomous vehicles, and a heightened focus on improving driving experience and safety can be attributed to the segment’s growth.
The three-wheeler segment is projected to witness significant growth from 2026 to 2033. Automotive instrument clusters play a crucial role in three-wheeled vehicles, providing riders with essential information for safe and efficient operation. The segment's growth can be attributed to the growing demand for and production of three-wheelers in developing countries across the globe. In addition, as the demand for electric three-wheelers continues to grow, the importance of intuitive and informative instrument clusters becomes paramount in meeting the needs of this evolving market segment.
Propulsion Type Insights
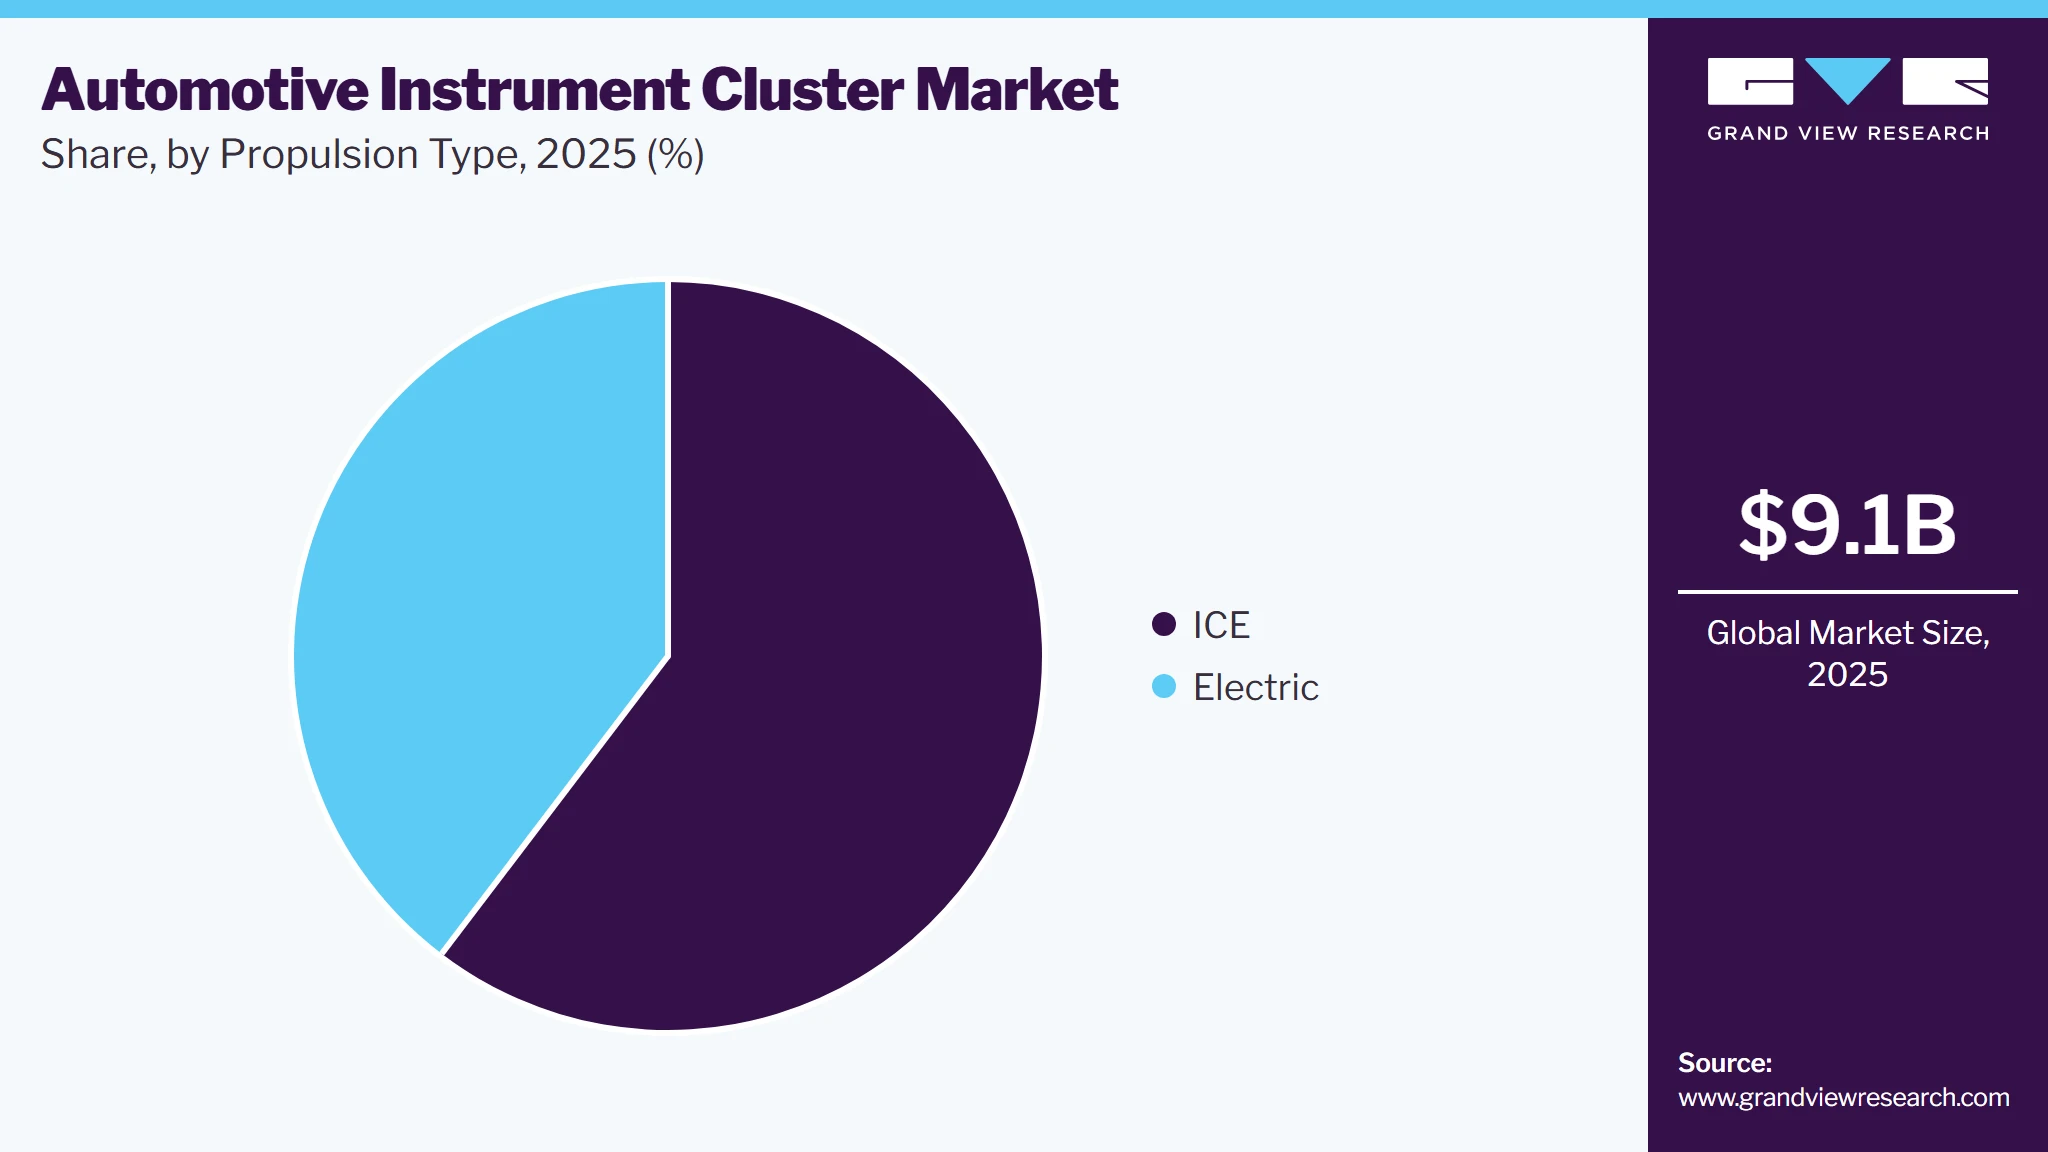
Based on propulsion type, the ICE segment led the market with the largest revenue share of 60.1% in 2025. The automotive instrument cluster in ICE vehicles typically displays vital information such as speed, engine RPM, fuel level, and temperature. It also includes warning lights and indicators to alert the driver of any issues with the vehicle's systems. The segment's growth can be attributed to the increasing use of analog instrument clusters with physical gauges and dials in traditional ICE vehicles.
 To learn more about this report, Download Free Sample Report
The electric vehicle (EV) segment is projected to witness significant growth from 2026 to 2033. The growing popularity of electric vehicles is a significant driver for the automotive instrument cluster market. EVs require specialized instrument clusters that provide information on battery status, range, charging status, and energy consumption. As the adoption of EV accelerates, the demand for advanced instrument clusters that cater to the unique requirements of electric drivetrains is expected to rise over the forecast period. This shift towards electrification is creating new opportunities for innovation in the instrument cluster market.
Regional Insights
North America automotive instrument cluster market is expected to witness steady growth from 2026 to 2033. The growing demand for electric vehicles in the region is a major driver, as EVs require advanced instrument clusters to display crucial data such as battery status and range. In addition, the growing preference for digital and hybrid instrument clusters among consumers, which offer enhanced functionality and customization, is further fueling market growth in the region.
U.S. Automotive Instrument Cluster Market Trends
The automotive instrument cluster market in the U.S. is expected to grow at a significant CAGR from 2026 to 2033. Supportive government policies promoting the adoption of EVs, and advanced automotive technologies can be attributed to the market’s growth. In addition, the vast presence of major automakers and technology companies in the U.S. is further creating favorable environments for the growth of the market in the country.
Asia Pacific Automotive Instrument Cluster Market Trends
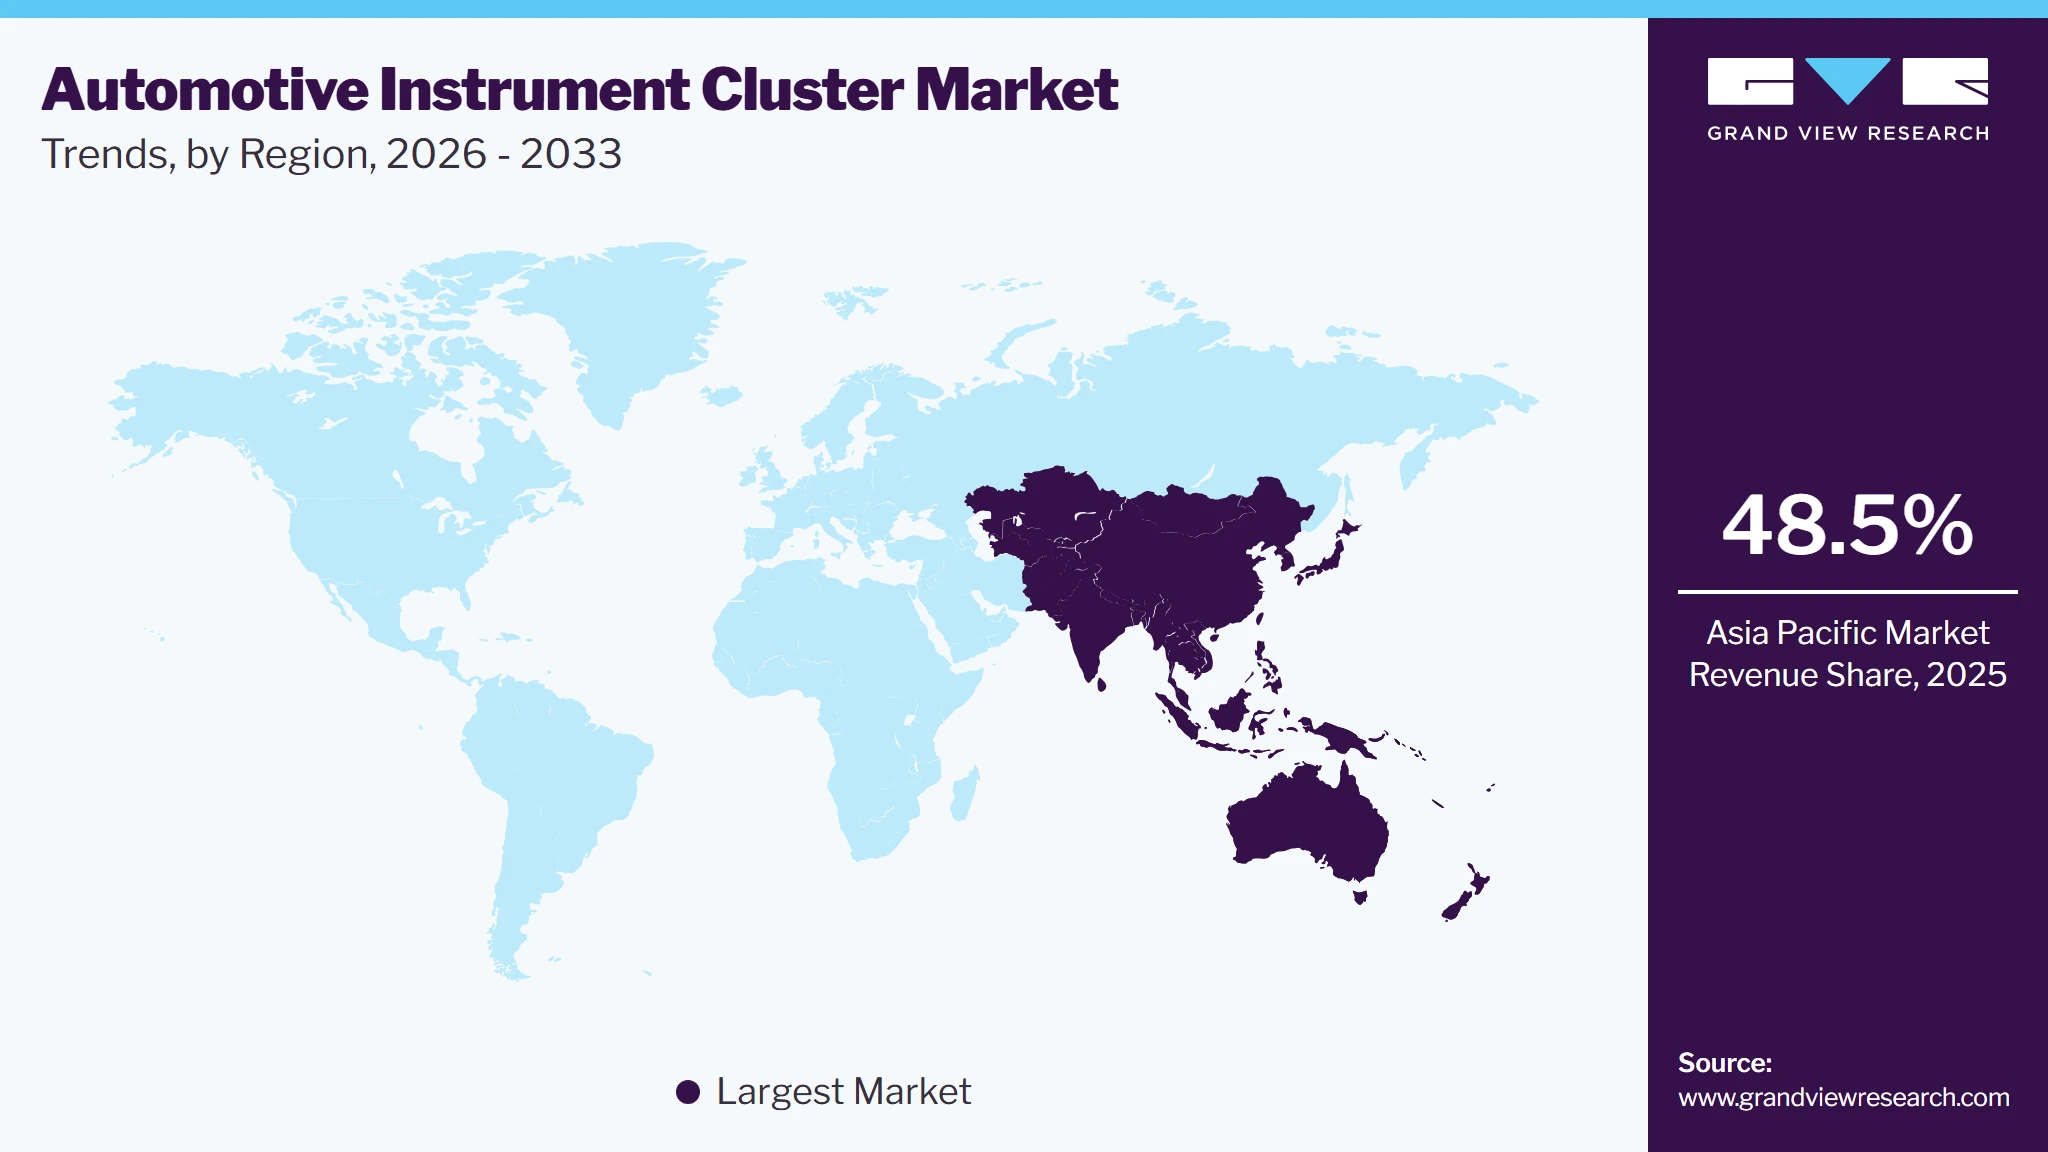
The automotive instrument cluster market in Asia Pacific dominated the global industry in 2025 and accounted for a 48.5% share of the global revenue. The robust automobile manufacturing presence in the region, led by countries such as China, India, and Japan, is a significant driver for the market. India is the fastest growing country in the Aisa Pacific automotive instrument cluster market. In addition, the surging sales of passenger cars across the region, coupled with the increasing urban population and improving living standards, are expected to boost the growth of the market from 2026 to 2033.
 To learn more about this report, Download Free Sample Report
Europe Automotive Instrument Cluster Market Trends
The automotive instrument cluster market in Europe is expected to grow at a significant CAGR from 2026 to 2033. Europe is home to several prominent luxury car brands, such as Audi AG, BMW AG, and Mercedes-Benz, which have a strong demand for advanced instrument cluster technologies. In addition, Europe is known for its rapid adoption of advanced technologies, which is driving the demand for innovative and feature-rich instrument cluster solutions in the automotive industry. Thus, factors such as the region's strong luxury car manufacturing presence, rapid technology adoption, and the established presence of companies such as Continental AG and Robert Bosch GmbH are expected to contribute to the market's growth in the region.
Key Automotive Instrument Cluster Company Insights
Key players operating in the automotive instrument cluster market include Continental AG, Denso Corporation, JP Minda Group, Nippon Seiki Co., Ltd., Panasonic Corporation, Pricol Limited, Robert Bosch GmbH, Simco Ltd., Valid Manufacturing Ltd., and Visteon Corporation. The companies are focusing on various strategic initiatives, including new product development, partnerships & collaborations, and agreements to gain a competitive advantage over their rivals. The following are some instances of such initiatives.
-
In November 2023, at EVangelise '23, hosted by iCreate in Ahmedabad, the Bengaluru-based startup Auklr Technologies unveiled an advanced intelligent instrument cluster designed to transform the driving experience for electric vehicles.
-
In August 2023, TVS Motor Company, an Indian automotive manufacturer, introduced the TVS X, an electric two-wheeler. Built on an entirely new platform, the TVS X features the 10.25-inch instrument cluster, supporting the company's in-built navigation system, NavPro, among other features.
Key Automotive Instrument Cluster Companies
The following key companies have been profiled for this study on the automotive instrument cluster market.
-
Continental AG
-
Denso Corporation
-
JP Minda Group
-
Nippon Seiki Co., Ltd.
-
Panasonic Corporation
-
Pricol Limited
-
Robert Bosch GmbH
-
Simco Ltd.
-
Valid Manufacturing Ltd.
-
Visteon Corporation
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (Continental AG, Visteon Corporation, DENSO Corporation)
- Focus on developing advanced digital instrument clusters, fully configurable cockpit displays, integrated HMI platforms, and connected vehicle solutions.
- Continuous investment in display technologies such as TFT-LCD, OLED, 3D visualization, augmented reality integration, software-defined vehicle architectures, and ADAS-compatible cockpit systems.
- Strong relationships with global automotive OEMs and extensive experience in vehicle electronics integration.
- Broad product portfolios spanning instrument clusters, infotainment systems, telematics, cockpit domain controllers, and digital cockpit platforms.
- High R&D and engineering costs associated with advanced display technologies, software development, and cybersecurity requirements.
- Dependence on vehicle production cycles and OEM sourcing decisions.
Emerging Players (Nippon Seiki Co., Ltd., Pricol Limited, Simco Ltd.)
- Focus on niche digital cockpit technologies, HMI software platforms, next-generation display interfaces, touch-enabled controls, and customizable instrument cluster solutions.
- Emphasis on software innovation, user experience enhancement, lightweight electronics integration, and EV-focused cockpit applications.
- Greater agility in adopting new technologies and responding to evolving OEM requirements.
- Limited manufacturing scale and global market reach compared with established Tier-1 suppliers.
Automotive Instrument Cluster Market Report Scope
Report Attribute
Details
Market size in 2025
USD 9.1 billion
Estimated Market size in 2026
USD 9.7 billion
Projected Market size by 2033
USD 17.7 billion
Growth rate
CAGR of 8.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, Vehicle Type, Propulsion Type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; Italy China; Japan; India; Australia; South Korea; Australia; Brazil; Kingdom of Kingdom of Saudi Arabia (KSA); UAE; South Africa
Key companies profiled
Continental AG; Denso Corporation; JP Minda Group; Nippon Seiki Co., Ltd.; Panasonic Corporation; Pricol Limited; Robert Bosch GmbH; Simco Ltd.; Valid Manufacturing Ltd.; Visteon Corporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Instrument Cluster Market Report Segmentation
The report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global automotive instrument cluster market report based on type, vehicle type, propulsion type, and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Analog
-
Digital
-
Hybrid
-
-
Vehicle Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Scooter
-
Motorcycle
-
Three Wheeler
-
Passenger Car
-
Buses
-
Trucks
-
-
Propulsion Type Outlook (Revenue, USD Million, 2021 - 2033)
-
ICE
-
Electric
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Kingdom of Saudi Arabia
-
South Africa
-
-
Research Methodology
The automotive instrument cluster market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each automotive instrument cluster segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Type
Revenue Capture Definition
Analog
This segment captures revenue generated from analog automotive instrument clusters that utilize traditional electromechanical gauges, needles, and indicator systems to display vehicle information such as speed, fuel level, engine temperature, and RPM. These clusters are primarily used in entry-level passenger vehicles, motorcycles, commercial vehicles, and cost-sensitive automotive segments where affordability, durability, and simplicity are prioritized.
Digital
This segment includes revenue derived from fully digital automotive instrument clusters equipped with TFT-LCD, OLED, or other advanced display technologies. These systems provide customizable interfaces, real-time vehicle diagnostics, navigation data, ADAS alerts, connectivity features, and enhanced graphical visualization. Digital clusters are increasingly deployed across premium, luxury, electric, and connected vehicle platforms to improve driver experience and functionality.
Hybrid
This segment captures revenue generated from hybrid automotive instrument clusters that combine conventional analog gauges with digital display screens. These systems offer a balance between traditional instrument readability and modern digital functionality, enabling the display of vehicle information, infotainment content, navigation guidance, and safety notifications while maintaining familiar analog interfaces.
Segment- Vehicle Type
Revenue Capture Definition
Scooter
This segment captures revenue generated from automotive instrument clusters installed in scooters, including conventional and electric models. These clusters provide information related to speed, battery status, fuel level, trip data, navigation, and vehicle diagnostics while supporting increasing digitalization within urban mobility solutions.
Motorcycle
This segment includes revenue derived from instrument clusters integrated into motorcycles across commuter, premium, sports, touring, and electric categories. These systems display critical riding information such as speed, RPM, fuel consumption, navigation, ride modes, connectivity features, and vehicle health monitoring.
Three Wheeler
This segment captures revenue generated from instrument clusters used in passenger and cargo three-wheelers. These clusters support vehicle operation by displaying speed, battery or fuel status, maintenance alerts, trip information, and operational diagnostics, particularly as electrification increases within the three-wheeler market.
Passenger Cars
This segment includes revenue derived from automotive instrument clusters installed in hatchbacks, sedans, SUVs, crossovers, luxury vehicles, and electric passenger cars. Instrument clusters in this segment increasingly incorporate digital displays, ADAS integration, connected vehicle functions, navigation systems, and personalized user interfaces.
Buses
This segment captures revenue generated from instrument clusters deployed in public transportation, transit, school, coach, and electric buses. These systems provide drivers with operational data, vehicle diagnostics, route information, safety alerts, fleet management integration, and energy consumption monitoring.
Trucks
This segment includes revenue derived from instrument clusters installed in light-duty, medium-duty, and heavy-duty trucks. These solutions support commercial vehicle operations through real-time monitoring of vehicle performance, fuel efficiency, payload information, maintenance schedules, telematics integration, and driver assistance functionalities.
Segment- Propulsion
Revenue Capture Definition
ICE
This segment captures revenue generated from automotive instrument clusters installed in internal combustion engine (ICE) vehicles powered by gasoline, diesel, or alternative combustion fuels. These clusters display conventional vehicle information such as engine speed, fuel level, engine temperature, maintenance alerts, navigation guidance, and driver assistance notifications.
Electric
This segment includes revenue derived from automotive instrument clusters integrated into battery electric vehicles (BEVs), plug-in hybrid electric vehicles (PHEVs), and other electrified vehicle platforms. These systems provide specialized information including battery state of charge, driving range, charging status, energy consumption, regenerative braking performance, power flow visualization, and EV-specific vehicle diagnostics, supporting the growing demand for connected and intelligent electric mobility solutions.
Estimation Model
Layer Name
Key Question
Description
Global Vehicle Production Layer
Where are automotive instrument clusters used and what drives demand?
Establish the total potential demand base by identifying automotive instrument cluster deployment across passenger cars, two-wheelers, three-wheelers, buses, trucks, and electric vehicles. Demand is fundamentally driven by global vehicle production volumes, vehicle parc growth, rising vehicle ownership, increasing vehicle electrification, and the growing integration of electronic cockpit systems across various vehicle categories.
Addressable Vehicle Electronics Layer
Which vehicles can realistically adopt advanced automotive instrument clusters?
Refine the total vehicle production base into the realistically serviceable market by considering factors such as vehicle segment, consumer purchasing power, OEM technology adoption strategies, vehicle price positioning, digital cockpit penetration, regulatory requirements, connectivity features, and the adoption of advanced driver assistance systems (ADAS). This layer identifies vehicles capable of integrating analog, hybrid, or fully digital instrument cluster solutions.
Instrument Cluster Procurement Layer
Who is actively purchasing, integrating, or upgrading automotive instrument cluster systems?
Estimate annual demand generation by analyzing new vehicle production programs, vehicle model launches, platform upgrades, electric vehicle development initiatives, digital cockpit adoption trends, premiumization strategies, software-defined vehicle deployments, and replacement demand within the aftermarket. This layer captures procurement activities by automotive OEMs, vehicle manufacturers, and system integrators across major vehicle categories and regions.
Revenue Layer
How is revenue generated from automotive instrument cluster sales?
Revenue is generated through the supply of automotive instrument clusters across various types (analog, digital, and hybrid), vehicle categories (scooters, motorcycles, three-wheelers, passenger cars, buses, and trucks), and propulsion systems (ICE and electric). Market revenue is calculated by considering vehicle production volumes, instrument cluster penetration rates, display technology specifications, software and connectivity features, ADAS integration, customization requirements, OEM pricing agreements, and value chain margins across component suppliers, Tier-1 manufacturers, and automotive OEMs.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Automotive Instrument Cluster Market Assessment
Structured evaluation of market dynamics including key drivers, restraints, opportunities, and emerging trends across the automotive instrument cluster value chain.
Assessment of technology evolution across analog, hybrid, and digital instrument clusters, connected vehicle ecosystems, digital cockpit platforms, ADAS integration, and software-defined vehicle architectures.
Clear visibility into market growth drivers, technology adoption trends, and key market challenges.
Strategic input for market entry, product positioning, expansion planning, and investment decision-making.
Vehicle Segment and Application Insights
Analysis of demand distribution across scooters, motorcycles, three-wheelers, passenger cars, buses, and trucks.
Evaluation of evolving OEM requirements related to digital cockpit adoption, EV-specific instrumentation, connectivity features, driver information systems, safety notifications, navigation integration, and user experience enhancement.
Identification of high-growth vehicle categories and emerging application opportunities.
Support for targeted product development, customer prioritization, and go-to-market strategy formulation.
Technology and Competitive Landscape Review
Benchmarking of key automotive instrument cluster technologies including analog, hybrid, and fully digital systems, as well as TFT-LCD, OLED, 3D display, and advanced HMI solutions.
Analysis of major players' innovation strategies, digital cockpit capabilities, software integration expertise, EV-focused product development, OEM partnerships, and regional market presence.
Competitive intelligence for technology differentiation and portfolio optimization.
Guidance for R&D prioritization, partnership assessment, acquisition evaluation, and long-term growth strategy development.
Frequently Asked Questions About This Report
The electric segment is expected to grow at a compound annual growth rate of 10.8% from 2026 to 2033.
The ICE segment dominated the propulsion type segment in 2025 with 60.1% revenue share.
The global automotive instrument cluster market size was estimated at USD 9.1 billion in 2025 and is expected to reach USD 9.78 billion in 2026.
The global automotive instrument cluster market is expected to grow at a compound annual growth rate of 8.9% from 2026 to 2033, reaching USD 17.7 billion by 2033.
Some key players operating in the automotive instrument cluster market include Continental AG, Denso Corporation, JP Minda Group, Nippon Seiki Co., Ltd., Panasonic Corporation, Pricol Limited, Robert Bosch GmbH, Simco Ltd., Valid Manufacturing Ltd., and Visteon Corporation.
The hybrid segment dominated the type segment in 2023. Growing adoption of hybrid instrument clusters owing to their range of benefits, including enhanced customization, better aesthetics, and the ability to display a wide variety of information, can be attributed to segment growth.
The key drivers attributed to the market growth include advancements in digital display technology and the integration of more sophisticated features such as navigation, multimedia, and connectivity options.
The passenger cars segment dominated the vehicle type segment in 2025 with 53.3% revenue share.
The three wheeler segment is expected to grow at a compound annual growth rate of 11.4% from 2026 to 2033.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


