
- Home
- »
- Semiconductors
- »
-
Automotive Printed Circuit Board Market Size, Growth Report, 2026-2033GVR Report cover

Automotive Printed Circuit Board Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Double-Sided PCB, Multi-Layer PCB, Single-Sided PCB), By Vehicle Type, By Level of Autonomy, By Application, By Region, And Segment Forecasts
Market Size, 2025
$10.8BMarket Estimate, 2026
$11.4BMarket Forecast, 2033
$16.8BCAGR, 2026–2033
5.7%Automotive Printed Circuit Board Market Summary
The global automotive printed circuit board market size was valued at USD 10.8 billion in 2025 and is projected to grow from USD 11.4 billion in 2026 to USD 16.8 billion in 2033, at a CAGR of 5.7% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 44.0% in 2025. The automotive Printed Circuit Board (PCB) market is witnessing strong growth, driven by the increasing electronic content in modern vehicles, including ADAS, infotainment systems, powertrain control, and EV battery management systems. Rising adoption of electric and autonomous vehicle is further accelerating demand for high-density, multi-layer, and flexible PCBs.
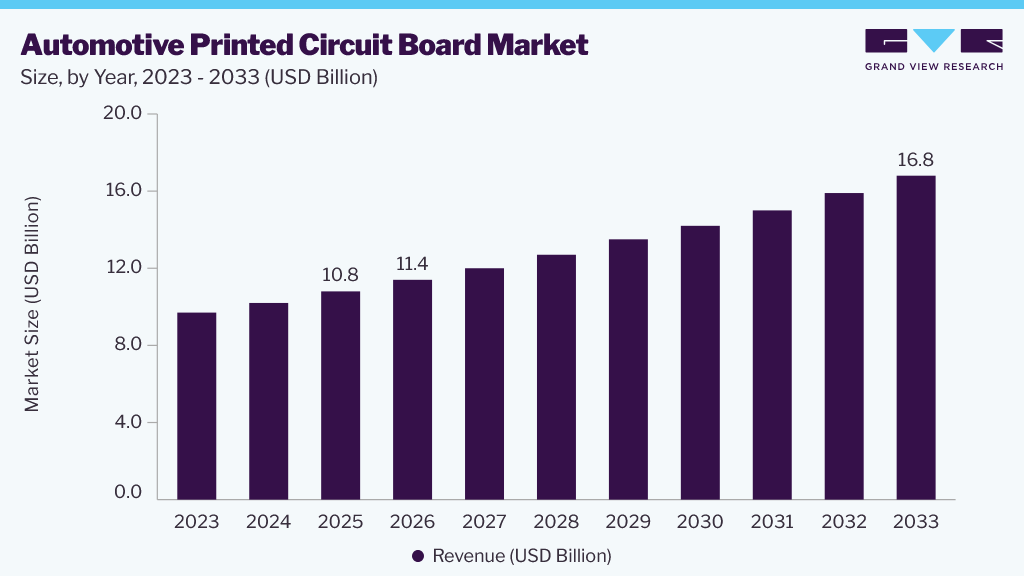 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: The double-sided PCBs segment dominated the market in 2025 and accounted for a revenue share of more than 35.0%.
- By vehicle type: The passenger car segment held the largest market share in 2025.
- By application: The infotainment components segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (44.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 10.8 Billion
- Estimated market size in 2026: USD 11.4 Billion
- Projected market size by 2033: USD 16.8 Billion
- CAGR (2026-2033): 5.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Stringent safety regulations and the shift toward connected mobility are reinforcing the integration of advanced PCB technologies across automotive platforms. As global fuel prices fluctuate and environmental concerns intensify, both manufacturers and consumers are prioritizing drivetrain technologies that offer improved fuel economy without compromising power or reliability. Advanced drivetrains, including all-wheel drive (AWD) and hybrid systems, enhance vehicle performance, traction, and safety, especially under challenging road and weather conditions, thus gaining wider adoption across passenger and commercial vehicle segments.
Several market drivers are fueling this growth. Technological advancements in automotive electronics and printed circuit board (PCB) manufacturing enhance performance and reliability, while stricter safety and emission regulations compel automakers to incorporate advanced electronic systems, boosting PCB demand. Consumer expectations for safety, connectivity, and infotainment further drive market expansion.
However, the market faces restraints such as high initial costs for developing advanced PCBs and complex manufacturing processes that require significant investment in expertise and equipment. In addition, challenges such as supply chain disruptions and economic fluctuations can impact raw material availability and overall market stability.
Despite these challenges, there are substantial opportunities in the automotive PCB market. The rapid growth of the electric vehicle segment presents a significant opportunity, as EVs require more electronic components than traditional vehicles. Emerging markets in the Asia Pacific and Latin America offer further growth prospects due to increasing vehicle production and the adoption of advanced automotive technologies. Sustainability initiatives are also driving the development of eco-friendly and energy-efficient PCBs, opening new avenues for innovation. Furthermore, continuous technological advancements, such as flexible and rigid-flex PCBs, support the increasing complexity and miniaturization of automotive electronic systems, providing additional growth opportunities.
Analyst Perspective
The automotive PCB sector has moved from its traditional role as an element of hardware supply to now playing a strategic role within the industry toward enabling electric vehicle (EV) architectures and software defined mobility. Increased demand for PCBs in vehicles continues to be generated from EV architecture, advanced driver assistance systems (ADAS) & zonal electronic systems. All of which contribute to the need for more PCB content on each vehicle while also driving the need for high-density interconnect (HDI), rigid-flex, and high-temperature PCBs. Supply chain localization and diversification are emerging as key strategies to reduce OEMs' reliance upon single-sourced suppliers. In addition, the trends of sustainability and miniaturization are driving design priorities; thus, PCB manufacturers have to look for greener substrates (non-toxic components) and provide integrated solutions in order to stay competitive. As a whole, this marketplace should remain structurally growth-focused, but becoming competitively differentiated will depend on technology capability, reliability engineering, and close alignment with EV Platforms and autonomous vehicle platforms.
Type Insights
The double-sided PCBs segment dominated the market in 2025 and accounted for a revenue share of more than 35.0%. Double-sided PCBs dominate the automotive PCB market due to their versatility and efficiency in providing intermediate-level complexity at a lower cost than multi-layer PCBs. These PCBs are widely used in various automotive levels of autonomy, including lighting systems, power supplies, and instrumentation, due to their ability to support surface mount technology (SMT) and through-hole components on both sides. The market dominance of double-sided PCBs can be attributed to their balance between performance and cost, making them ideal for mid-range levels of autonomy.
As automotive technology evolves, the demand for more electronic content in vehicles continues to rise. This trend supports the growth of double-sided PCBs, which offer enhanced functionality compared to single-sided PCBs without the higher costs associated with multi-layer PCBs. Their widespread use in electronic control units (ECUs), engine control systems, and transmission control systems underscores their critical role in modern vehicles. The growing focus on electric vehicles (EVs) and advanced driver-assistance systems (ADAS) is boosting the need for reliable and cost-effective PCB solutions, further strengthening the market position of double-sided PCBs.
The multi-layer PCB segment is projected to witness significant growth from 2026 to 2033. The multi-layer PCB segment is the fastest-growing in the automotive PCB market, driven by the increasing complexity and functionality required in modern vehicles. These PCBs consist of three or more conductive layers, offering high circuit density and enhanced performance. The growth of multi-layer PCBs is fueled by the rapid adoption of advanced automotive technologies, including ADAS, infotainment systems, and electric vehicle powertrains. As vehicles become more sophisticated, the need for PCBs that can handle higher frequencies and greater electrical performance becomes paramount. Multi-layer PCBs are ideal for these levels of autonomy due to their ability to support complex circuitry and higher component densities. The trend toward autonomous driving and the integration of more electronic features in vehicles also contribute to the rising demand for multi-layer PCBs. Moreover, the shift toward electric and hybrid vehicles, which require more robust and reliable electronic systems, further accelerates the growth of this segment. Multi-layer PCBs are essential for critical levels of autonomy, such as battery management systems, inverters, and motor controllers, making them indispensable in the automotive industry's push toward electrification and advanced driver assistance.
Vehicle Type Insights
The passenger car segment dominated the market in 2025. The passenger car segment dominates the automotive PCB market, primarily due to the high volume of production and the increasing incorporation of advanced electronic systems in these vehicles. Passenger cars are equipped with a wide array of electronic components, including infotainment systems, navigation systems, advanced safety features, and comfort-related electronics, all of which require sophisticated PCBs.
The rising consumer demand for enhanced driving experiences, connectivity, and safety features drives the need for more PCBs in passenger cars. In addition, the trend toward electric and hybrid passenger cars further boosts the demand for automotive PCBs, as these vehicles rely heavily on electronic systems for battery management, powertrain control, and energy efficiency.
The dominance of passenger cars in the PCB market is also supported by the continuous advancements in automotive technology, such as ADAS and autonomous driving capabilities, which are more commonly integrated into passenger cars before commercial vehicles. As a result, the passenger car segment remains the largest consumer of automotive PCBs, reflecting the broader trends of increasing electronic content and technological innovation in the automotive industry.
The commercial vehicle is the fastest-growing segment in the automotive printed circuit board (PCB) market, driven by the increasing adoption of advanced electronic systems in trucks, buses, and other commercial vehicles. These vehicles are incorporating more sophisticated electronics to enhance safety, efficiency, and connectivity. Key Level of Autonomy includes telematics, fleet management systems, advanced braking systems, and powertrain control modules. The rise of electric and hybrid commercial vehicles is also a significant factor contributing to the growth of this segment. Electric buses and trucks require robust electronic systems for battery management, motor control, and charging infrastructure, driving the demand for high-performance PCBs.
Furthermore, the logistics and transportation industry's shift toward smart and connected vehicle solutions is accelerating the integration of advanced electronics in commercial vehicles. This trend is supported by regulatory requirements for enhanced safety and emissions standards, which necessitate more complex and reliable electronic systems. As a result, the commercial vehicle segment is experiencing rapid growth in the automotive PCB market, reflecting the broader move toward smarter, safer, and more efficient transportation solutions.
Level of Autonomy Insights
The conventional vehicles segment dominated the market in 2025, primarily due to their widespread presence and the gradual transition to more advanced vehicle technologies. Despite the growing interest in electric and autonomous vehicles, conventional vehicles still represent the majority of the global automotive fleet. These vehicles rely on a variety of electronic systems for engine control, transmission, infotainment, and safety features, all of which require PCBs.
The dominance of conventional vehicles is supported by the ongoing demand for gasoline and diesel-powered vehicles, especially in regions with less developed infrastructure for electric vehicles. In addition, the incremental improvements in fuel efficiency and emissions control in conventional vehicles continue to drive the integration of advanced electronic systems, sustaining the demand for automotive PCBs.
The market for PCBs in conventional vehicles is also bolstered by the retrofitting and upgrading of existing vehicles with modern electronics, further enhancing their performance and safety. As a result, conventional vehicles remain the dominant segment in the automotive PCB market, reflecting the broader trends of technological enhancement and sustained demand for traditional vehicle types.
The autonomous vehicles segment is experiencing significant growth in the automotive printed circuit board (PCB) market. The autonomous vehicles segment is the fastest-growing in the automotive PCB market, driven by the rapid advancements in self-driving technology and the increasing investments in autonomous vehicle development. Autonomous vehicles rely heavily on complex electronic systems to operate safely and efficiently, including sensors, cameras, LiDAR, radar, and artificial intelligence (AI) processors, all of which require advanced PCBs. The high demand for multi-layer and flexible PCBs in these vehicles is due to their ability to support the intricate and high-density circuitry needed for autonomous driving. The growth of this segment is fueled by the push from major automotive manufacturers and technology companies toward achieving fully autonomous driving capabilities.
In addition, the regulatory environment is gradually evolving to support the deployment of autonomous vehicles, further accelerating the adoption of advanced PCBs. The integration of vehicle-to-everything (V2X) communication technologies, which enable autonomous vehicles to interact with their surroundings, also drives the need for sophisticated PCBs. As the development and testing of autonomous vehicles progress, the demand for high-performance and reliable PCBs continues to rise, making this segment the fastest-growing in the automotive PCB market.
Application Insights
The infotainment components segment dominated the market in 2025 due to the growing consumer demand for connectivity, entertainment, and information systems in vehicles. Modern vehicles are equipped with advanced infotainment systems that include navigation, multimedia, internet connectivity, and smartphone integration, all of which require sophisticated PCBs.
The dominance of this segment is driven by the increasing incorporation of high-tech features in vehicles, particularly in mid-range and luxury segments. Infotainment systems enhance the driving experience by providing seamless connectivity and access to a wide range of digital content, making them a key differentiator in the competitive automotive market. The continuous advancements in display technologies, user interfaces, and connectivity options, such as 5G, further boost the demand for complex and high-density PCBs in infotainment applications. In addition, the trend toward integrating infotainment systems with other in-car technologies, such as ADAS and telematics, amplifies the need for robust and reliable PCBs.
The ADAS and basic safety segment is experiencing significant growth in the automotive printed circuit board (PCB) market, driven by the increasing focus on vehicle safety and the integration of advanced driver-assistance systems. ADAS includes features such as automatic emergency braking, collision avoidance, adaptive cruise control, and lane departure warning, which rely on a network of sensors, cameras, and radar systems, all requiring sophisticated PCBs.
The rapid growth of this segment is fueled by regulatory mandates and consumer demand for enhanced vehicle safety. Governments worldwide are implementing stricter safety standards, pushing automotive manufacturers to incorporate ADAS features in their vehicles, thereby increasing the demand for automotive PCBs. In addition, the rising incidence of road accidents has heightened the awareness and adoption of these safety systems, further driving market growth. The advancements in sensor technology and the development of AI and machine learning algorithms for real-time data processing also contribute to the increased demand for high-performance PCBs in ADAS applications. As the automotive industry moves toward higher levels of vehicle automation, the ADAS and basic safety segment is expected to continue its rapid growth, significantly impacting the automotive PCB market.
Regional Insights
The automotive printed circuit board (PCB) market in North America is characterized by a strong emphasis on technological innovation and the rapid adoption of advanced automotive electronics. The region's robust automotive industry, particularly in the United States and Canada, drives significant demand for PCBs used in various applications, including advanced driver-assistance systems (ADAS), infotainment systems, and powertrain control modules.
The presence of major automotive manufacturers and technology companies, coupled with a strong focus on research and development, fosters the growth of the PCB market. The push toward electric and autonomous vehicles further accelerates this demand, as these vehicles require more sophisticated and high-density PCBs. Regulatory initiatives aimed at improving vehicle safety and emissions standards also contribute to market growth by driving the adoption of advanced electronic systems in vehicles.
In addition, the region's well-established infrastructure for electric vehicles, including extensive charging networks, supports the increasing integration of PCBs in electric and hybrid vehicles. The North American automotive PCB market is expected to continue its growth trajectory, supported by ongoing advancements in automotive technology and the region's commitment to enhancing vehicle safety and connectivity.
U.S. Automotive Printed Circuit Board Market Trends
The automotive printed circuit board (PCB) market in the U.S. plays a pivotal role in the North American automotive PCB market, driven by the country's strong automotive industry and technological advancements. The U.S. is home to major automotive manufacturers and a thriving ecosystem of technology companies that are at the forefront of developing advanced automotive electronics.
The demand for PCBs in the U.S. is propelled by the rapid adoption of electric and autonomous vehicles, as well as the integration of advanced driver-assistance systems (ADAS) and infotainment systems in vehicles. Regulatory mandates aimed at enhancing vehicle safety and reducing emissions also drive the market by encouraging the adoption of more sophisticated electronic systems.
The U.S. market is characterized by significant investments in research and development, leading to continuous innovations in PCB technology and applications. The growing consumer demand for connected and intelligent vehicles further supports the market growth, as these vehicles require complex and high-density PCBs. The U.S. automotive PCB market is expected to continue its robust growth, driven by ongoing advancements in automotive technology and the country's commitment to leading the future of mobility.
Asia Pacific Automotive Printed Circuit Board Market Trends
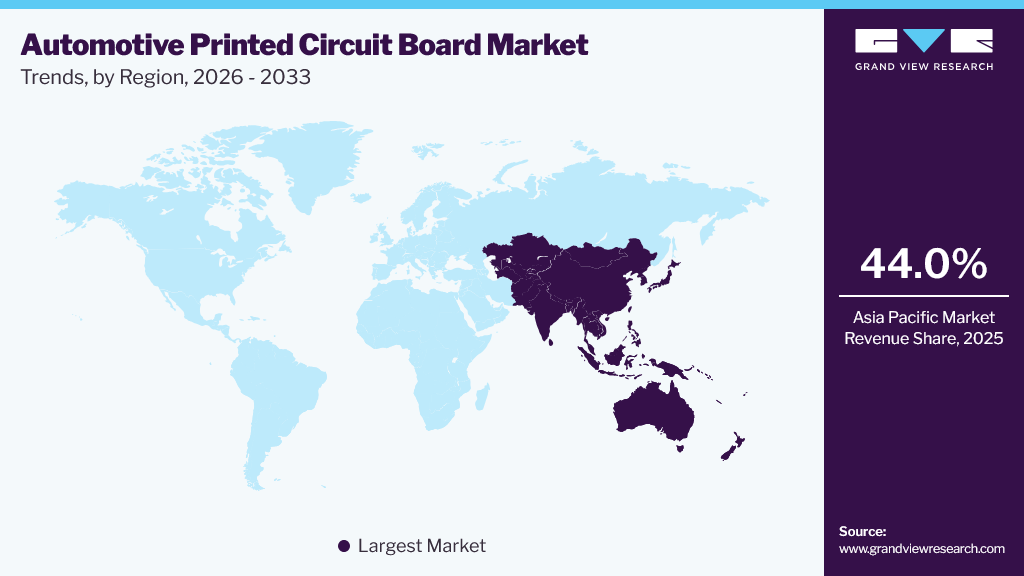
The Asia Pacific dominated the market, accounting for a revenue share of 44.0% in 2025. The region is also expected to record the fastest CAGR over the forecast period. It is expected to witness expansion, primarily driven by the high production volume of vehicles and the rapid adoption of advanced automotive technologies. China, Japan, and South Korea are key markets within the region, with China being the largest automotive market globally. The region's strong manufacturing base, coupled with significant investments in electric vehicle (EV) technology, drives the demand for PCBs.
 To learn more about this report, Download Free Sample Report
Governments in the Asia Pacific region are actively promoting electric mobility through subsidies and favorable policies, further boosting the market. The rapid urbanization and increasing consumer demand for advanced safety and infotainment features in vehicles also contribute to the market growth. In addition, the presence of major PCB manufacturers and suppliers in the region enhances supply chain efficiency and supports the production of high-quality PCBs.
The Asia Pacific automotive PCB market benefits from the region's focus on technological advancements and the growing trend toward smart and connected vehicles. As the automotive industry continues to evolve, the Asia Pacific region is expected to maintain its leading position in the global automotive PCB market.
Europe Automotive Printed Circuit Board Market Trends
The automotive printed circuit board market in Europe is marked by the region's strong automotive heritage and commitment to innovation in vehicle electronics. Germany, France, and the United Kingdom are key contributors to the market, with Germany being a major hub for automotive manufacturing and technology development.
The region's stringent environmental regulations and focus on reducing carbon emissions drive the adoption of electric and hybrid vehicles, which in turn boosts the demand for advanced PCBs. European automakers are at the forefront of integrating advanced driver-assistance systems (ADAS) and autonomous driving technologies, further increasing the need for high-performance PCBs.
The market is also influenced by the growing demand for enhanced in-car connectivity and infotainment systems, reflecting consumers' preferences for more connected and intelligent vehicles. Europe's strong focus on safety and innovation, coupled with significant investments in research and development, positions the region as a critical market for automotive PCBs. The ongoing shift toward electric mobility and the development of smart transportation infrastructure are expected to sustain the growth of the automotive PCB market in Europe.
Key Automotive Printed Circuit Board Company Insights
The companies are focusing on various strategic initiatives, including new product development, partnerships & collaborations, and agreements to gain a competitive advantage over their rivals. The following are some instances of such initiatives.
Key Automotive Printed Circuit Board Companies
The following key companies have been profiled for this study on the automotive printed circuit board market:
-
Chin Poon Industrial
-
Meiko Electronics
-
Nippon Mektron
-
TTM Technologies
-
KCE Electronics
-
Tripod Technology
-
Unimicron Technology
-
Kingboard Chem GRP
-
Amitron Corp.
-
CMK Corp
Recent Developments
-
In October 2025, Concord Control Systems Limited acquired a 50% stake in Fusion Electronics Private Limited, a leading Indian manufacturer of flex printed circuit boards (PCBs), marking its entry into the high-value automotive and industrial electronics PCB segment. The deal enables Concord to leverage Fusion Electronics’ established manufacturing capabilities and customer base in automotive OEM supply chains, including global automakers, while strengthening its position in the electronic manufacturing services (EMS) space focused on advanced flex PCB production.
-
In October 2024, Ventec International Group announced a major upgrade of its European PCB production and logistics facility in Kirchheimbolanden, Germany. The company began consolidating and modernizing its operations into a single advanced production hub to improve manufacturing efficiency and customer responsiveness.
-
In May 2024, Chin-Poon Industrial, known for its significant focus on automotive PCB production, announced plans to invest an additional approximately USD 27.3 million to expand its factory site in Thailand.
Automotive Printed Circuit Board Market Report Scope
Report Attribute
Details
Market size in 2025
USD 10.8 billion
Estimated market size in 2026
USD 11.4 billion
Projected market size by 2033
USD 16.8 billion
Growth rate
CAGR of 5.7% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, vehicle type, level of autonomy, application, region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia & New Zealand; South Korea; Brazil; Argentina; South Africa; UAE
Key companies profiled
Chin Poon Industrial; Meiko Electronics; Nippon Mektron; TTM Technologies; KCE Electronics; Tripod Technology; Unimicron Technology; Kingboard Chem GRP; Amitron Corp; CMK Corp.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Printed Circuit Board Market Report Segmentation
The report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the automotive printed circuit board market based on type, vehicle type, level of autonomy, application, and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Double-Sided PCB
-
Multi-Layer PCB
-
Single-Sided PCB
-
-
Vehicle Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Passenger Car
-
Commercial Vehicle
-
-
Level of Autonomy Outlook (Revenue, USD Million, 2021 - 2033)
-
Autonomous Vehicles
-
Conventional Vehicles
-
Semi-Autonomous Vehicles
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
ADAS and Basic Safety
-
Body, Comfort, and Vehicle Lighting
-
Infotainment Components
-
Powertrain Components
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Kingdom of Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
The global Automotive Printed Circuit Board market size was valued at USD 10.8 billion in 2025 and is estimated at USD 11.4 billion for 2026.
The global Automotive Printed Circuit Board market is expected to grow at a CAGR of 5.7% from 2026 to 2033, reaching USD 16.8 billion
Asia Pacific dominated with a 44.0% revenue share in 2023.
Key players in the market include Chin Poon Industrial; Meiko Electronics; Nippon Mektron; TTM Technologies; KCE Electronics; Tripod Technology; Unimicron Technology; Kingboard Chem GRP; Amitron Corp; CMK Corp., and others.
The double-sided PCBs segment dominated the market in 2025 and accounted for a revenue share of more than 35.0%.
About the Author(s)
Semiconductors Research Team
Semiconductors & Electronics · SemiconductorsThis report was authored by the semiconductors research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the semiconductors segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


