
- Home
- »
- Advanced Interior Materials
- »
-
Ferroalloys Market Size, Share & Growth Report, 2026-2033GVR Report cover

Ferroalloys Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Ferrochrome, Ferromanganese, Ferro Silico Manganese, Ferro Silicon), By Application (Carbon & Low Alloy Steel, Stainless Steel, Alloy Steel, Cast Iron), By Region, And Segment Forecasts
Market Size, 2025
$57.1BMarket Estimate, 2026
$61.0BMarket Forecast, 2033
$102.3BCAGR, 2026–2033
7.7%Ferroalloys Market Summary
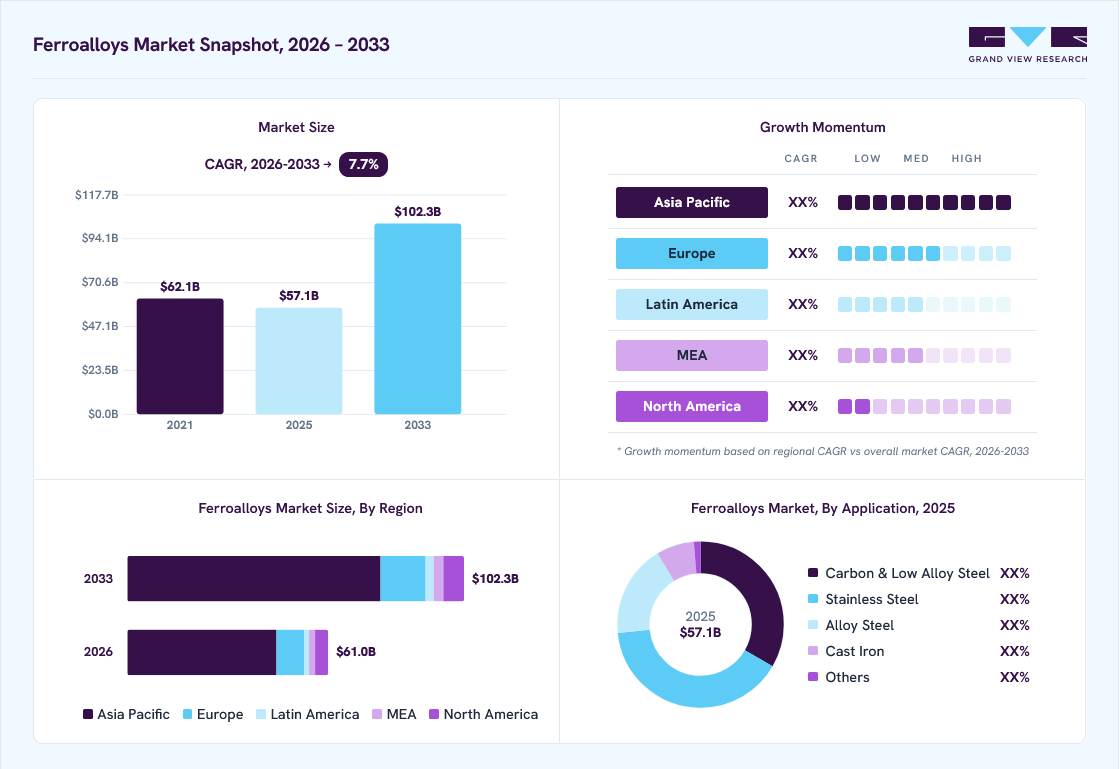
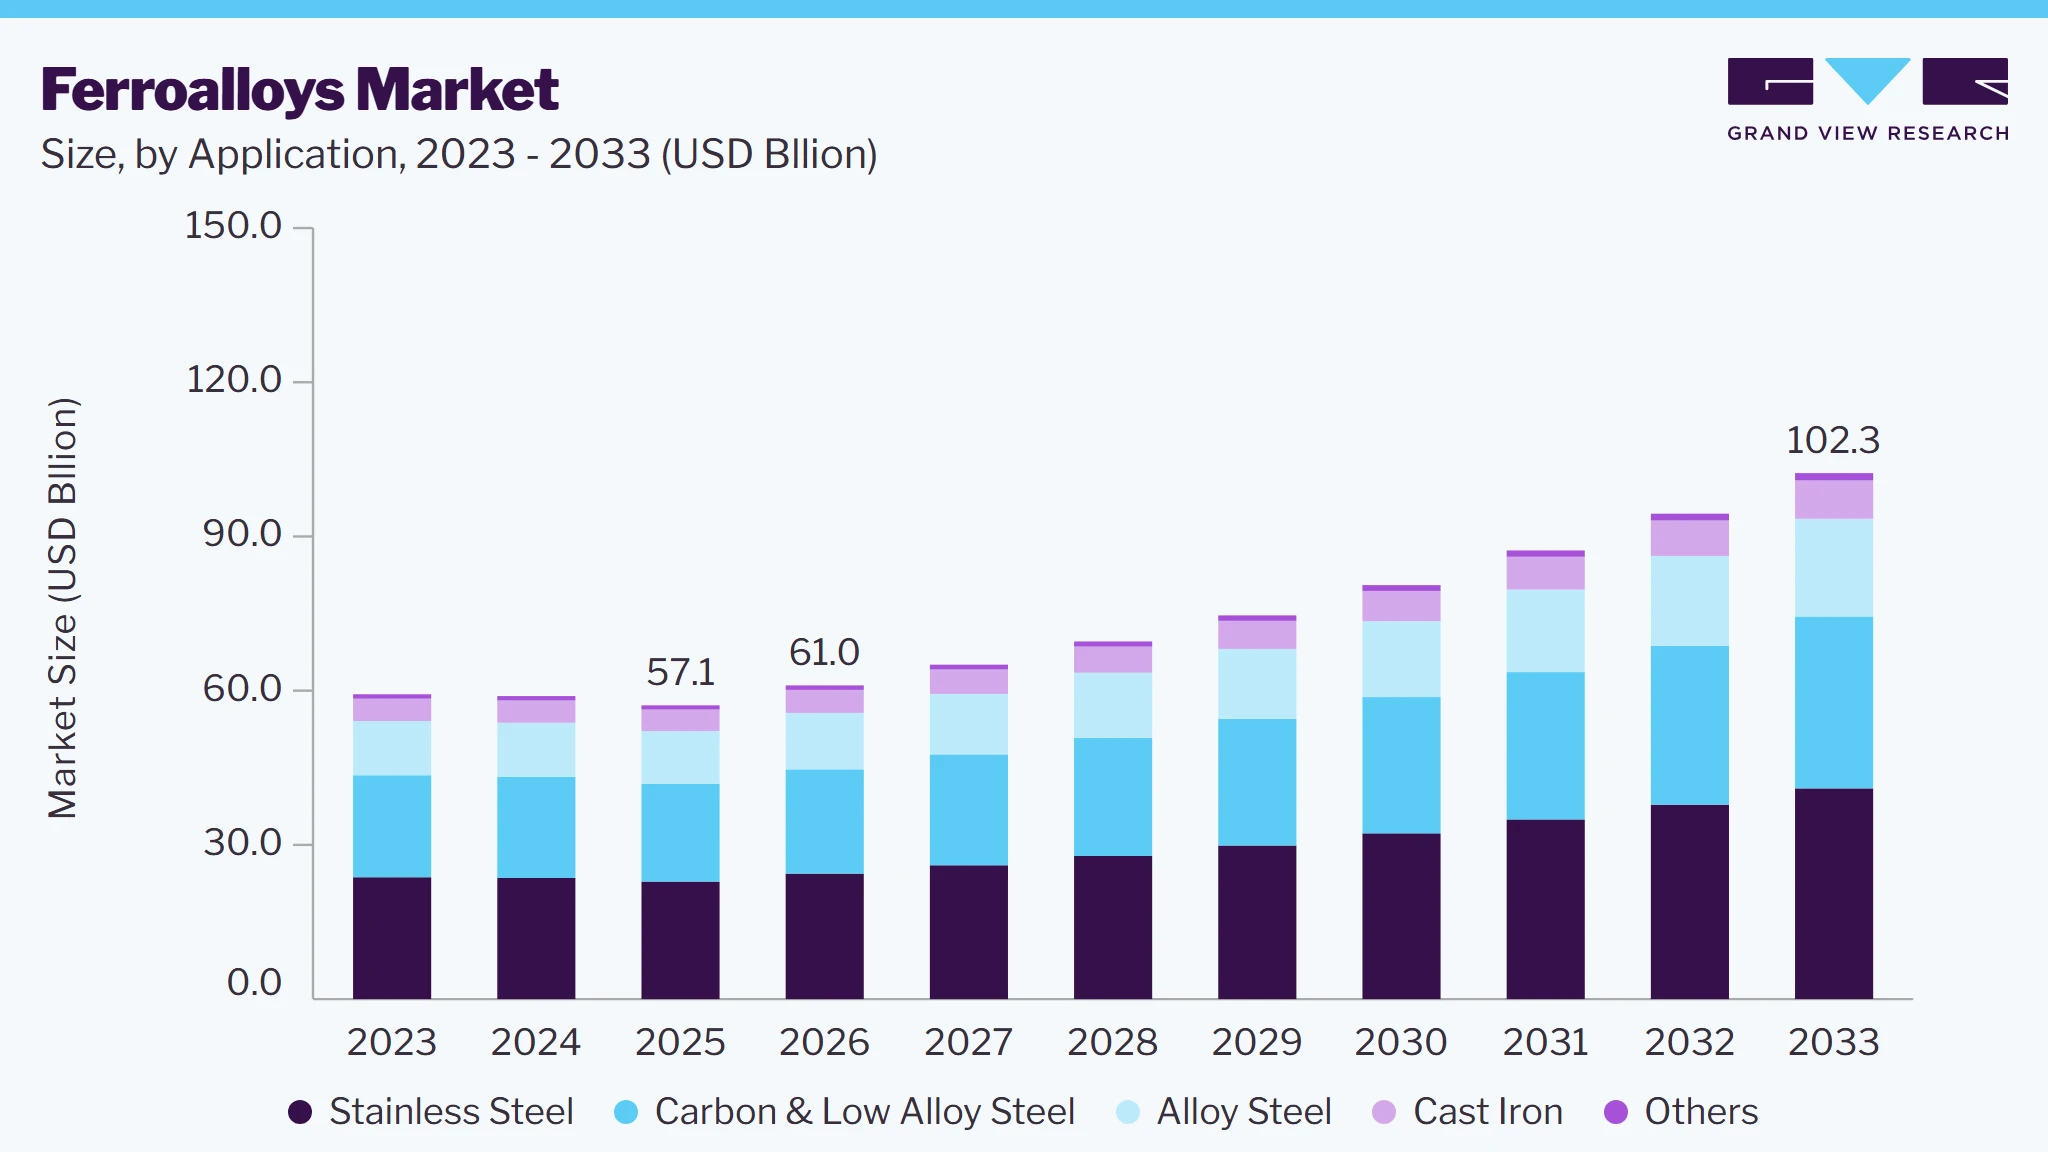
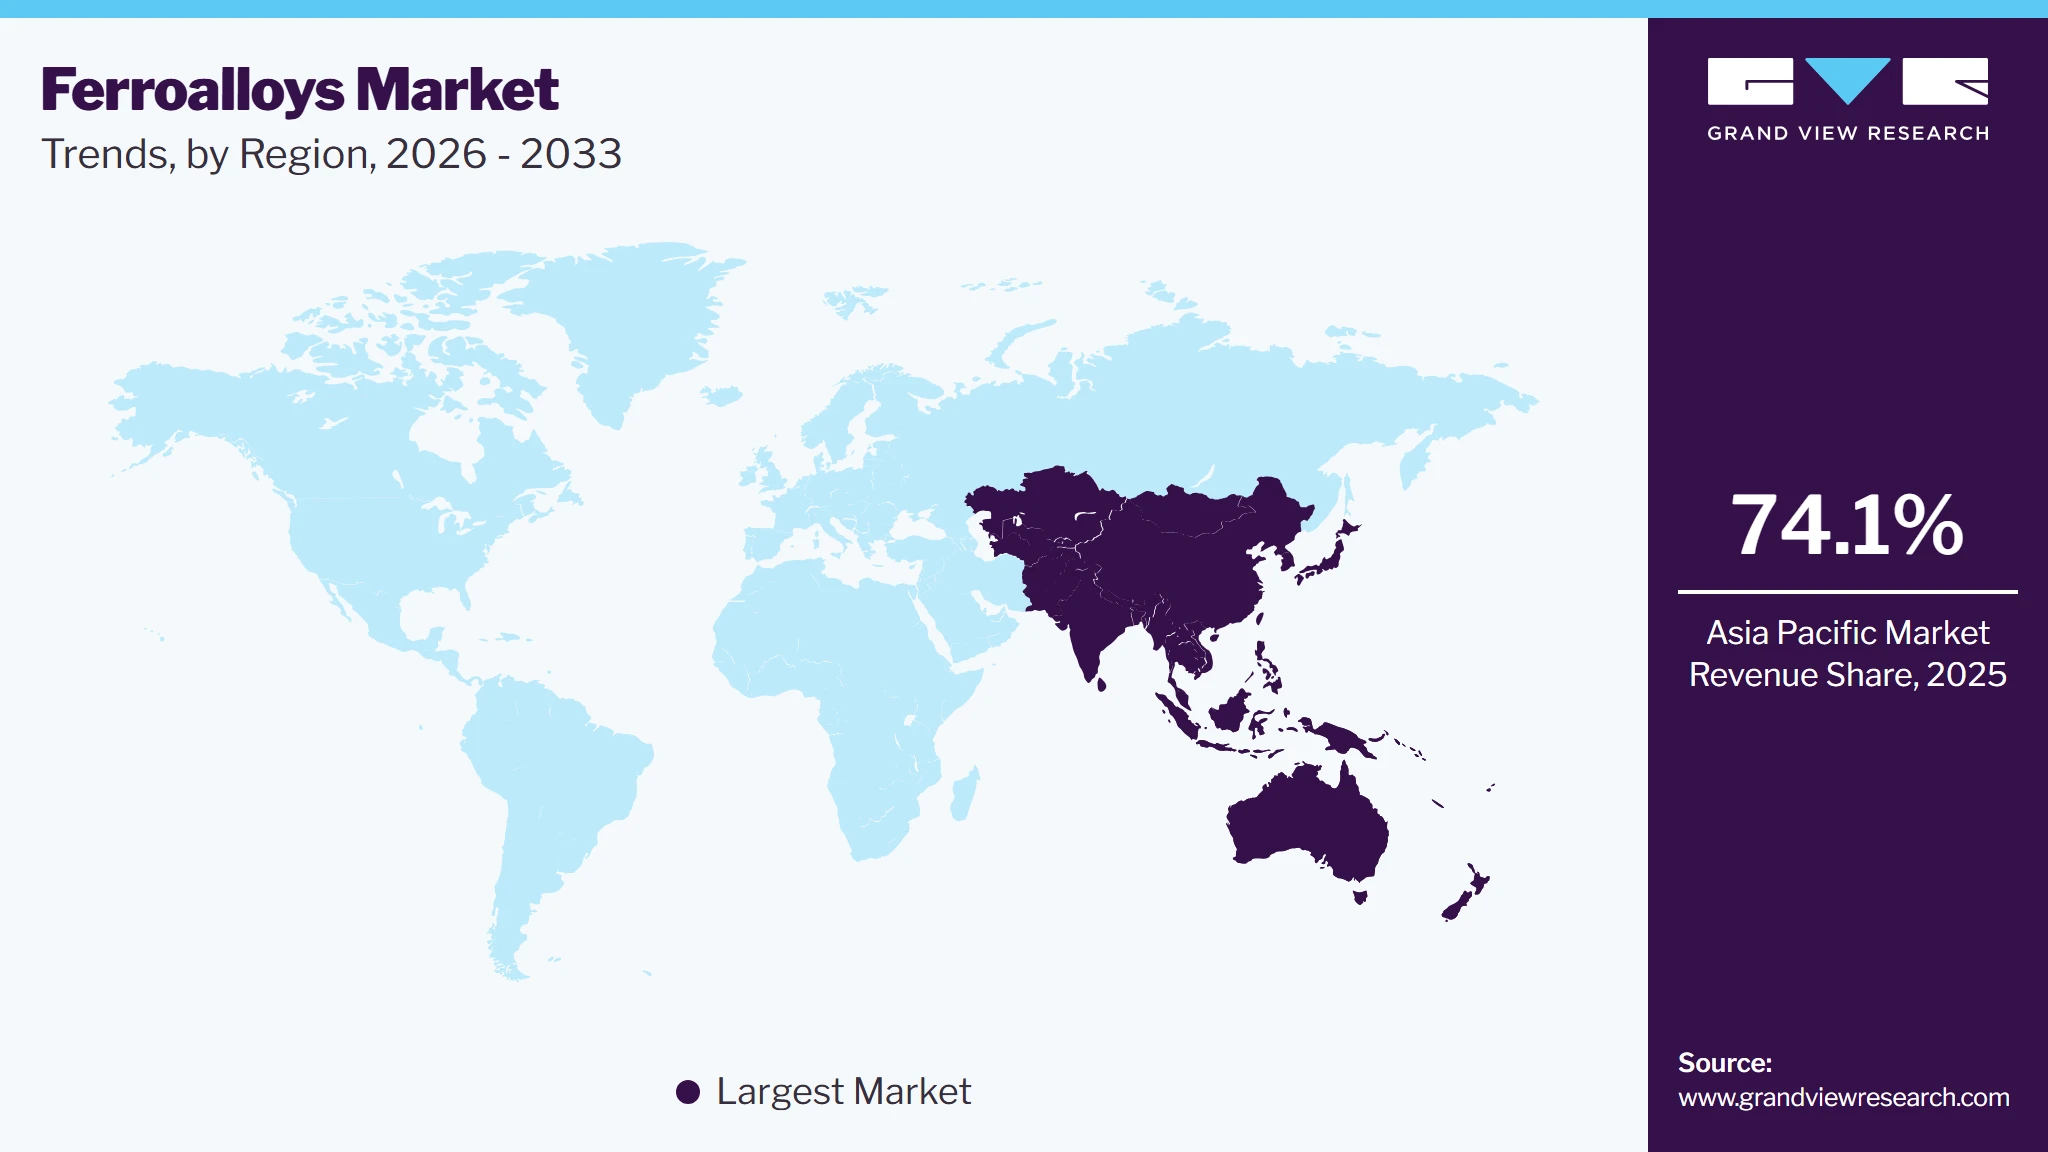
The global ferroalloys market size was valued at USD 57.1 billion in 2025 and is projected to grow from USD 61.0 billion in 2026 to USD 102.3 billion by 2033, at a CAGR of 7.7% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 74.1% in 2025. The market growth is driven by the demand for ferroalloys for use in global steel production.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
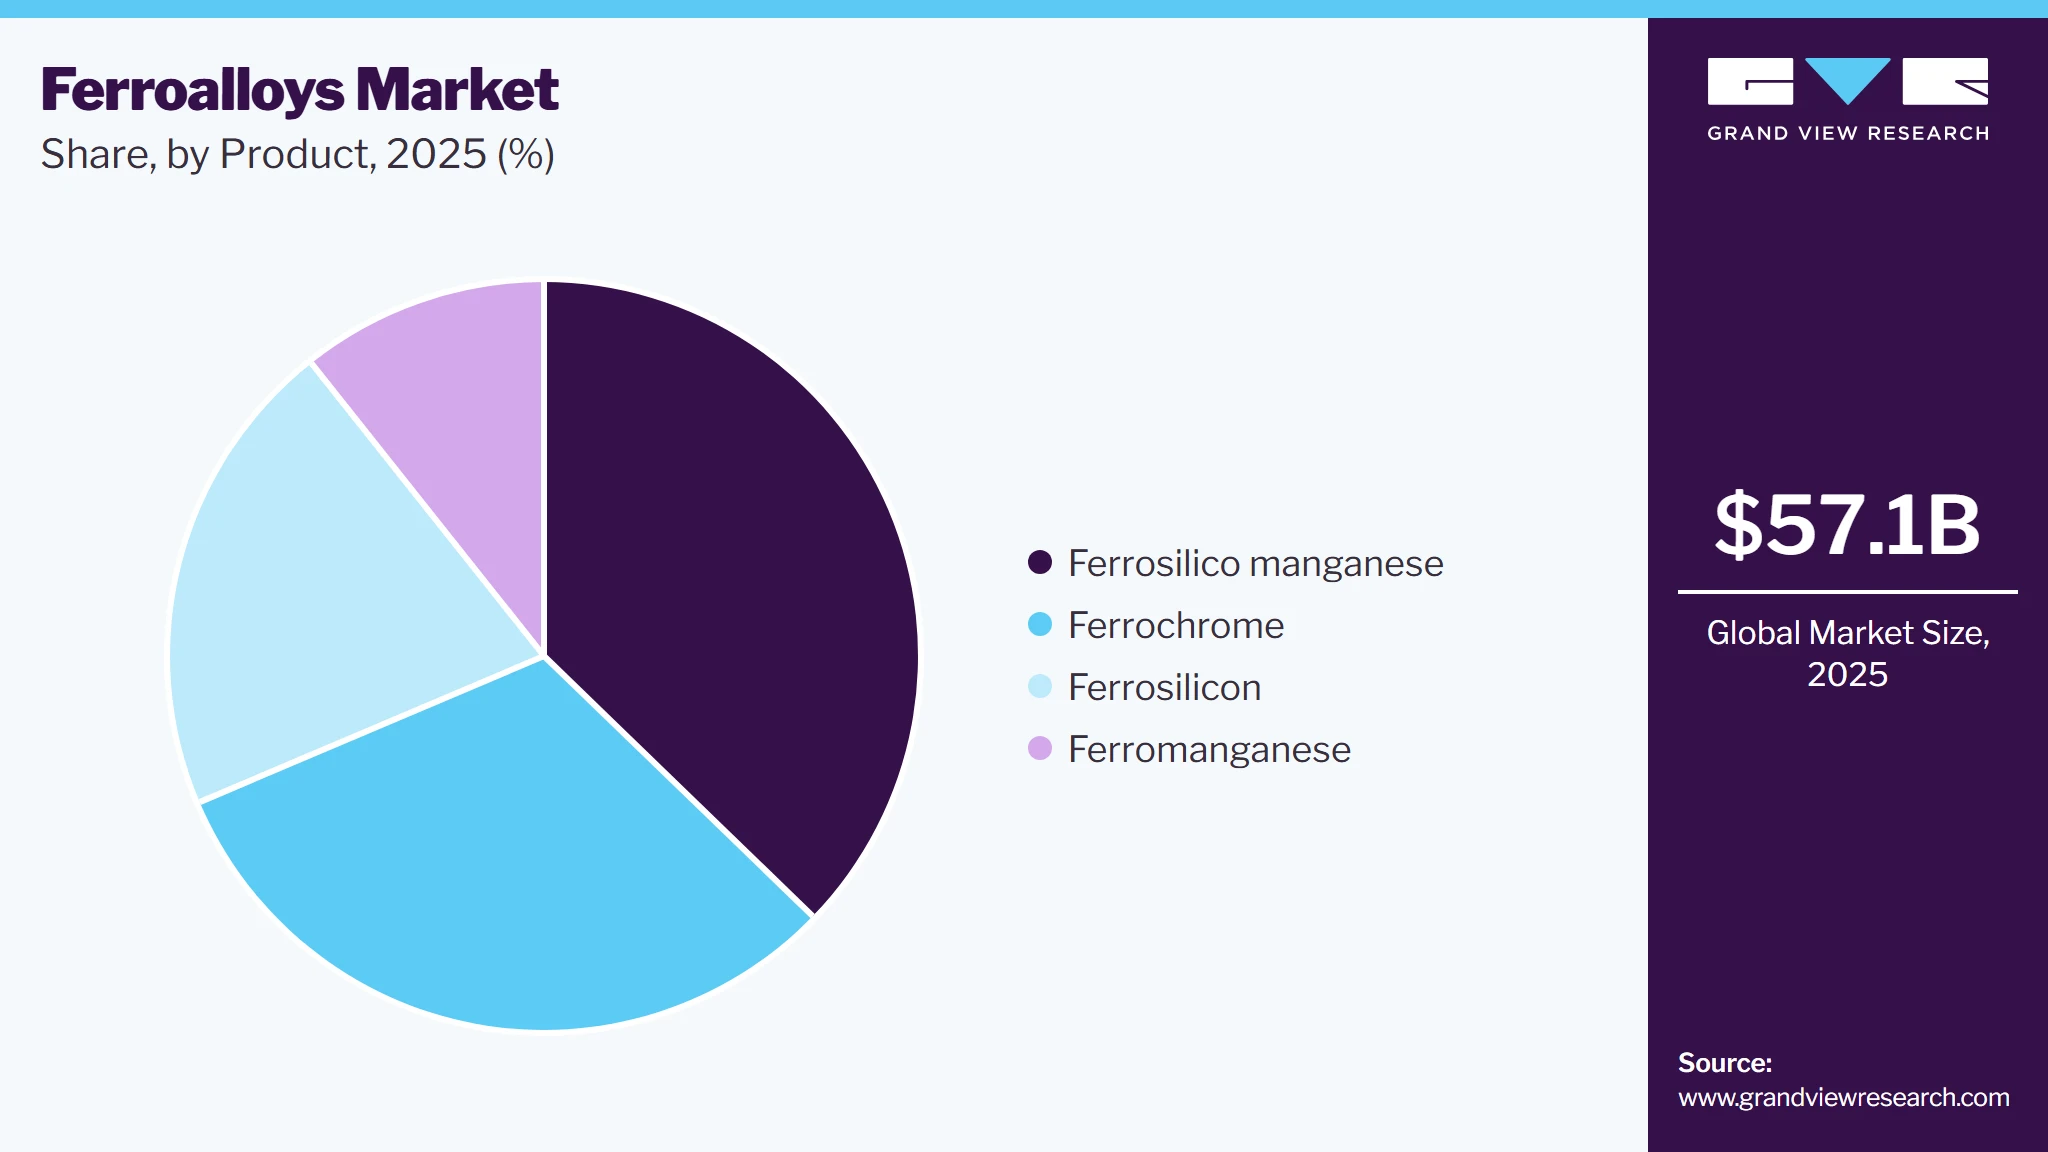
- By product: Ferrosilico manganese segment held the largest market share of 37.2% in 2025.
- By application: Stainless steel segment held the largest market share of 40.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (74.1% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 57.1 Billion
- Estimated market size in 2026: USD 61.0 Billion
- Projected market size by 2033: USD 102.3 Billion
- CAGR (2026-2033): 7.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
The manufacturing of steel is anticipated to be driven by the rising consumption of construction steel worldwide. Hence, the increasing requirement for non-residential and commercial construction, as well as the development of affordable housing units in emerging economies, is anticipated to drive ferroalloys consumption. To learn more about this report, Download Free Sample Report
Market Dynamics
The growth in ferroalloys production is driven by rising demand for ferrochrome, which provides chromium for corrosion and oxidation resistance in stainless steel production. Rising stainless steel output across Asia, led by China and supported by expanding production in other regional markets, is increasing demand for ferrochrome and boosting consumption of ferromanganese and ferrosilicon for alloying and deoxidation.
Capacity expansions in India, Indonesia, and other emerging Asian markets are expected to further support ferroalloy demand as stainless steel consumption increases across construction, automotive, appliances, chemical processing, and energy infrastructure. In addition, the growing production of higher-grade and specialty stainless steels for aerospace, medical, power generation, and advanced manufacturing applications requires specific alloying compositions, supporting demand for ferrochrome and other specialized ferroalloys.
High and volatile industrial electricity costs are a key restraint for the ferroalloys industry because ferrochrome, ferrosilicon, ferromanganese, and silicomanganese production relies on energy-intensive submerged arc furnaces. Changes in power tariffs directly affect production costs and producers' margins, while regions with reliable, relatively low-cost electricity can maintain a competitive advantage. Energy price volatility can also lead producers to reduce operating rates or suspend furnace operations when production economics become unfavorable.
The impact of electricity costs is particularly significant because ferroalloy prices are influenced by steel demand and global supply conditions, limiting producers’ ability to fully pass higher costs to customers. The energy price surge across several markets during 2021-2023 increased cost pressures on energy-intensive smelting operations, particularly in Europe. Consequently, access to stable and competitively priced electricity, along with captive power generation and long-term supply arrangements, remains important for maintaining profitability, supporting capacity utilization, and influencing the location of new ferroalloy production.
The transition toward lower-carbon steelmaking is creating opportunities for ferroalloy producers to reduce the emissions intensity associated with ferrochrome, ferromanganese, ferrosilicon, and silicomanganese production. As ferroalloy manufacturing is highly energy-intensive, producers are increasingly exploring renewable electricity, energy-efficient furnaces, waste-heat recovery, improved furnace controls, and other process optimization measures. Access to low-carbon and competitively priced electricity can also improve the environmental profile and cost competitiveness of ferroalloy production.
Growing demand from steelmakers for lower-carbon raw materials is expected to further support investment in cleaner ferroalloy production technologies. Producers can strengthen their position by integrating renewable power, improving energy efficiency, increasing the use of recycled inputs where technically feasible, and developing traceable low-emission ferroalloys. These developments can create opportunities to supply steel producers facing tighter emissions requirements and increasing pressure to reduce the carbon footprint of their supply chains.
Analyst Perspective
The global ferroalloys market is driven by steel and cast iron production, with demand closely linked to the production of carbon and low-alloy steel, stainless steel, alloy steel, and other metal products. Ferroalloys are essential for achieving the required chemical compositions, strength, hardness, corrosion resistance, and other metallurgical properties, supporting consistent demand across steelmaking and foundry operations. Growing steel production, expansion of stainless steel and specialty alloy capacity, and rising demand for higher-performance grades are supporting ferroalloy consumption, while energy costs, raw material availability, decarbonization initiatives, and the development of lower-emission production technologies are increasingly influencing market dynamics.
Product Insights
The ferrosilico manganese segment dominated the market with the largest revenue share of 37.2% in 2025. Ferrosilico manganese is an alloy of iron and manganese that contains a high amount of manganese and low levels of silicon. It is used as an alloying and deoxidizing agent in the production of steel, stainless steel, and manganese-rich steel. The global consumption of ferro-silico-manganese is anticipated to be driven by steel demand from the electric vehicle (EV) and aerospace industries. It imparts properties such as lightweight, high strength, and corrosion resistance to steel, which are desirable in the EV and aerospace industries and are preferred over other steel alloys.
 To learn more about this report, Download Free Sample Report
The ferrochrome segment is anticipated to grow at the fastest CAGR of 7.9% over the forecast period. Growth is supported by rising stainless steel production, in which ferrochrome is a key source of chromium, which enhances corrosion and oxidation resistance. Expanding stainless steel capacity across Asia, particularly in emerging markets, is expected to sustain ferrochrome consumption. Increasing demand for specialty and higher-performance stainless steel grades in automotive, construction, energy, and industrial applications is also expected to support segment growth.
Application Insights
The stainless steel segment led the market with the largest revenue share of 40.0% in 2025. Its leading position is attributed to the extensive use of ferroalloys in stainless steel production for alloying and deoxidation. Rising demand for corrosion-resistant and durable materials across construction, automotive, energy, chemical processing, and industrial applications is expected to sustain ferroalloy consumption in stainless steel manufacturing.
The alloy steel segment is anticipated to grow at the fastest CAGR of 8.1% over the forecast period. This is due to the increasing use of alloy steel in various sectors, where enhanced strength, toughness, wear resistance, and durability are required. Growing demand for high-performance steel components and infrastructure development is further supporting alloy steel consumption. The increasing production of specialized alloy grades is also expected to drive demand for ferroalloys used to achieve specific material properties.
Regional Insights
The ferroalloys market in North America is primarily supported by steelmaking, particularly carbon steel, stainless steel, and specialty steel production, with ferromanganese and ferrochrome remaining important inputs for alloying, deoxidation, and quality control. Demand is also linked to construction, automotive, machinery, energy, and infrastructure activity. The region remains structurally dependent on imports for several ferroalloy grades and associated critical mineral inputs, while domestic production meets only a smaller share of its requirements. In the U.S., manganese ferroalloys are particularly important because steelmaking accounts for approximately 85-90% of domestic manganese demand.
U.S. Ferroalloys Market Trends
The ferroalloys market in the U.S. has a demand base closely tied to domestic steel production, with silicon and chromium ferroalloys supporting carbon, stainless, and specialty steel manufacturing. USGS data indicate that ferrosilicon-containing steel is a major end-use segment for silicon ferroalloys, while chromium ferroalloys are strongly linked to stainless and alloy steel production. Domestic ferroalloy production remains relatively limited compared with historical levels, making imports important for maintaining supply, particularly for manganese, chromium, and silicon ferroalloys. Consequently, demand is expected to remain closely correlated with steel production, infrastructure investment, and specialty-steel requirements.
Asia Pacific Ferroalloys Market Trends
The Asia Pacific ferroalloys market held the largest revenue share of 74.1% in 2025 and is anticipated to grow at the fastest CAGR during the forecast period, supported by strong steel production capacity in China and India, as well as sustained demand from the infrastructure, construction, automotive, and shipbuilding industries. The region has an integrated ferroalloys value chain spanning mineral extraction, smelting, and downstream steel manufacturing, with major producers and consumers concentrated across China, India, Japan, South Korea, and Southeast Asia. Rapid urbanization and government-led infrastructure development continue to support demand, while environmental regulations, Chinese overcapacity, and evolving trade flows are reshaping regional competition.
 To learn more about this report, Download Free Sample Report
The ferroalloys market in China accounted for the largest revenue share in the Asia-Pacific region in 2025. China is the world’s largest producer and consumer of ferroalloys, supported by its dominant steel industry, extensive smelting capacity, and strong industrial base. Inner Mongolia is a major ferroalloy production hub, benefiting from relatively low-cost electricity, abundant coal and renewable energy resources, and established industrial infrastructure. Domestic supply largely supports China’s substantial internal demand, while the country also remains a major exporter of ferrosilicon and manganese alloys. Government efforts to address overcapacity, improve energy efficiency, and reduce carbon emissions are encouraging industry consolidation and technology upgrades, while weaker property-sector activity is increasing producers’ reliance on export markets and contributing to greater trade scrutiny in international markets.
Europe Ferroalloys Market Trends
The ferroalloys market in Europe is supported by established steelmaking and industrial activity across major economies such as Germany, France, Italy, the UK, and Spain, with demand driven by automotive, construction, machinery, and advanced manufacturing applications. However, high and volatile energy costs, stringent environmental regulations, and the region’s decarbonization agenda are placing pressure on ferroalloy smelters and increasing reliance on imports. The implementation of CBAM and the shift toward electric arc furnaces and hydrogen-based steelmaking are reshaping import patterns and demand for specific alloy grades.
The Germany ferroalloys market is a major center of ferroalloy demand in Europe, supported by its large steel industry and strong automotive and machinery manufacturing base. Demand for ferromanganese and ferrosilicon is closely linked to the production of automotive, engineering, and industrial steel grades. High energy costs have pressured domestic smelting economics and increased reliance on imported ferroalloys. Meanwhile, decarbonization initiatives and investments in hydrogen-based steelmaking are expected to increase demand for lower-carbon and application-specific ferroalloy grades.
Latin America Ferroalloys Market Trends
The ferroalloys market in Latin America is comparatively modest globally but benefits from Brazil’s large steel and mining industry, with regional demand supported by construction, automotive, and infrastructure development. Consumption is influenced by economic conditions, currency fluctuations, and infrastructure investment cycles, while countries rely on a mix of domestic production and imports, with reliance on local resources and smelting capacity.
Middle East & Africa Ferroalloys Market Trends
The ferroalloys market in the Middle East & Africa is characterized by a dual role as both a major raw material and alloy-producing region and an emerging consumption center. South Africa stands out as one of the world's largest ferrochrome producers, leveraging extensive chrome ore reserves, while Gulf countries are expanding steel production capacity to diversify away from oil-dependent economies, driving rising demand for ferroalloys.
Key Ferroalloys Company Insights
Some key players operating in the market are Tata Steel Limited and Gulf Ferro Alloys Company (Sabayek).
-
Tata Ferro Alloys and Minerals Division (FAMD) of India-based Tata Steel Limited is the largest non-steel vertical of the company. Since 2012, it has produced and sold silicomanganese. The unit caters to the ferroalloy requirements of its integrated steel facility in Joda, Odisha. The company is also the largest ferroalloy producer that caters to the requirements of steel production facilities across the Asia Pacific. It has manganese and chrome ore reserves in Odisha, India.
-
Gulf Ferro Alloys Company (Sabayek), which was established in 1992 and is headquartered in Jubail, produces ferroalloys that are used in steel making. Presently, it is the largest producer in the GCC region, with a capacity of manufacturing 140,000 tons per year. The company offers a wide range of products, including silico manganese, ferro manganese, SiMn/FeMn slag, and fumes.
Key Ferroalloys Companies
The following key companies have been profiled for this study on the ferroalloys market.
-
Anyang Lishi Industrial Co., Ltd.
-
Cronimet Holding GmbH
-
Glencore
-
NIPPON DENKO CO., LTD.
-
S.C. Feral S.R.L
-
Sabayek
-
SAIL
-
Samancor Chrome
-
Tata Steel Limited
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Global Players: (Cronimet Holding GmbH, Glencore, NIPPON DENKO CO., LTD., Samancor Chrome, Tata Steel Limited)
- Expand ferroalloy production capacity and strengthen integrated operations across mining, ore processing, smelting, and distribution.
- Secure long-term access to chrome, manganese, and other raw materials while optimizing energy-intensive smelting operations.
- Develop lower-carbon production routes, improve furnace efficiency, and strengthen recycling and resource recovery capabilities.
- Strong international presence and established relationships with large steel producers support stable demand and access to major markets.
- Vertical integration across mining and ferroalloy production provides greater control over raw-material supply and production costs.
- Large-scale production facilities and diversified product portfolios support consistent volumes, product quality, and customer requirements.
- High exposure to electricity, ore, reductant, and other input-cost fluctuations due to the energy-intensive nature of ferroalloy production.
- Large integrated operations require significant capital investment and can involve higher operational complexity.
- Dependence on steel production cycles makes demand sensitive to fluctuations in global industrial activity and steel output.
Regional & Specialized Players: (Anyang Lishi Industrial Co., Ltd., S.C. Feral S.R.L, Sabayek, SAIL)
- Focus on selected ferroalloy products, grades, and regional steelmaking markets to strengthen customer relationships.
- Improve production flexibility and offer customized alloy specifications, volumes, and delivery schedules based on customer requirements.
- Leverage regional raw-material availability, energy economics, and proximity to steel producers to maintain cost competitiveness.
- Strong regional customer relationships support repeat business with steel mills, foundries, and alloy consumers.
- Greater production flexibility enables faster response to changes in customer specifications, order sizes, and market demand.
- Specialized product expertise allows companies to focus on selected ferroalloys and applications rather than competing across broad portfolios.
- Smaller production scale can limit purchasing power and create higher exposure to raw-material and energy-cost volatility.
- More concentrated geographic exposure increases sensitivity to regional steel production and economic conditions.
- Limited global production and distribution networks can constrain access to major international customers.
Recent Developments
-
In June 2026, Jai Dadi Group began construction of the USD 16 million Nile Ferro Alloys plant in Egypt’s East Ismailia Industrial Zone within Sinai’s Technology Valley. The 80,000-square-meter facility is expected to create around 300 direct jobs and will produce silicomanganese, intermediate iron products from scrap metal, and other ferroalloys for infrastructure, heavy engineering, and railway component manufacturing industries.
-
In June 2026, Maithan Alloys Limited received approval from the National Company Law Tribunal (NCLT), Kolkata Bench, for the merger of Impex Metal & Ferro Alloys Limited with Maithan Alloys. As Impex Metal is a wholly owned subsidiary of Maithan Alloys, the merger will not require the issuance of new equity shares, while promoter shareholding will remain unchanged.
-
In October 2025, Outokumpu announced a USD 45 million investment to establish a pilot plant for chromium metal production in the US. The facility is intended to develop domestic production capabilities for critical chromium materials and will produce enriched ferrochrome containing approximately 65% chromium and chromium metal containing more than 90% chromium, supporting a more secure and sustainable raw material supply for the North American stainless steel industry.
Ferroalloys Market Report Scope
Report Attribute
Details
Market Definition
The ferroalloys market size represents the apparent consumption of ferroalloys across carbon & low alloy steel, stainless steel, alloy steel, cast iron, and other applications.
Market size in 2025
USD 57.1 billion
Estimated market size in 2026
USD 61.0 billion
Projected market size by 2033
USD 102.3 billion
Growth rate
CAGR of 7.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in kilotons, Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Volume forecasts, revenue forecasts, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Turkey; Russia; China; India; Japan; Brazil
Key companies profiled
Anyang Lishi Industrial Co., Ltd.; Cronimet Holding GmbH; Glencore; NIPPON DENKO CO., LTD.; S.C. Feral S.R.L; Sabayek; SAIL; Samancor Chrome; Tata Steel Limited
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase; addition or alteration to country, regional, and segmentation scope
Pricing and purchase options
Avail customized purchase options to meet your exact research requirements; Explore purchase options
Global Ferroalloys Market Report Segmentation
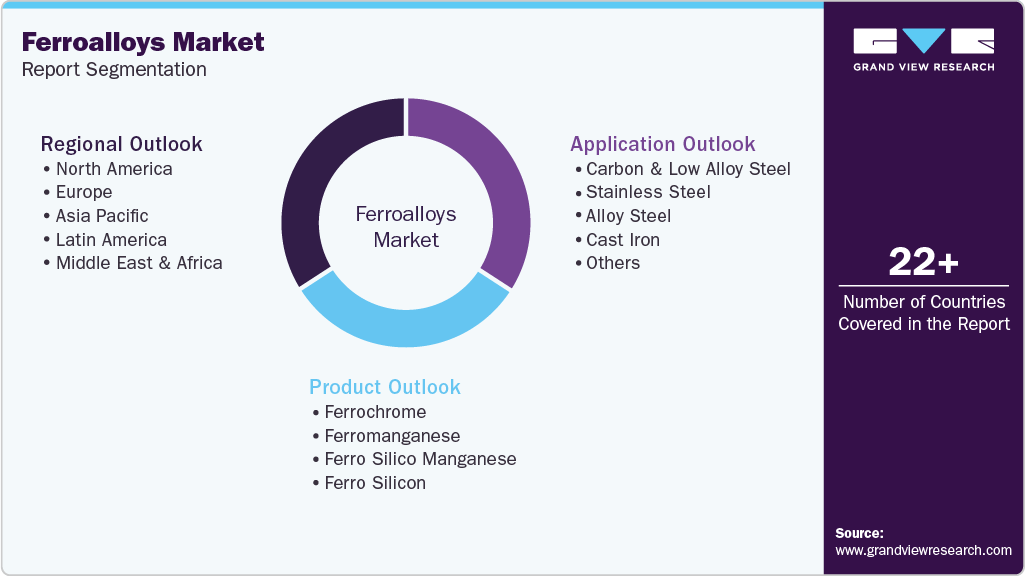
This report forecasts revenue and volume growth of the market at the global, country, and regional levels and provides an analysis of the latest trends in each of the sub-segments of the market from 2021 to 2033. For this study, Grand View Research, Inc. has segmented the global ferroalloys market report based on product, application, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Ferrochrome
-
Ferromanganese
-
Ferro Silico Manganese
-
Ferro Silicon
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Carbon & Low Alloy Steel
-
Stainless Steel
-
Alloy Steel
-
Cast Iron
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Turkey
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Research Methodology
The ferroalloys marketfigures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with eachferroalloys segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue Capture Definition
Ferrochrome
This segment includes chromium-based ferroalloys produced by reducing chromite ore in submerged arc furnaces. Ferrochrome is primarily used as a source of chromium in stainless steel production, where it improves corrosion resistance, hardness, and durability. It is also used in alloys and specialty steels that require enhanced mechanical and thermal properties.
Ferromanganese
This segment comprises manganese-based ferroalloys produced by smelting manganese ore with carbonaceous reductants. Ferromanganese is mainly used in steelmaking as an alloying and deoxidizing agent. It improves steel strength, hardness, toughness, and wear resistance and is widely consumed in carbon, low-alloy, and specialty steel production.
Ferrosilico manganese
This segment includes manganese- and silicoSn-based ferroalloys produced using manganese ore, quartz or quartzite, and carbonaceous reductants. Ferrosilico manganese serves as both an alloying and deoxidizing agent in steelmaking. Its combined manganese and silicon content makes it widely used in carbon steel, structural steel, and other steel grades requiring controlled alloy composition.
Ferrosilicon
This segment comprises silicon-based ferroalloys produced primarily from quartz or quartzite and carbonaceous reductants. Ferrosilicon is mainly used as a deoxidizer and alloying additive in steel production. It is also used in cast iron production and as a reducing agent in the manufacture of other ferroalloys.
Application
Revenue Capture Definition
Carbon & Low Alloy Steel
This segment represents ferroalloy consumption in the production of carbon and low-alloy steel, including structural steel, automotive steel, construction products, machinery, rails, and engineering components. Revenue is generated from the sales of ferroalloys to carbon and low-alloy steel manufacturers for use during steelmaking and refining processes.
Stainless Steel
This segment covers ferroalloy consumption in stainless steel manufacturing, primarily ferrochrome, as well as manganese- and silicon-based alloys. Revenue is generated from ferroalloy sales to stainless steel manufacturers serving construction, automotive, industrial equipment, appliances, and consumer applications.
Alloy Steel
This segment includes ferroalloys used in the production of alloy and specialty steel for automotive, energy, and engineering applications. Revenue is generated from the sales of ferroalloys to alloy steel manufacturers based on their requirements for different steel grades and production volumes.
Cast Iron
This segment represents ferroalloy consumption by foundries and cast iron manufacturers producing automotive castings, pipes, and other cast products. Revenue is generated from ferroalloy sales to foundries and cast iron manufacturers for use in melting and casting operations.
Others
This segment includes ferroalloy applications in specialty steel, welding and electrode manufacturing, foundries, and other metallurgical processes outside the major steel and cast iron categories. Revenue is generated from the sales of ferroalloys to manufacturers and industrial users across these applications.
Estimation Model
Layer Name
Key Question
Description
Addressable Metal Production Base Layer
What is the potential demand base for ferroalloys?
Quantify the production base of major ferroalloy-consuming industries, including carbon & low alloy steel, stainless steel, alloy steel, cast iron, and other applications. Assess production volumes, operating capacity, steel grade mix, production routes, utilization rates, and new capacity additions to establish the addressable ferroalloy consumption base.
Ferroalloy Consumption Intensity Layer
How much ferroalloy is consumed per unit of metal production?
Establish product- and application-specific ferroalloy consumption coefficients, expressed as kg or tons of ferroalloy consumed per ton of steel or cast iron output. Account for differences in steel grade, alloy composition, production process, furnace technology, recovery rates, and alloying requirements.
Ferroalloy Demand Layer
What quantity of ferroalloys is required?
Calculate annual ferroalloy demand by applying the relevant consumption intensity to the corresponding metal production base. Incorporate requirements from new capacity, ongoing production, grade-specific alloying, replacement, and process losses. The resulting demand is quantified in tons of ferroalloys and segmented by product type and application.
Pricing & Revenue Layer
What is the monetary value of ferroalloy demand?
Estimate market revenue by multiplying calculated ferroalloy consumption volumes by applicable average selling prices (ASP). Pricing is differentiated by ferroalloy type, grade, composition, and region, taking into account raw-material costs, energy costs, freight, import/export values, and prevailing market prices to derive representative market values.
Delivered Customizations
We have successfully delivered the following deep-dive customizations
Client Request
Customization Delivered
Value Adds
Ferroalloy Product Segmentation & Demand Analysis
Detailed assessment of the global market across ferrochrome, ferromanganese, ferrosilicomanganese, and ferrosilicon, including product characteristics, grade specifications, consumption patterns, and demand across carbon & low alloy steel, stainless steel, alloy steel, cast iron, and other applications.
Identifies shifts in ferroalloy demand by product and application, changing steel-grade requirements, and opportunities across major steelmaking and foundry applications.
Ferroalloy Trade & Supply Chain Analysis
Assessment of international trade in ferroalloys and key raw materials, covering imports, exports, major trading countries, trade values, volumes, unit values, and sourcing patterns across relevant HS codes.
Evaluates international supply dependence, major production and trading hubs, trade flows, supplier concentration, and potential supply-chain vulnerabilities across key ferroalloy products.
Ferroalloy Pricing & Raw-Material Analysis
Analysis of ferroalloy pricing based on product type, grade, raw-material composition, electricity consumption, manufacturing requirements, transportation costs, and international trade values, supplemented by assessment of key inputs such as chromite, manganese ore, quartz/quartzite, coke, coal, and reductants.
Identifies the major factors influencing ferroalloy prices, cost pressures across the production value chain, differences between ferroalloy products, and opportunities for production-cost optimization.
Frequently Asked Questions About This Report
Based on product, the ferrosilico manganese segment led with a 37.2% revenue share in 2025 owing to the surging steel demand from the EV and aerospace industries.
The key drivers for the growth of the global ferroalloys market are the increasing non-residential construction in developed countries and the surging number of low-cost, affordable housing unit projects in emerging countries.
Asia Pacific dominated with a 74.1% revenue share in 2025.
The stainless steel segment led with a 40.0% revenue share in 2025
Asia Pacific is anticipated to grow at the fastest CAGR during the forecast period
Based on the application, the alloy steel segment is the fastest-growing over the forecast period.
The global ferroalloys market size was valued at USD 57.1 billion in 2025 and is estimated at USD 61.0 billion for 2026.
The global ferroalloys market is expected to grow at a CAGR of 7.7% from 2026 to 2033, reaching USD 102.3 billion by 2033.
Key players include Anyang Lishi Industrial Co., Ltd.; Cronimet Holding GmbH; Glencore; NIPPON DENKO CO., LTD.; S.C. Feral S.R.L; Sabayek; SAIL; Samancor Chrome; Tata Steel Limited
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


