
- Home
- »
- Distribution & Utilities
- »
-
Micro Inverter Market Size, Share, Trends Report, 2026-2033GVR Report cover

Micro Inverter Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Single-Phase, Three-Phase), By Application (Residential, Commercial), By Region (North America, Europe, Asia Pacific, CSA, MEA), And Segment Forecasts
Market Size, 2025
$5.8BMarket Estimate, 2026
$7.2BMarket Forecast, 2033
$37.6BCAGR, 2026–2033
26.7%Micro Inverter Market Summary
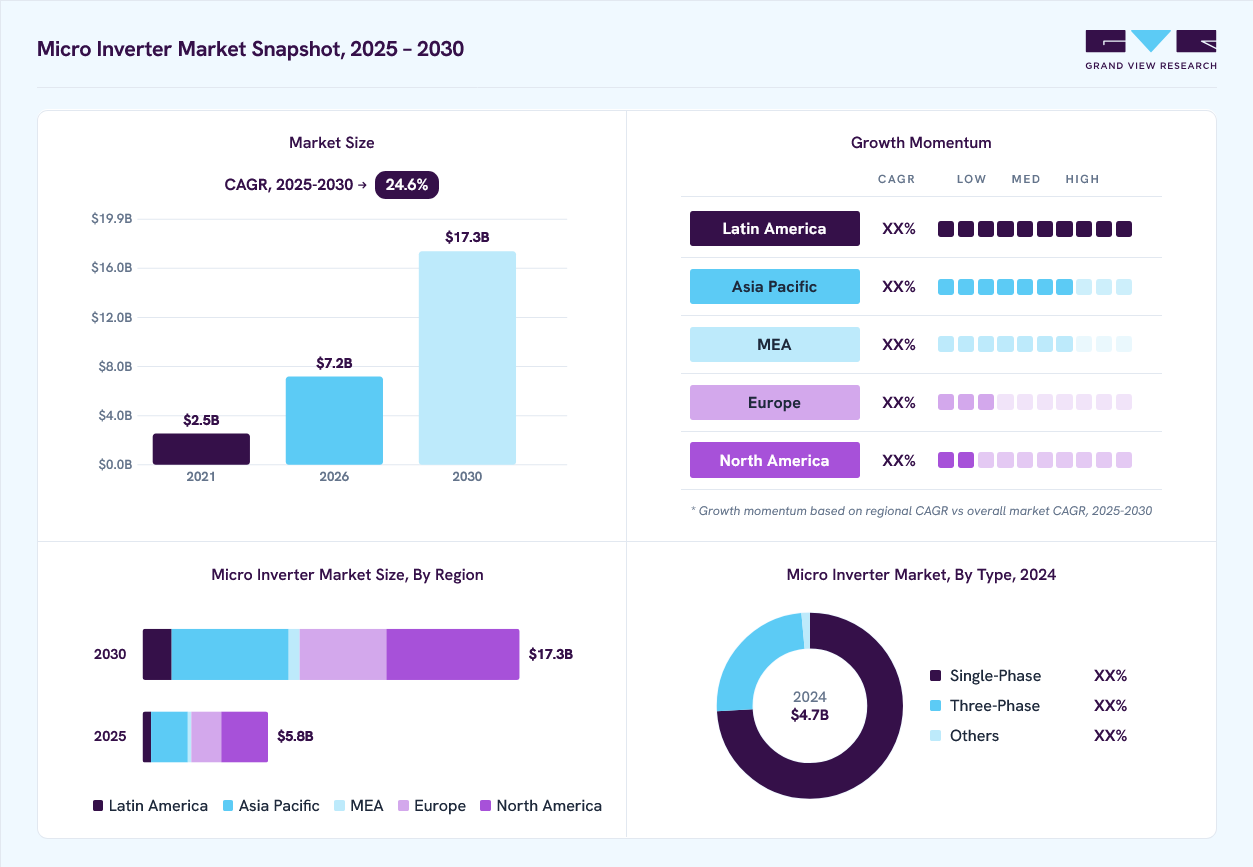
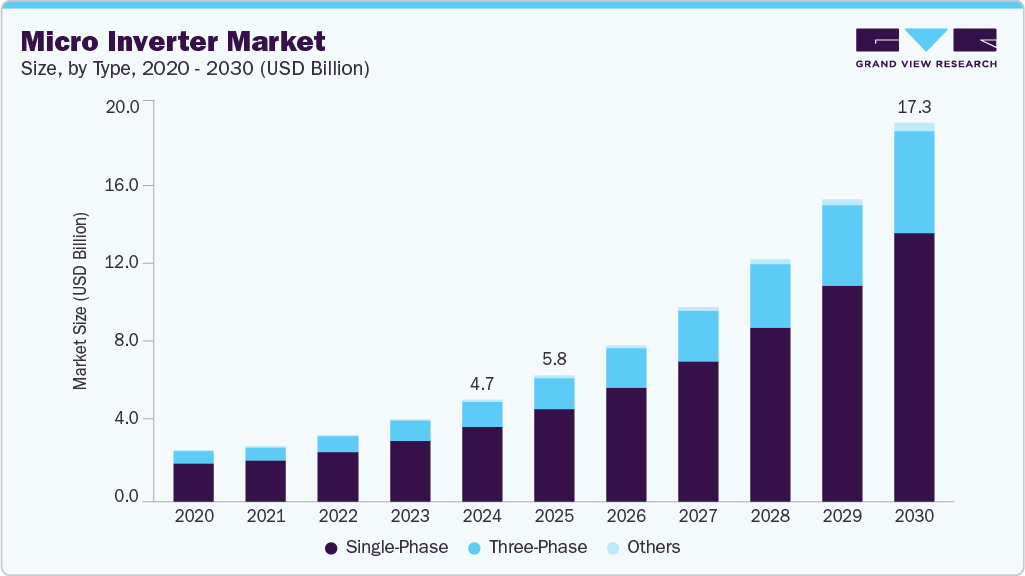
The global micro inverter market size was valued at USD 5.8 billion in 2025 and is projected to grow from USD 7.2 billion in 2026 to USD 37.6 billion by 2033, at a CAGR of 26.7% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.3% in 2025. The market is experiencing steady growth, driven by the rising adoption of rooftop solar systems and the increasing emphasis on maximizing energy efficiency.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Single-phase segment dominated the market, with a revenue share of 73.5% in 2025.
- By application: Residential segment held the largest market share of 78.6% in 2025.
Regional Highlights
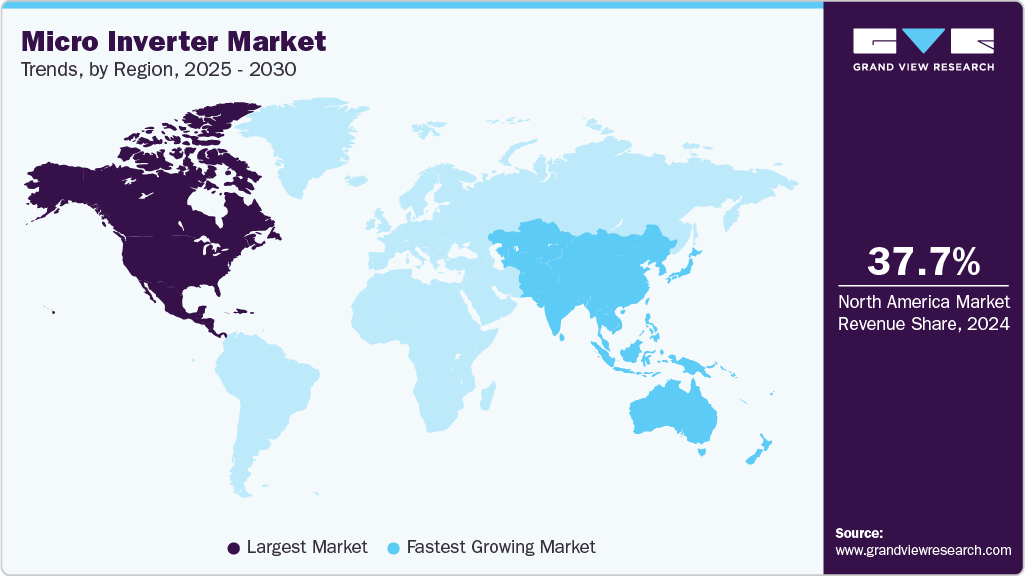
- Largest regional market: North America (37.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.8 Billion
- Estimated market size in 2026: USD 7.2 Billion
- Projected market size by 2033: USD 37.6 Billion
- CAGR (2026-2033): 26.7%
Prism AI by Grand View Research Free to tryAsk a question about the micro inverter marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Factors such as the growing shift toward module-level power electronics (MLPE), enhanced system performance, and safety benefits fuel the demand for micro inverters across residential and small-scale commercial applications. In addition, advancements in solar technology and supportive policy frameworks are accelerating the deployment of microinverters in key regions. The integration of smart grid capabilities, along with declining solar installation costs, is further encouraging adoption. Moreover, government incentives and renewable energy targets are boosting the uptake of distributed solar systems, positioning micro inverters as a preferred choice for optimizing output and ensuring flexibility in system design.
 To learn more about this report, Download Free Sample Report
Technological advancements, including integrating smart home systems and the internet of things (IoT), significantly improve micro inverters' performance and monitoring capabilities. These innovations enable real-time data analytics, fault detection, and remote maintenance, enhancing energy yield and system reliability. As energy systems become increasingly decentralized, micro inverters are vital in optimizing solar output and supporting grid stability, aligning well with global efforts toward cleaner and more resilient energy infrastructures.
The residential and small commercial sectors rapidly embrace micro inverter technology due to its scalability, ease of installation, and safety benefits, such as reduced fire risk. The modular nature of micro inverters allows for flexible solar system design and better performance in shaded or complex rooftop conditions, making them especially suitable for urban environments. This trend is particularly strong in North America and Europe, where supportive policies, net metering schemes, and consumer awareness drive solar adoption.
However, the market faces challenges such as higher upfront costs than traditional string inverters and compatibility issues in certain large-scale installations. Nonetheless, continuous R&D efforts and economies of scale are expected to bring down prices and broaden the application scope of micro inverters. As the global push for renewable energy intensifies, micro inverters are set to become a key component in advancing the efficiency, safety, and accessibility of solar power systems worldwide.
Market Dynamics
The micro inverter market is primarily driven by the increasing adoption of distributed solar photovoltaic (PV) systems across residential and commercial sectors, supported by favorable renewable energy policies, declining solar installation costs, and rising investments in rooftop solar projects. Micro inverters improve system efficiency by enabling module-level power conversion and maximum power point tracking (MPPT), allowing each solar panel to operate independently and minimizing energy losses caused by shading, dust accumulation, or panel mismatch. In addition, advancements in power electronics, digital monitoring platforms, and smart grid technologies are supporting the widespread adoption of microinverter solutions worldwide.
The growing deployment of rooftop solar photovoltaic systems is a major driver of the micro inverter market. Residential homeowners, commercial building owners, and small businesses are increasingly investing in rooftop solar installations to reduce electricity costs, improve energy independence, and meet sustainability goals. Unlike conventional string inverters, micro inverters optimize each solar module's performance through module-level maximum power point tracking (MPPT), resulting in higher energy yields, improved system reliability, and enhanced operational safety. These advantages are accelerating their adoption across both new installations and retrofit projects.
Furthermore, supportive government incentives, net-metering policies, renewable energy targets, and financial programs promoting distributed solar generation continue to strengthen market growth. The rapid expansion of residential solar installations in countries such as the U.S., Germany, Australia, and India, coupled with increasing consumer demand for smart energy management and real-time system monitoring, is further driving the adoption of micro inverter technology. Continuous product innovations focused on higher conversion efficiency, longer operational life, and compatibility with battery energy storage systems are expected to sustain market growth throughout the forecast period.
Despite their operational advantages, micro inverters have higher upfront installation costs than traditional string inverter systems because each solar module requires an individual inverter. This increases initial project expenditure, particularly for large-scale installations. In contrast, fluctuations in semiconductor component prices and the need for specialized installation expertise may further limit adoption in cost-sensitive markets.
The increasing integration of residential battery storage systems, smart home energy management platforms, and distributed energy resources presents significant growth opportunities for the micro inverter market. As consumers and utilities increasingly adopt intelligent energy management solutions, demand for micro inverters with advanced monitoring capabilities, grid support functions, and seamless compatibility with battery storage systems is expected to accelerate over the forecast period.
Analyst Perspective
The micro inverter market is experiencing robust growth, driven by the increasing deployment of distributed solar photovoltaic (PV) systems, supportive renewable energy policies, and rising investments in residential and commercial rooftop solar installations. Growing demand for higher energy generation efficiency, module-level monitoring, and enhanced system reliability is accelerating the adoption of micro inverters over conventional string inverter technologies. While higher initial installation costs and semiconductor supply chain constraints remain key challenges, continuous advancements in power electronics and digital monitoring platforms are improving product performance and expanding application opportunities. In the coming years, companies that can strengthen technological innovation, enhance product efficiency, expand global distribution networks, and develop integrated smart energy solutions are expected to strengthen their competitive position in the global micro inverter market.
Type Insights
Based on type, the single-phase segment led the market with the largest revenue share of 73.5% in 2025, primarily driven by its widespread application in residential and small commercial solar installations. Single-phase micro inverters are well-suited for low to medium-energy demand systems, offering a cost-effective and efficient solution for rooftop solar projects. Their ability to optimize the output of individual solar panels makes them ideal for installations where shading or panel orientation may vary. Furthermore, ease of installation and integration with standard household electrical systems has further fueled their adoption, especially in regions with high solar rooftop penetration, such as North America and Europe.
As decentralized energy systems become more prevalent, the demand for flexible and modular solar solutions like single-phase micro inverters continues to grow. These systems also support smart grid compatibility and enable real-time performance monitoring at the panel level, which enhances energy yield and system reliability. The segment benefits from growing awareness of clean energy, supportive government incentives, and the increasing affordability of solar components. While three-phase inverters are favored in larger commercial and industrial setups, single-phase micro inverters remain the top choice for homeowners and small businesses seeking to maximize solar efficiency with minimal complexity.
Application Insights
Based on applications, the residential segment led the market with the largest revenue share of 78.6% in 2025, driven by the growing adoption of rooftop solar systems among homeowners seeking energy independence and cost savings. Micro inverters are particularly well-suited for residential applications due to their ability to optimize the output of each solar panel, which is critical in rooftop settings where shading, panel orientation, and roof angles can vary. Their ease of installation, enhanced safety features, and compatibility with single-phase power systems further support widespread deployment in the residential sector, especially in countries with favorable net metering policies and solar subsidies.
 To learn more about this report, Download Free Sample Report
The demand for residential solar installations is also propelled by increasing electricity costs and heightened environmental awareness. Homeowners are turning to solar energy to reduce utility bills and contribute to sustainability goals. Micro inverters add value by enabling real-time monitoring, efficient energy conversion, and lower maintenance requirements. As solar panel prices continue to decline and smart home integration becomes more prevalent, micro inverters are expected to remain the preferred choice for residential users seeking reliable, high-performance solar solutions with minimal operational complexity.
Regional Insights
North America dominated the micro inverter market with the largest revenue share of 37.3% in 2025. The North American micro-inverter market leads globally, driven by strong adoption of residential rooftop solar systems, favorable government incentives, and increasing demand for high-efficiency, module-level power electronics. The U.S. dominates the regional market, supported by federal tax credits, net metering policies, and state-level solar initiatives encouraging household solar adoption. Technological advancements, including integrated monitoring systems and enhanced safety features, make micro inverters a preferred choice for homeowners and small businesses. Canada also sees increased demand, particularly in off-grid and hybrid solar installations across rural and remote communities.
 To learn more about this report, Download Free Sample Report
U.S. Micro Inverter Market Trends
The micro inverter market in the U.S. held the largest share in North America region in 2025. The micro inverter market in the U.S. is experiencing strong momentum, fueled by federal tax incentives, net metering policies, and a sharp rise in residential solar installations. Consumers increasingly opt for micro inverters due to their enhanced safety, individual panel-level optimization, and ability to maintain system performance even under shading or panel mismatch conditions. The growing popularity of smart homes and energy monitoring solutions further boosts demand, as micro inverters offer real-time visibility and remote system control.
Asia Pacific Micro Inverter Market Trends
The micro inverter market in Asia Pacific is emerging as one of the fastest-growing regions in the micro-inverter market, propelled by expanding solar installations, rapid urbanization, and ambitious renewable energy targets. Countries like China, India, Japan, and Australia drive growth through large-scale rooftop programs and pro-solar government policies. The growing middle class and demand for reliable, decentralized energy encourage residential users to invest in solar with micro inverter solutions. Moreover, falling costs of solar components and increasing awareness of micro-inverter benefits, such as performance optimization and safety, are accelerating adoption across urban and rural settings.
Europe Micro Inverter Market Trends
The micro inverter market in Europe is expanding steadily, supported by the region’s strong emphasis on renewable energy integration and distributed generation. Nations like Germany, the Netherlands, and France are at the forefront of residential solar adoption, aided by feed-in tariffs and regulatory frameworks that promote clean energy. The push for energy independence, especially in response to geopolitical uncertainties, encourages households and small businesses to invest in self-sustaining solar systems equipped with microinverters. In addition, the trend toward smart homes and grid-connected solutions aligns well with micro inverter technology, further boosting market demand.
Latin America Micro Inverter Market Trends
The micro inverter market in Latin America is witnessing the growing adoption of microinverters as solar power becomes a more viable and attractive energy option across the region. Countries like Brazil, Mexico, and Chile are leading in residential and small commercial solar deployment due to high solar irradiance and increasing electricity costs. Micro inverters are favored in this context for their scalability, ease of installation, and ability to maintain performance under partial shading conditions. Government-led rural electrification efforts and favorable policies are also playing a role in driving market growth, particularly in underserved or remote areas.
Middle East & Africa Micro Inverter Market Trends
The micro inverter market in the Middle East and Africa is gradually expanding, driven by rising interest in decentralized solar solutions to overcome grid unreliability and expand energy access. The UAE and Saudi Arabia are investing in rooftop solar initiatives as part of long-term clean energy strategies, such as Vision 2033 and Energy Strategy 2050. In sub-Saharan Africa, microinverters are gaining traction in off-grid and mini-grid solar projects due to their reliability, safety, and ability to function independently at the panel level. As solar costs continue to fall and demand for resilient power systems grows, micro inverters are poised for wider adoption across the region.
Key Micro Inverter Company Insights
Some key players operating in the market are Enphase, Darfon Electronics Corporation, Deye Inverter, Sparq Systems, Fimer Group, Solis Solar, Tata Power Solar, and others.
Key Micro Inverter Companies
The following key companies have been profiled for this study on the micro inverter market.
-
Deye Inverter
-
Darfon Electronics Corporation
-
Enphase
-
Fimer Group
-
Fenice Energy
-
Sparq Systems
-
Sensol
-
Statcon Energiaa
-
SunEvo Solar
-
Solis Solar
-
Tata Power Solar
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Enphase Energy, Inc., Altenergy Power System Inc. (APsystems), Hoymiles Power Electronics Inc., Darfon Electronics Corporation, FIMER S.p.A.)
- Focus on the large-scale development and commercialization of micro inverter solutions supported by global distribution networks and strategic partnerships with solar installers, distributors, and EPC companies.
- Emphasize product innovation, module-level monitoring capabilities, high conversion efficiency, product reliability, and integration with residential and commercial solar energy systems.
- Benefit from strong brand recognition, advanced power electronics expertise, broad product portfolios, and well-established global sales and service networks.
- Continuous investments in research and development, manufacturing scale, and digital energy management platforms support product differentiation and long-term customer relationships.
- Face high research and development expenditures, semiconductor component procurement challenges, and increasing competition from lower-cost manufacturers.
- Business performance may be affected by fluctuations in solar installation activity, policy incentives, supply chain disruptions, and pricing pressure across the distributed solar market.
Emerging & Specialized Players (e.g., SPARQ Systems Inc., Chilicon Power, LLC (a Generac company), Northern Electric Power Technology Inc. (NEP), NingBo Deye Inverter Technology Co., Ltd., Zhejiang Envertech Corporation Ltd.)
- Focus on specialized micro inverter technologies, smart energy management solutions, and application-specific products targeting residential, commercial, and distributed photovoltaic installations.
- Emphasize technological innovation, product customization, strategic collaborations, and regional market expansion to strengthen competitive positioning.
- Benefit from operational flexibility, faster product development cycles, and the ability to address evolving customer requirements through specialized micro inverter solutions and advanced monitoring technologies.
- Agile business models enable rapid adoption of new technologies, competitive pricing strategies, and expansion into emerging distributed solar markets.
- Limited global brand recognition, manufacturing scale, and distribution networks compared with established market leaders.
- Expansion often requires significant investments in production capacity, international distribution partnerships, product certifications, and customer acquisition to compete effectively in the global micro inverter market.
Recent Developments
-
In February 2024, Enphase Energy announced the launch of its new IQ8P Microinverter, designed to support higher-powered solar panels up to 480 W. This innovation aligns with the growing trend toward more powerful residential PV systems. It offers improved energy harvesting and faster installation.
-
In January 2024, Darfon Electronics expanded its micro inverter product line by releasing a three-phase model targeting small commercial rooftop projects. The launch supports the growing shift towards scalable, distributed energy systems that optimize performance and safety at the panel level.
Micro Inverter Report Scope
Report Attribute
Details
Market definition
The global micro inverter market refers to the revenue generated from the sales of micro inverters used in residential, commercial, and small-scale industrial solar photovoltaic (PV) systems to convert direct current (DC) generated by individual solar modules into grid-compatible alternating current (AC).
Market size in 2025
USD 5.8 billion
Estimated market size in 2026
USD 7.2 billion
Projected market size by 2033
USD 37.6 billion
Growth rate
CAGR of 26.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S, Canada, Mexico, Germany, Spain, UK, Russia, France, Italy, India, China, Japan, Australia, Brazil, Argentina, Saudi Arabia, South Africa, UAE
Key companies profiled
Enphase Energy, Inc., Altenergy Power System Inc. (APsystems), Hoymiles Power Electronics Inc., Darfon Electronics Corporation, SPARQ Systems Inc., Chilicon Power, LLC (a Generac company), Northern Electric Power Technology Inc. (NEP), NingBo Deye Inverter Technology Co., Ltd., Zhejiang Envertech Corporation Ltd., and FIMER S.p.A.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Micro Inverter Market Report Segmentation
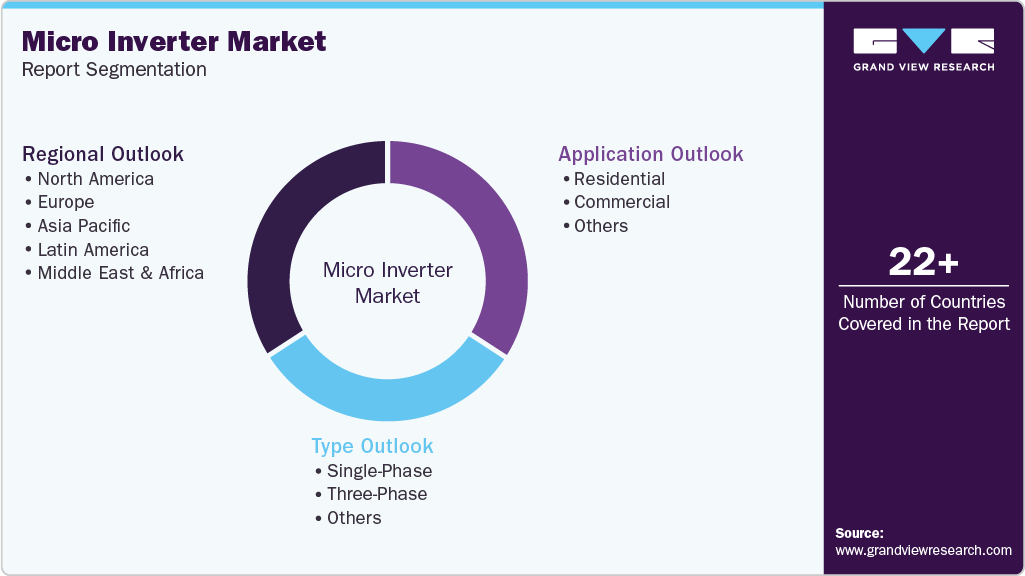
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global micro inverter market report based on type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Single-Phase
-
Three-Phase
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Residential
-
Commercial
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Spain
-
France
-
Italy
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The micro inverter market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each micro inverter segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Type
Revenue Capture Definition
Single-Phase
Single-phase micro inverters are primarily deployed in residential and small commercial solar photovoltaic (PV) systems where electricity is supplied through single-phase distribution networks. Market revenue is attributable to the manufacturing, sale, installation, and replacement of single-phase micro inverters, module-level power electronics, monitoring platforms, software integration, and related aftermarket services that support distributed solar energy systems.
Three-Phase
Three-phase micro inverters are designed for commercial, industrial, and large distributed solar installations that require three-phase power output. Revenue is generated through the production, distribution, and deployment of three-phase micro inverters, advanced power conversion technologies, energy management systems, monitoring software, installation services, and associated maintenance activities across commercial and industrial solar projects.
Others
This segment includes specialized microinverter solutions for niche solar applications, hybrid energy systems, portable solar installations, and emerging distributed energy technologies. Revenue is derived from the sale of customized micro-inverter products, integrated power electronics, specialized monitoring solutions, engineering services, and related support for non-conventional solar energy applications.
Application
Revenue Capture Definition
Residential
Residential applications include rooftop solar photovoltaic systems installed on single-family homes, multi-family housing, and residential communities. Market revenue is generated through the sale of micro inverters, module-level monitoring systems, installation services, replacement units, software subscriptions, and maintenance services that support residential distributed solar generation.
Commercial
Commercial applications include rooftop and distributed solar installations across office buildings, educational institutions, retail facilities, warehouses, healthcare facilities, and other commercial establishments. Revenue capture includes the sale of micro inverters, energy monitoring platforms, installation and commissioning services, operation and maintenance contracts, and integrated energy management solutions designed for commercial solar systems.
Others
This segment includes micro inverter deployments across industrial facilities, agricultural buildings, public infrastructure, government projects, community solar installations, and other specialized distributed photovoltaic applications. Market revenue is attributed to equipment sales, engineering and installation services, monitoring software, system upgrades, maintenance contracts, and associated technical support for non-residential solar installations.
Estimation Model
Layer Name
Key Question
Description
Solar PV Installation Demand Base Layer
What forms the demand base?
Identify global demand for micro inverters across distributed solar photovoltaic installations. Assess rooftop solar deployment, residential and commercial PV adoption, renewable energy investments, and government incentive programs to establish the addressable market opportunity for module-level power electronics.
Micro Inverter Manufacturing & Supply Layer
Where are micro inverters manufactured and supplied?
Estimate the production capacity of micro inverters across major manufacturing regions. Analyze semiconductor component availability, power electronics manufacturing capabilities, supply chain networks, distribution channels, and strategic partnerships to evaluate product availability and market accessibility.
Application Adoption Layer
How extensively are micro inverters deployed?
Analyze the adoption of micro inverters across residential, commercial, and other distributed solar applications. Evaluate installation trends, system performance requirements, module-level monitoring adoption, energy efficiency benefits, and compatibility with battery energy storage systems, influencing market penetration.
Revenue Layer
How is market revenue generated?
Expenditures on micro inverters, module-level monitoring platforms, installation services, replacement units, and related energy management solutions quantify market revenue. Product shipments, average selling prices, solar installation volumes, and aftermarket service revenues across distributed solar applications drive the overall market value.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Micro Inverter Competitive Landscape Assessment
Detailed competitive landscape analysis covering manufacturers and suppliers of micro inverters and module-level power electronics solutions. The study profiled key market participants based on geographic presence, organizational structure, product portfolio, manufacturing capabilities, distribution networks, customer base, strategic initiatives, and investments in product innovation, smart energy technologies, and capacity expansion.
Enabled evaluation of competitive positioning, technological capabilities, distribution strengths, customer engagement strategies, and market participation across the global micro inverter value chain.
Application & Technology Assessment
Evaluation of global micro inverter demand across residential, commercial, and other distributed solar photovoltaic applications. Included assessment of micro inverter technologies, module-level power electronics, energy monitoring systems, smart grid compatibility, installation trends, regulatory frameworks, and regional solar deployment across major markets.
Highlighted application trends, technology adoption patterns, and regional growth opportunities. Supported strategic planning, product portfolio optimization, market entry evaluation, and investment prioritization decisions.
Opportunity Assessment
Identification of high-growth opportunities associated with expanding rooftop solar installations, distributed energy resources, residential battery energy storage systems, and smart energy management solutions. Assessed emerging opportunities arising from renewable energy policy support, grid modernization initiatives, increasing demand for high-efficiency solar systems, and advancements in digital monitoring and power conversion technologies.
Enabled prioritization of high-value growth opportunities and emerging application segments. Supported long-term business planning, product development strategies, geographic expansion initiatives, and investment decisions aligned with evolving distributed solar energy requirements.
Frequently Asked Questions About This Report
The key players operating in the global micro inverter market include Enphase Energy, Inc., Altenergy Power System Inc. (APsystems), Hoymiles Power Electronics Inc., Darfon Electronics Corporation, SPARQ Systems Inc., Chilicon Power, LLC (a Generac company), Northern Electric Power Technology Inc. (NEP), NingBo Deye Inverter Technology Co., Ltd., Zhejiang Envertech Corporation Ltd., and FIMER S.p.A.
The micro inverter market size was valued at USD 5.8 billion in 2025 and is estimated at USD 7.2 billion in 2026.
The micro inverter market is expected to grow at a CAGR of 26.7% from 2026 to 2033, reaching USD 37.6 billion by 2033.
Based on type, single-phase accounted for largest revenue share of 73.5% in 2025, while three-phase are anticipated to register the fastest CAGR over the forecast period.
Latin America is anticipated to register the fastest CAGR of 29.9% over the forecast period.
The key driver of the global micro inverter market is the increasing adoption of distributed solar photovoltaic (PV) systems across residential and commercial sectors. Growing investments in rooftop solar installations, supportive government incentives, declining solar PV costs, and rising demand for higher energy generation efficiency are accelerating the adoption of micro inverters.
Based on applications, residential accounted for largest revenue share of 78.6% in 2025.
North America dominated the market with revenue share of 37.3% in 2025.
About the Author(s)
Distribution & Utilities Research Team
Energy & Power · Distribution & UtilitiesThis report was authored by the distribution & utilities research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the distribution & utilities segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


