
- Home
- »
- Clinical Diagnostics
- »
-
Next Generation Tissue Biomarkers Market Report, 2033GVR Report cover

Next Generation Tissue Biomarkers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Reagents & Assays, Instruments & Platforms, Software & AI), By Type, By Technology, By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$3.3BMarket Estimate, 2026
$3.6BMarket Forecast, 2033
$6.0BCAGR, 2026–2033
7.5%Next Generation Tissue Biomarkers Market Summary
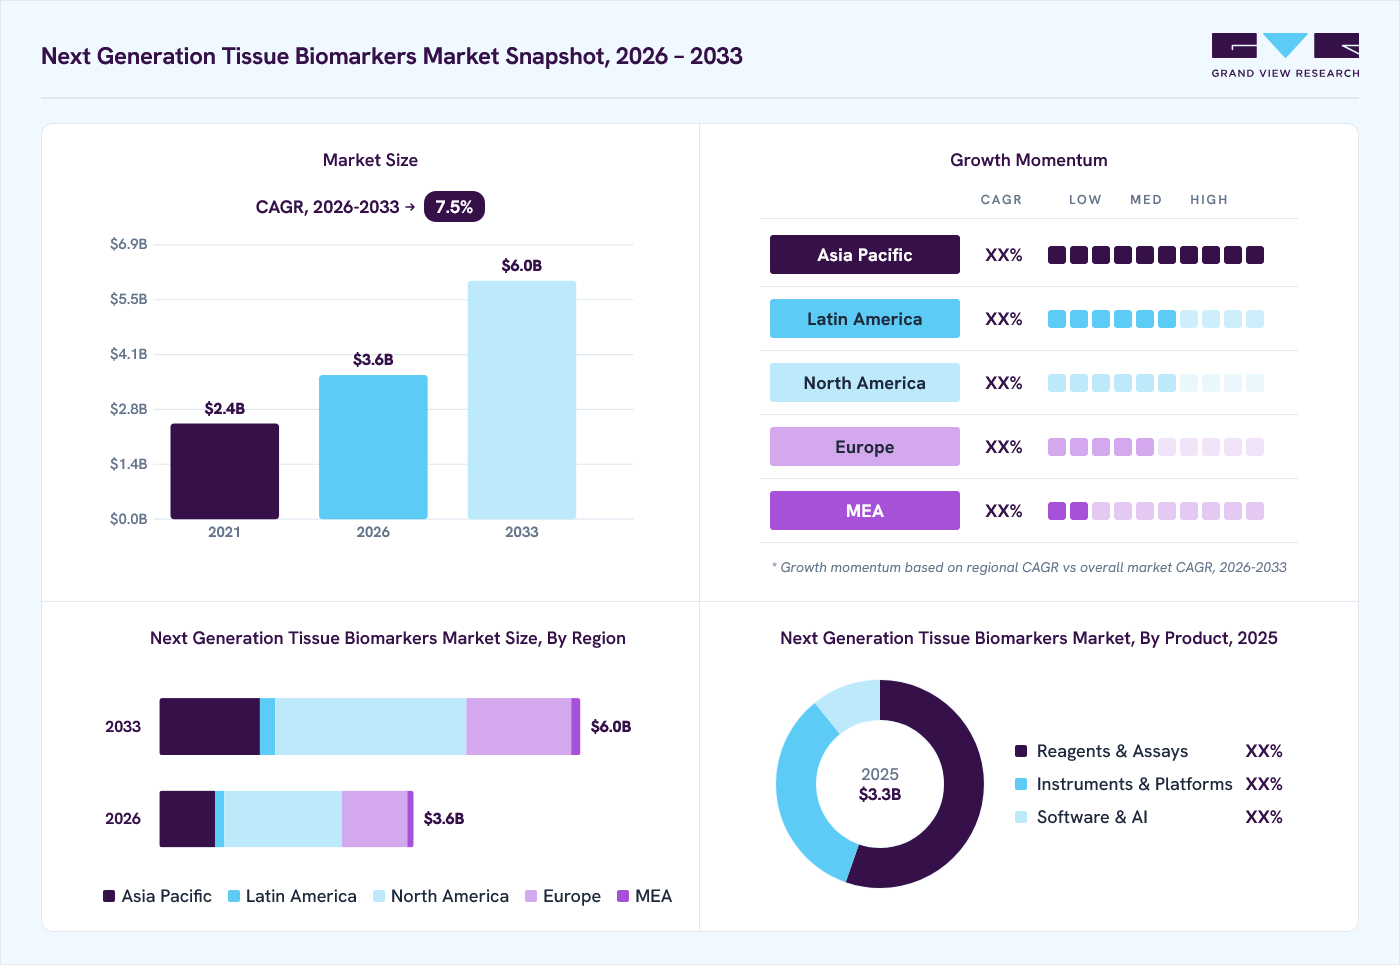
The global next generation tissue biomarkers market size was valued at USD 3.3 billion in 2025 and is projected to grow from USD 3.6 billion in 2026 to USD 6.0 billion by 2033, at a CAGR of 7.5% from 2026 to 2033. North America dominated the market with the largest revenue share of 46.4% in 2025.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Reagents & assays held the largest revenue share of 55.3% in 2025.
- By type: Genomic biomarkers held the largest revenue share of 32.9% in 2025.
- By technology: Next-Generation Sequencing (NGS) held the largest share of 28.9% in 2025.
- By application: Oncology held the largest revenue share of 59.4% in 2025.
- By end use: Hospitals & reference labs held the largest revenue share of 41.3% in 2025.
Regional Highlights
- Largest regional market: North America (46.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest revenue share of North America in 2025
Market Size & Forecast
- Market Size in 2025: USD 3.3 Billion
- Estimated Market Size in 2026: USD 3.6 Billion
- Projected Market Size by 2033: USD 6.0 Billion
- CAGR (2026-2033): 7.5%
Prism AI by Grand View Research Free to tryAsk a question about the next generation tissue biomarkers market✓Every figure cited from GVR research Prefer the report? Download free sample →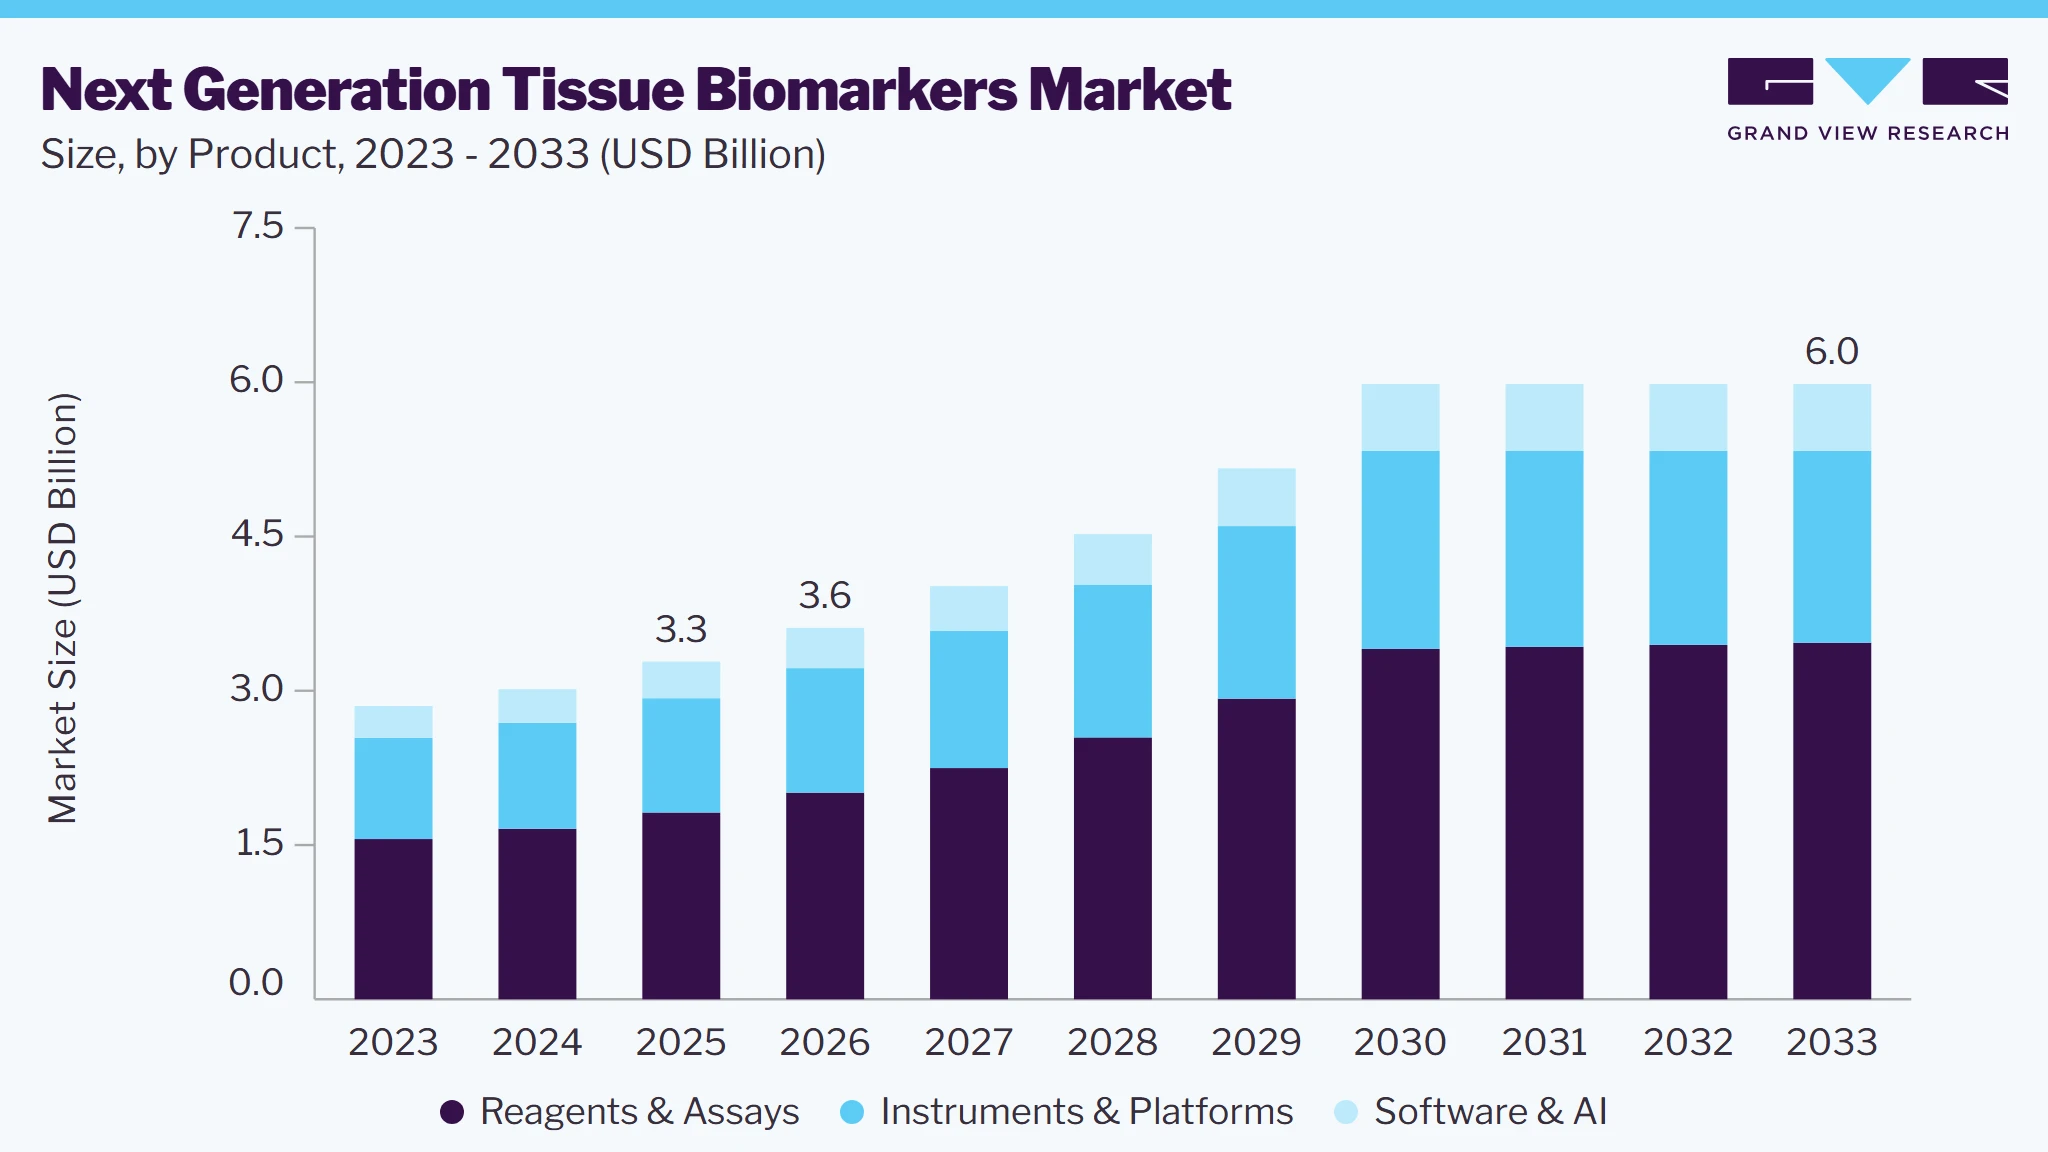 To learn more about this report, Download Free Sample Report
Market Dynamics
Increasing technological advancements for detecting next generation tissue biomarkers boost the market growth. The development of high-throughput screening technologies such as next-generation sequencing (NGS) has significantly enhanced the ability to analyze genetic mutations and gene expression profiles in cancer tissues. For instance, in November 2024, Illumina, Inc. received approval from the U.S. Food and Drug Administration (FDA) for its in vitro diagnostic (IVD) test, TruSight Oncology Comprehensive, marking a significant advancement in precision oncology. This test analyzes over 500 genes in solid tumor samples to identify biomarkers that can guide targeted therapy decisions. Furthermore, liquid biopsies, high-throughput screening technologies, epigenetic profiling, and microRNA-based biosensors are the in practice for next generation tissue biomarker detection. Collectively, these technological advancements are transforming the landscape of tissue biomarker discovery, leading to more accurate diagnostics, personalized treatment strategies, and improved patient outcomes. AI and machine learning algorithms are being incorporated into digital pathology, automating the analysis of tissue images. This is expected to enhance the discovery of new morphological biomarkers and improve diagnostic efficiency.
A major restraint in the next generation tissue biomarkers market is the lack of standardized biomarker assays, testing protocols, and interpretation methodologies across laboratories and healthcare institutions. Technologies such as multiplex immunohistochemistry (mIHC), spatial transcriptomics, AI-enabled digital pathology, and proteomic profiling often use different platforms, reagents, analytical workflows, and scoring systems, leading to variability in test results. This inconsistency makes it difficult to compare outcomes across clinical studies and limits the reproducibility of biomarker findings.
Furthermore, extensive clinical validation is required before tissue biomarkers can be routinely integrated into diagnostic workflows and treatment decision-making. Generating robust evidence through multicenter clinical studies is both time-consuming and resource-intensive, particularly for novel biomarkers intended for companion diagnostics and precision medicine applications. As a result, the adoption of new tissue biomarker technologies may be delayed despite their strong analytical performance and potential clinical value.
The market for next-generation tissue biomarkers in disease diagnosis is experiencing significant growth, driven by advancements in precision medicine, digital pathology, and biomarker discovery technologies. These developments are enhancing early disease detection, personalized treatment strategies, and overall patient outcomes.
Title
Opportunity and Impact
- Integration of Artificial Intelligence (AI) in Tissue Diagnostics
- AI-powered tools are enhancing the accuracy of diagnostic procedures and streamlining workflows.
- AI algorithms can analyze complex tissue samples, aiding pathologists in making faster and more accurate diagnoses.
- Biomarker-Based Testing for Personalized Medicine:
- Biomarker testing is gaining traction for its role in guiding targeted therapies.
- Identifying specific biomarkers in tissue samples allows for tailored treatment approaches, improving efficacy and reducing adverse effects.
- Advancements in Liquid Biopsy Techniques
- Liquid biopsies offer a non-invasive alternative to traditional tissue biopsies by detecting circulating tumor DNA and other biomarkers in blood samples.
- This approach allows for early detection of cancers and monitoring of treatment responses without the need for invasive procedures.
- Development of Comprehensive Diagnostic Panels:
- Creating panels that assess multiple biomarkers simultaneously enhances the accuracy of early disease detection.
- Comprehensive panels facilitate the identification of disease signatures at early stages, enabling prompt and appropriate interventions.
- Nanomedicine Applications in Diagnostics
- Nanotechnology enhances the sensitivity and specificity of diagnostic tests through the use of nanoparticles for biomarker detection.
- Nanomedicine enables the development of highly sensitive diagnostic tools capable of detecting low-abundance biomarkers, improving early disease diagnosis.
Market Concentration & Characteristics
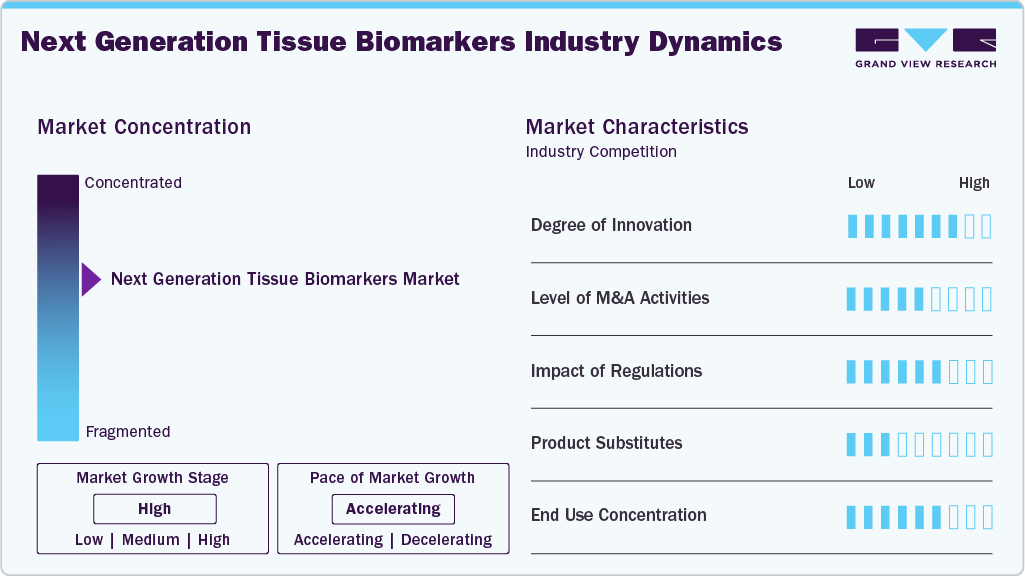
The next generation tissue biomarkers industry is marked by a high degree of innovation, by enhancing diagnostic accuracy, enabling personalized treatments, and improving patient outcomes. In April 2025,ViewsML and Dartmouth Health partnered aimed at advancing AI-driven virtual biomarkers and diagnostics. This collaboration focuses on developing virtual biomarkers through ViewsML's virtual immunohistochemistry (IHC) staining platform, which reduces reliance on traditional physical antibodies and immunostaining methods.
The market has experienced notable fluctuations over the past few years, influenced by technological advancements, market dynamics, and strategic shifts within the medical sector. According to an article from January 2025, Quanterix Corporation announced to acquire Akoya Biosciences in an all-stock transaction, aiming to create the first integrated solution for ultra-sensitive detection of both blood- and tissue-based protein biomarkers. This merger positions the combined entity to lead in the biomarker detection field, offering integrated solutions that span both blood and tissue analyses.
 To learn more about this report, Download Free Sample Report
Regulations play a crucial role in shaping the next generation tissue biomarkers market, affecting product approvals, market adoption, and innovation. Regulatory bodies like the FDA (U.S.), CE Mark (Europe), and CFDA (China) enforce strict guidelines to ensure diagnostic accuracy, patient safety, and data security.
The next-generation tissue biomarkers have significantly advanced disease diagnosis and monitoring. Several alternative diagnostic methods offer complementary or substitute options, such as proteomics, circulating free DNA analysis, and liquid biopsies. These alternatives provide diverse approaches to disease diagnosis and monitoring, each with its own set of advantages and limitations. The choice of method depends on the specific clinical context, the disease in question, and the desired information to be obtained.
The market exhibits a high level of end-user concentration, primarily driven by demand from hospitals and reference labs, pharma and biotech companies, academic and research institutions, and contract research organizations. Large healthcare networks and academic medical centers account for a significant portion of adoption, as they require high-throughput scanning and AI-powered diagnostics. Reference laboratories and contract research organizations (CROs) also contribute to market growth by utilizing digital pathology for clinical trials. While adoption is growing in smaller pathology labs, the market remains concentrated among large-scale institutions with higher diagnostic volumes and technology budgets.
New Technology and Adoption Landscape of Next Generation Tissue Biomarkers
The next generation tissue biomarkers market in tissue diagnostics is undergoing rapid transformation, driven by advancements in AI, whole slide imaging (WSI), telepathology, and automation. These innovations are improving diagnostic accuracy, workflow efficiency, and accessibility, leading to increased adoption across hospitals, research institutions, and diagnostic laboratories.
New Technology and Adoption Landscape of Next Generation Tissue biomarkers
Advanced genomic profiling: The landscape of next-generation tissue biomarkers has significant advancements in precision medicine, genomics, and diagnostics:
Next-Generation Sequencing (NGS): These platforms provide comprehensive insights into genomic mutations, gene expression patterns, and epigenetic alterations in tumors or other tissues.
Example: FoundationOne by Foundation Medicine.
-
Single-Cell RNA Sequencing (scRNA-seq):-This technology allows the profiling of individual cells within a tissue sample, offering detailed insights into cell-specific molecular signatures.
-
Example: 10x Genomics offers platforms for single-cell RNA sequencing
-
Spatial Transcriptomics:- Spatial transcriptomics provides detailed information about how genes are regulated within specific regions of a tissue sample. It offers a new layer of insight into tissue heterogeneity
Example: Spatial Transcriptomics by 10x Genomics is a technology that maps gene expression patterns to tissue sections.
- Liquid biopsy: It is a non-invasive emerging technology that allows for the detection of tissue-specific biomarkers from blood, urine, or other bodily fluids. It is particularly useful for detecting cancer-related mutations, monitoring disease progression, and predicting therapeutic responses.
Example: Guardant360 by Guardant Health is a liquid biopsy test that detects genetic mutations in tumor DNA found in blood.
- Artificial Intelligence and Machine Learning (AI/ML): By processing vast amounts of tissue biomarker data, AI can accelerate the identification of clinically relevant biomarkers that can inform personalized treatment approaches.
Example: PathAI is a company using AI to help pathologists interpret tissue slides.
Adoption Trends:
-
High adoption in personalized medicines.
-
Increasing demand for clinical diagnostics.
-
Rising market growth and investments
Analyst Perspective
The Next Generation Tissue Biomarker Market is poised for strong growth, driven by the increasing adoption of precision medicine, advancements in multi-omics technologies, and expanding use of AI-enabled tissue analysis. Rising demand for companion diagnostics, targeted therapies, and biomarker-guided clinical decision-making is accelerating the integration of genomic, proteomic, and spatial biology platforms into routine diagnostics and drug development. Continuous innovation in digital pathology, next-generation sequencing, and multiplex tissue analysis is improving analytical accuracy and workflow efficiency. Furthermore, growing pharmaceutical investment in biomarker-driven clinical trials and expanding regulatory support for precision diagnostics are expected to sustain long-term market expansion across clinical and research applications.
Product Insights
The reagents and assays dominated the next generation tissue biomarkers industry with the largest revenue share of 55.3% in 2025. This segment is expected to witness rapid expansion due to its broad applicability in biopharmaceutical research. The increasing prevalence of cancer and other tissue-related diseases has accelerated the demand for faster and more precise diagnostic solutions, leading to the widespread adoption of reagents and assays. A key driving factor is the growing need for early disease detection and diagnostics, which has resulted in high demand for accurate, reliable, and rapid diagnostics, contributing to market growth. Advancements in technologies such as next-generation sequencing (NGS), CRISPR, and digital PCR have enhanced the capabilities and applications of reagents and assays. For example, in September 2024, QIAGEN reached a significant milestone with the introduction of 100 new assays for its QIAcuity digital PCR (dPCR) platform, designed to advance research in cancer, inherited genetic disorders, and infectious disease monitoring. QIAcuity is emerging as an essential tool for a wide variety of applications that demand precise and sensitive detection of genetic targets, fueling the advancement of new multiplexed assay. The newly introduced assays consist of dPCR LNA (locked nucleic acid) Mutation, dPCR CNV (copy number variation) Probe Assays, and dPCR Microbial DNA Detection Assays. The device will facilitate applications such as diagnosing infectious diseases and tracking cancer progression and treatment responses using less invasive liquid biopsy methods.
The software & AI segment is expected to witness significant growth over the forecast period, driven by the increasing adoption of digital pathology, artificial intelligence (AI), and machine learning (ML) for biomarker discovery and clinical decision support. AI-powered image analysis platforms enable automated tissue segmentation, biomarker quantification, and pattern recognition, improving diagnostic accuracy, reproducibility, and workflow efficiency while minimizing inter-observer variability. The integration of AI with spatial biology, multiplex imaging, and next-generation sequencing data further enhances biomarker identification and patient stratification. Growing demand for precision oncology, rising volumes of digital pathology data, and increasing investments in computational pathology solutions by healthcare providers and biopharmaceutical companies are expected to accelerate the adoption of software and AI platforms throughout the forecast period.
Type Insights
The genomic biomarker segment dominated the next generation tissue biomarkers market, capturing a 32.9% revenue share in 2025, owing to the rising demand for innovative therapies, growing competition for early disease detection, and significant R&D investments. For instance, in June 2024, BioAI and the Genomic Testing Cooperative announced a strategic collaboration to deliver AI-driven digital pathology solutions for clinical research and diagnostic applications. The collaboration’s goals include developing genomic biomarkers, screening algorithms, and assays, with plans to deploy them in clinical environments. In addition, in August 2024, Illumina, Inc, a global company in DNA sequencing and array-based technologies, announced that its TruSight Oncology (TSO) Comprehensive test received approval from the U.S. Food and Drug Administration (FDA) as an in vitro diagnostic (IVD) tool. The regulatory support, patient awareness, and bioinformatics advancements are all playing pivotal roles in accelerating the use of genomic biomarkers in clinical and research settings.
The metabolomic biomarkers segment is expected to grow at the fastest CAGR over the forecast period. Metabolomic biomarkers are specific metabolic changes or substances in the body that can be measured to identify disease states, predict disease risk, and monitor treatment responses. The growing interest in understanding the metabolic changes associated with prostate cancer is driving the segment’s growth. For example, in February 2025, Metabolon, Inc. announced new multiomics biomarker discovery features within its newly launched Integrated Bioinformatics Platform. These enhancements include multiomics predictive modeling, latent factor analysis, multiomics pathway analysis using public tools like Reactome, and advanced data visualization capabilities for multiomic datasets. Metabolomic biomarkers provide insights into disease mechanisms by analyzing small molecule profiles in biofluids such as urine, serum, and plasma. These markers support early detection and offer the potential for distinguishing aggressive from indolent cancer forms. Advances in analytical techniques like NMR spectroscopy and mass spectrometry have improved the detection and quantification of metabolic changes. Growing investments in precision oncology and increasing use of metabolomics in research and clinical trials are further accelerating the segment’s expansion.
Technology Insights
The next generation sequencing segment dominated the market with the largest share of 28.9% in 2025. Next Generation Sequencing (NGS) refers to the huge DNA sequencing methods that aid in genomic discovery. In February 2025, Roche introduced its groundbreaking sequencing by expansion (SBX) technology, creating a new category within next-generation sequencing. By combining SBX chemistry with an advanced sensor module, this technology enables ultra-fast, high-throughput sequencing that is versatile and scalable, suitable for a wide array of applications. This innovation establishes a new category in next-generation sequencing, offering substantial improvements over existing technologies. In addition, in May 2023, Pfizer and Thermo Fisher Scientific Inc announced a collaboration to expand local access to next-generation sequencing (NGS)-based testing for lung and breast cancer patients in over 30 countries across Latin America, Africa, the Middle East, and Asia, where advanced genomic testing has previously been scarce or inaccessible.
The spatial genomics biology segment is anticipated to grow at a significant CAGR of 15.97% from 2024 to 2033. Advancements in genome-editing tools, such as the CRISPR/Cas9 system, have facilitated the adoption of spatial genomics, driving market growth. For example, in February 2025, Bruker Corporation announced major innovations in spatial biology, including the Whole Transcriptome Panel (WTX), the PaintScape platform for direct 3D genome visualization, the CellScape PowerOMX software engine, and the GeoMx protein panel. PaintScape offers researchers an in-depth view of the 3D genome, enabling them to explore how structural variations in the genome influence gene expression and contribute to disease mechanisms. Furthermore, in January 2024, Bio-Techne Corporation revealed that Advanced Cell Diagnostics (ACD), a spatial biology brand under Bio-Techne, established a new benchmark with the introduction of a next-generation, protease-free RNAscope spatial multiomics workflow. This newly developed workflow is compatible with both manual and automated assays. By enabling the simultaneous imaging of RNA and protein biomarkers on the same tissue section, it offers an unparalleled single-cell perspective on disease pathology and therapeutic response. Moreover, the potential of spatial genetics analysis has increased investment in the development of new products in the healthcare sector, further propelling the market growth.
Application Insights
The oncology segment dominated the next generation tissue biomarkers industry with the largest revenue share of 59.4% in 2025. The growing demand for precision medicine drives segment growth and the development of targeted cancer therapies. Next-generation tissue biomarkers are essential for identifying cancer subtypes, predicting treatment responses, and monitoring therapeutic efficacy. In April 2024, Takara Bio USA, Inc., a wholly owned subsidiary of Takara Bio Inc., announced the launch of the Shasta Single-Cell System, an automated, high-throughput NGS solution. Takara Bio USA already provided instruments and NGS kits to early-access users. This comprehensive system enables researchers to extract a greater volume of genomic and transcriptomic data from far more cells than current technologies allow, all while reducing time and costs for research teams. The increasing prevalence of cancer, along with advancements in immuno-oncology, has heightened the need for innovative next generation tissue biomarkers.
The companion diagnostics segment is expected to grow at the fastest CAGR of 18.8% over the forecast period. The companion diagnostics market is experiencing significant product expansion, with new assays being developed for various cancer types, autoimmune diseases, and neurological disorders. Companies are focusing on multiplex diagnostics, which allow simultaneous testing of multiple biomarkers. Rising healthcare investments, improved regulatory frameworks, and growing awareness of precision medicine are driving expansion. For example, in January 2025, Foundation Medicine, Inc. announced that the U.S. Food and Drug Administration (FDA) approved FoundationOneCDx as a companion diagnostic for Day One Biopharmaceuticals' OJEMDA, a treatment for patients aged six months and older. FoundationOne CDx is the first and only companion diagnostic for OJEMDA. The FDA-approved test analyzes more than 300 cancer-related genes in a patient's tumor using a tissue sample. Advancements in biomarker discovery and targeted therapies further contribute to the expansion of this segment, enabling healthcare providers to tailor treatments to individual patient profiles, thereby improving outcomes and reducing adverse effects.
End-use Insights
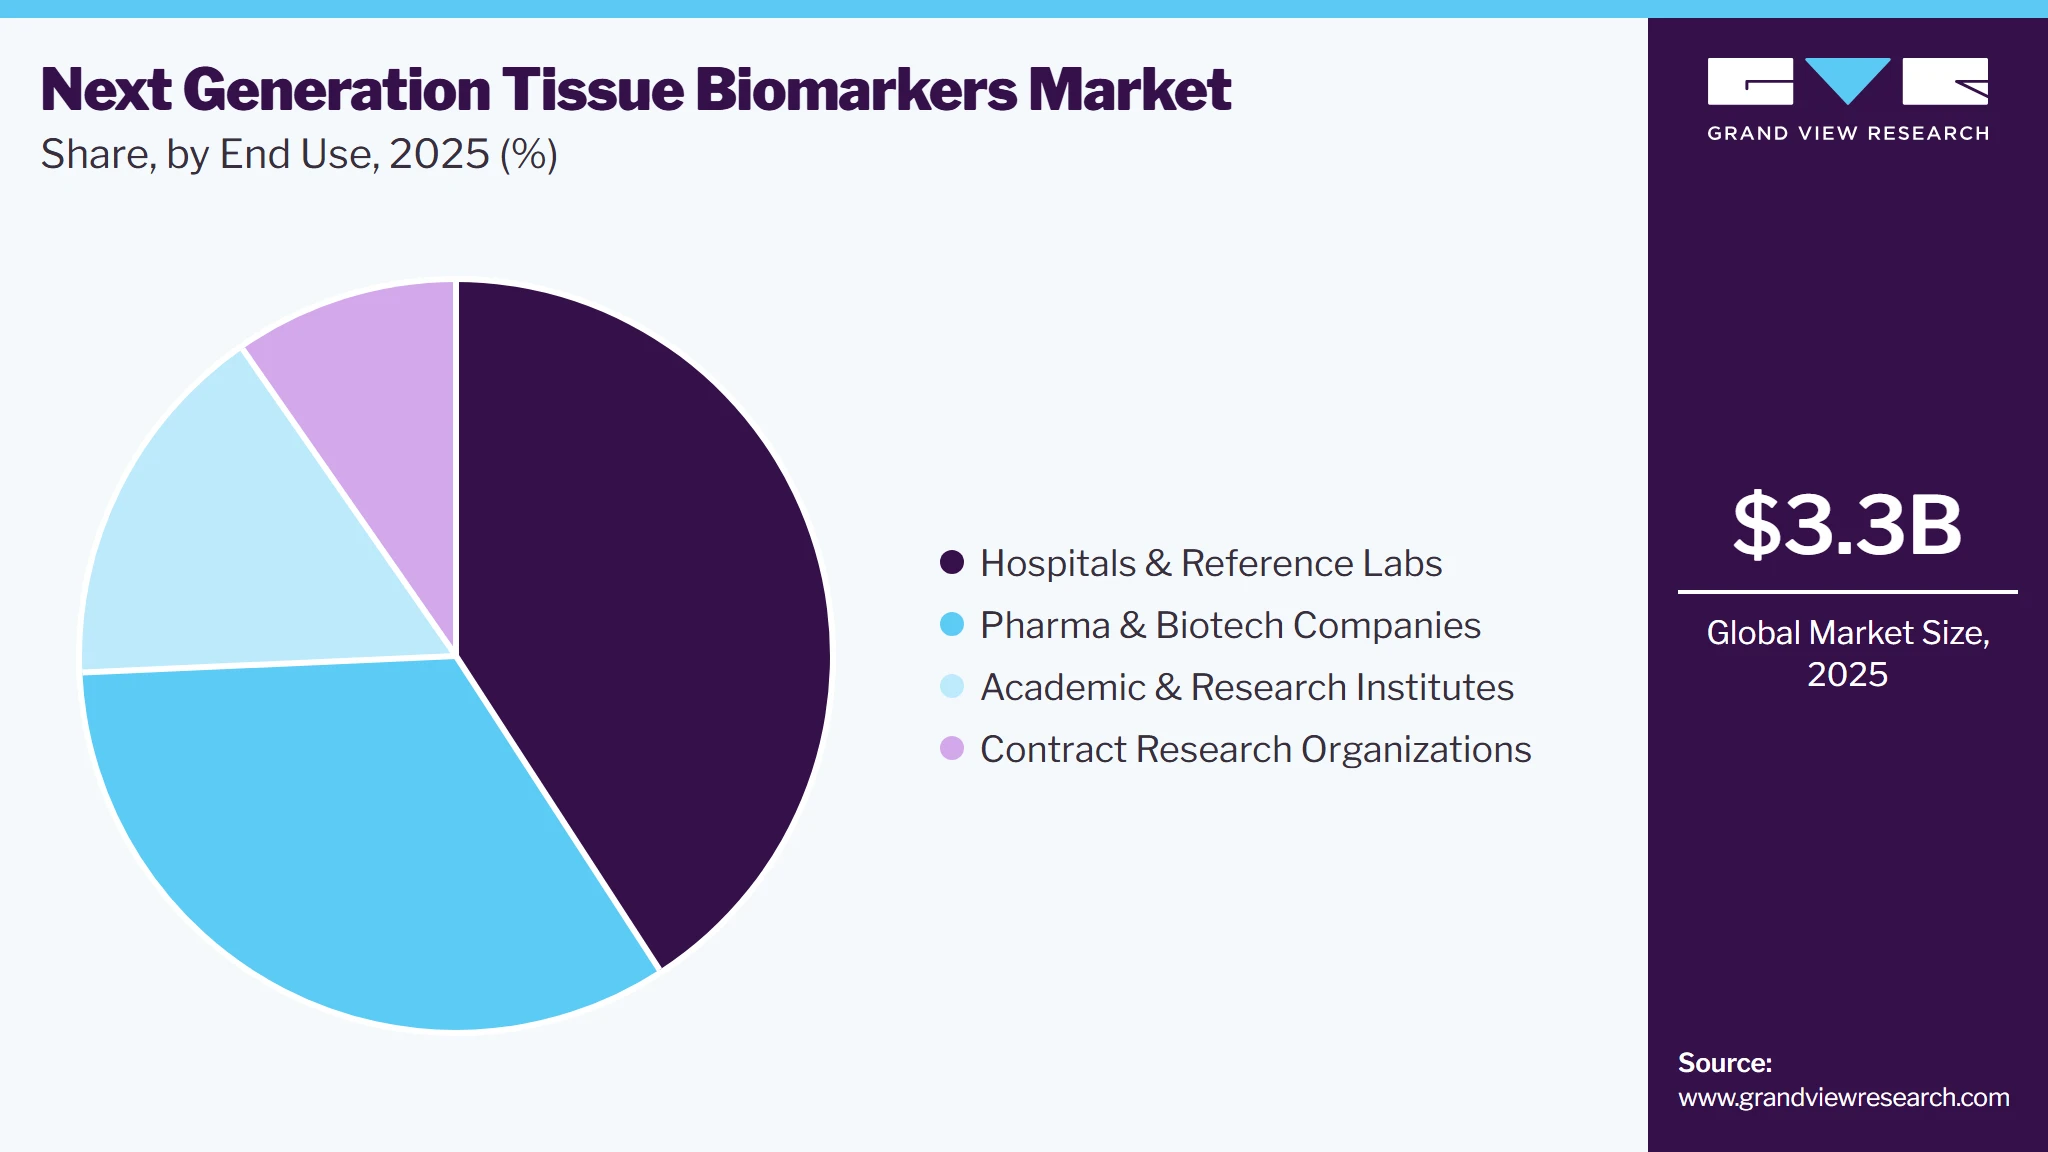
The hospitals & reference labs segment dominated the market with the largest share of 41.3% in 2025. Hospitals and reference labs are rapidly adopting next generation tissue biomarkers to enhance efficiency, accuracy, and accessibility. With the rising global burden of cancer and other tissue-related diseases, hospitals require faster, high-throughput solutions to manage increasing case volumes. In March 2024, Hackensack Meridian Health, a reference lab and the Genomic Testing Cooperative (GTC) in California, partnered to create a groundbreaking genomic profiling laboratory named Anthology Diagnostics. This lab aims to provide more personalized, precise, and real-time insights for cancer patients, oncologists, and hospitals. This reference lab will offer next-generation sequencing data for both DNA and RNA, which will aid clinicians in making treatment decisions and support researchers in discovering innovative biomarkers to enhance the understanding and management of blood cancers and solid tumors. For instance, in May 2023, NHS Borders launched its Rapid Cancer Diagnostic Service (RCDS), a significant step forward in early detection for patients presenting with vague or nonspecific symptoms. This initiative exemplifies the growing commitment among hospitals to integrate cutting-edge companion diagnostic solutions to improve patient outcomes. The evolution of hospital laboratories is pivotal in meeting changing patient needs, prompting healthcare facilities to broaden their service offerings. Additionally, hospitals are investing in advanced diagnostic platforms and forging collaborations with pharmaceutical companies to bolster their personalized cancer care capabilities.
 To learn more about this report, Download Free Sample Report
The contract research organizations segment is projected to grow at a CAGR of 18.4% during the forecast period. These organizations are heavily involved in research and development, focusing on targeted therapies that require precise biomarker identification. These organizations, which provide outsourced research services to the pharmaceutical, biotechnology, and medical device industries, are at the forefront of integrating advanced biomarker technologies into clinical trials and translational research.
Regional Insights
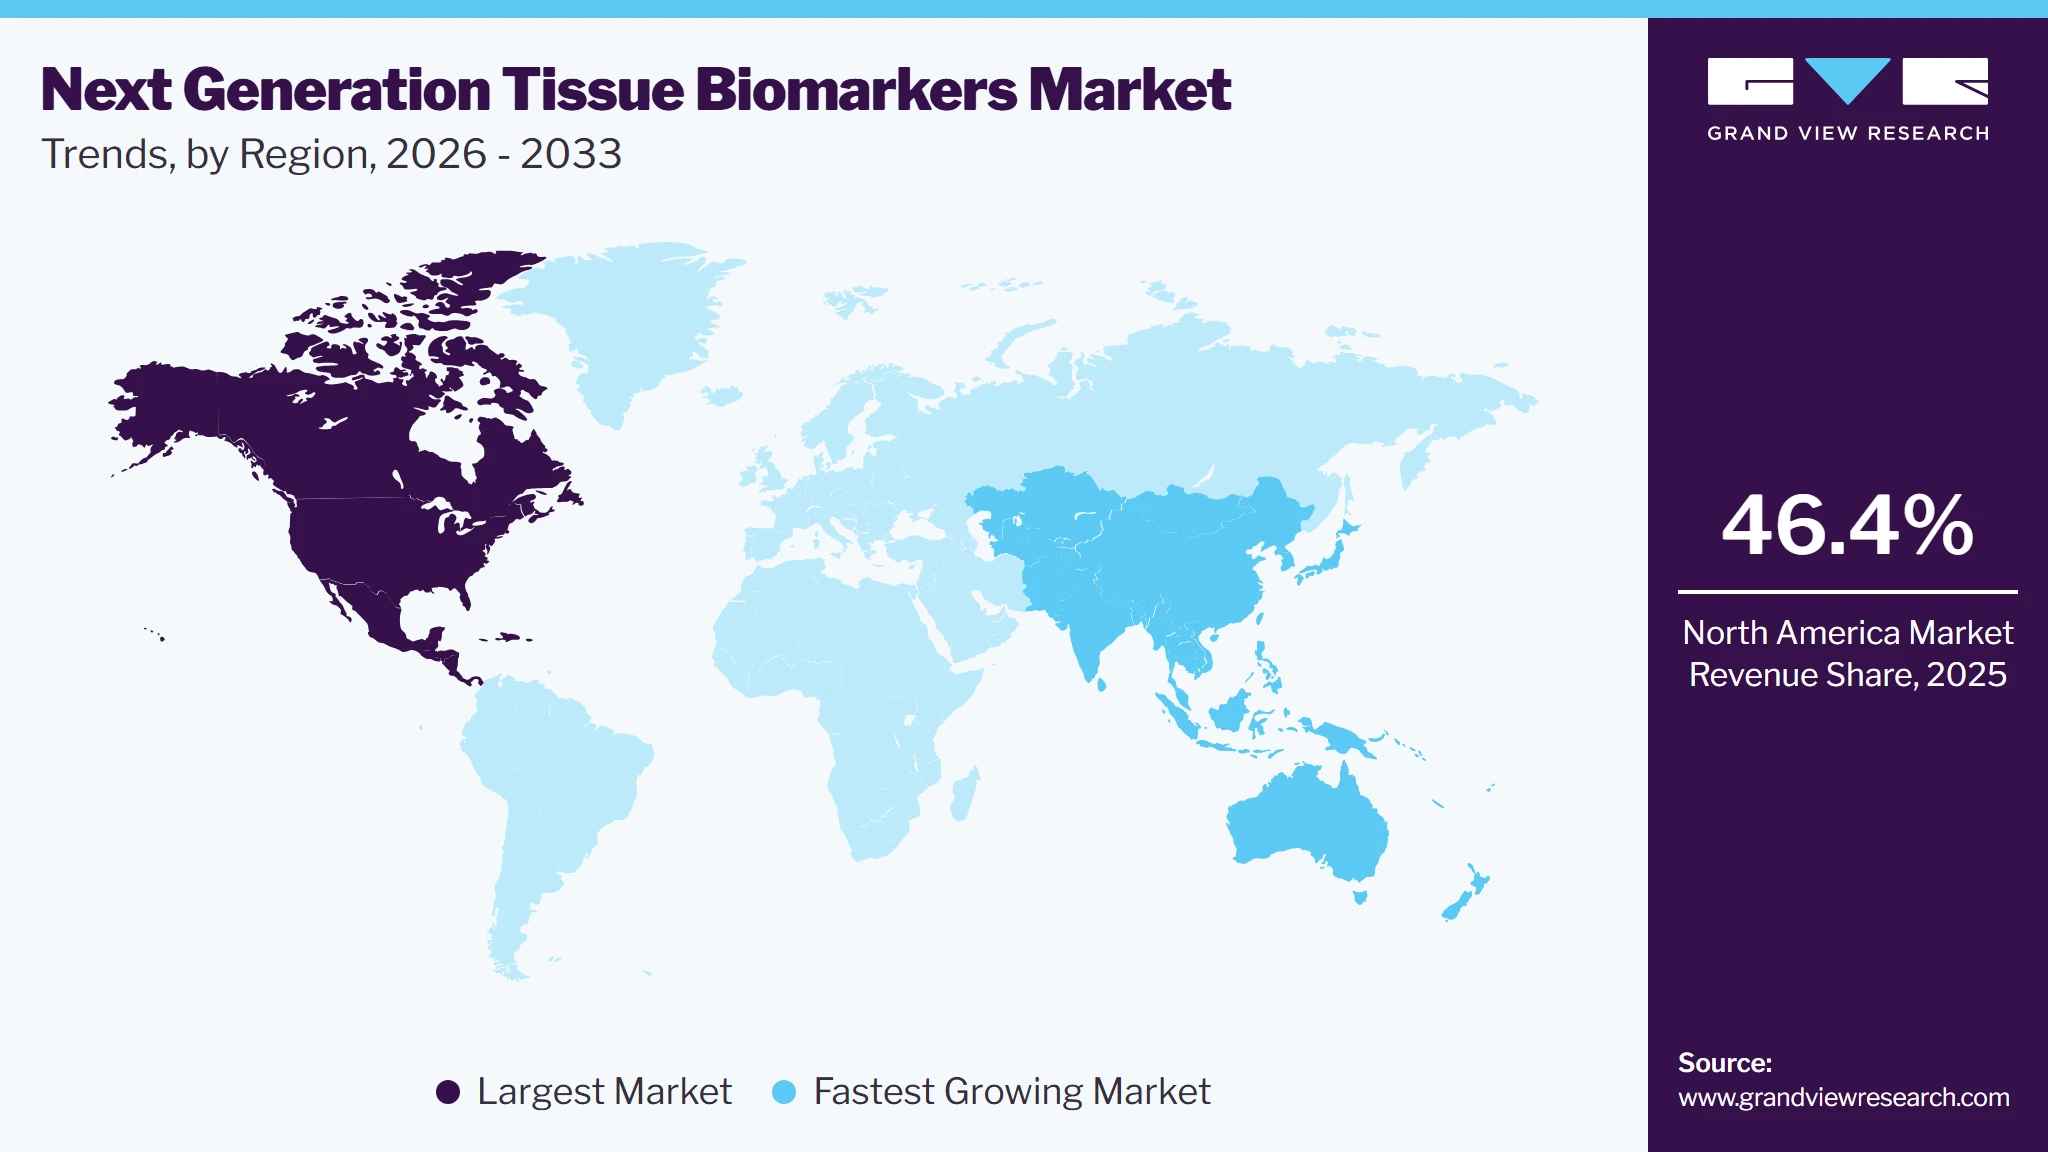
The North America next generation tissue biomarkers market accounted for the largest global share of 46.4% in 2025, primarily due to advanced healthcare infrastructure, substantial healthcare expenditure, and a robust regulatory framework that expedites approvals for next generation tissue biomarkers. Technological advancements in medical research and development are also contributing to market expansion. These innovations improve the quality and speed of diagnostic processes, making next generation tissue biomarkers more appealing to healthcare providers. Leading research institutions and biotech firms across the region are driving innovation through the development of cutting-edge diagnostic methods. Additionally, the growing prevalence of chronic diseases, including cancer, necessitates advanced technologies, further propelling the demand for next generation tissue biomarkers. In January 2025, Quanterix Corporation, a company in ultra-sensitive biomarker detection, and Akoya Biosciences, known for its spatial biology expertise, announced a definitive agreement in which Quanterix will acquire Akoya. The merger will create the first integrated solution for the ultra-sensitive detection of both blood- and tissue-based protein biomarkers, enabling early disease detection through non-invasive methods, even before symptoms manifest.
 To learn more about this report, Download Free Sample Report
U.S. Next Generation Tissue Biomarker Market Trends
The U.S. next generation tissue biomarker industry is projected to witness significant expansion, driven by the high prevalence of chronic diseases (including cancer) and the rapid adoption of advanced diagnostic solutions. Ongoing technological advancements, frequent FDA approvals for novel tests, and growing competition among biotechnology companies further bolster market growth prospects in the country.
Europe Next Generation Tissue Biomarkers Market Trends
The Europe next generation tissue biomarkers industry commands a notable global share, supported by developed economies such as Germany, Spain, the UK, France, and Italy. In November 2025, GenDx, a Eurobio Scientific Company, announced a partnership with OSE Immunotherapeutics, a French biotech company focused on developing first-in-class immuno-oncology treatments, to create and validate a companion diagnostic (CDx) test. This marks GenDx's first move into the companion diagnostic market, coinciding with the opening of their new offices at the Utrecht Science Park. These nations benefit from strong healthcare infrastructure and robust clinical research capabilities, spurring market growth. In the UK, advanced healthcare systems, strategic partnerships, and the introduction of innovative products drive adoption. Meanwhile, France’s focus on in-house genomic testing and Germany’s rising disease incidence also contribute to market expansion. Overall, these factors position Europe for sustained growth.
The UK next generation tissue biomarkers market is experiencing significant growth, driven by advanced healthcare infrastructure, strategic collaborations, and a strong focus on precision medicine. Increased investments in innovative technologies and strong regulatory support facilitate the development of cutting-edge tests for personalized therapies.
In September 2024, Biofidelity, a pioneer in cutting-edge genomic solutions, announced the opening of a new manufacturing facility in the UK, dedicated to the production of genomic assays. This new facility is dedicated to the production of high-quality genomic assays, reinforcing Biofidelity’s commitment to advancing genomic research and diagnostics. Partnerships between hospitals and reference labs boost research efforts, enhancing diagnostic accuracy and treatment outcomes. With an emphasis on early detection and care, the UK market is poised for continued expansion and greater integration of companion diagnostic solutions.
Asia Pacific Next Generation Tissue Biomarker Market Trends
The Asia Pacific next generation tissue biomarkers industry is anticipated to grow at the fastest CAGR of 17.3% over the forecast period. The market is experiencing significant growth, propelled by healthcare reforms, infrastructure enhancements, and a large patient pool. The region’s high burden of chronic diseases, including cancer, underscores the need for effective biomarker detection solutions. In September 2023, Agilent Technologies Inc. entered into a Research Collaboration Agreement (RCA) with the National Cancer Centre Singapore (NCCS) to advance translational cancer research focused on the genomic landscape of cancers prevalent in Asia. As part of the agreement, Agilent will supply the Magnis Next-Generation Sequencing (NGS) Preparation System to assist in studying specific details related to Asian cancer cohorts, where tissue samples from routine clinical care are often limited both locally and regionally. The collaboration aims to deliver consistent results by streamlining the analysis of multiple genes and complex genetic alterations from genomic DNA.
The next generation tissue biomarkers market in China is experiencing significant growth, driven by witnessing growth, driven by a rising prevalence of chronic diseases and an increasing focus on precision medicine. Significant investments in research and development, along with favorable government policies, have accelerated the adoption of advanced diagnostic technologies.
Latin America Next Generation Tissue Biomarker Market Trends
Latin America offers lucrative opportunities in the next generation tissue biomarkers space, driven by the rapid advancement of precision medicine and various R&D initiatives. Collaborations between pharmaceutical companies, diagnostic firms, and service providers are improving access to cutting-edge testing technologies. In September 2024, Biocare Medical, a company in immunohistochemistry (IHC) instrumentation and reagents, partnered with Ensigna Biosystems, a leading provider of advanced histopathology services, to announce a new strategic collaboration. This partnership aimed to expand and enhance innovative spatial biology applications, which are crucial for advancing biomedical research and the development of therapies. These partnerships between global innovators and local healthcare providers continue to reinforce Latin America’s standing as a promising region.
Middle East & Africa Next Generation Tissue Biomarker Market Trends
The Middle East and Africa (MEA) next generation tissue biomarker industry is expanding due to improving healthcare infrastructure, rising prevalence of chronic diseases, and growing adoption of AI-ML. However, many areas remain underpenetrated due to limited screening programs. Governments are increasingly focusing on expanding early detection efforts and promoting noninvasive diagnostic methods.
Key Next Generation Tissue Biomarkers Company Insights
New product launch, mergers and acquisitions, and collaborations are some of the major strategies adopted by the key market players to counter the stiff competition.
Key Next Generation Tissue Biomarkers Companies
The following key companies have been profiled for this study of the next generation tissue biomarkers market.
-
Roche Diagnostics / Ventana Medical Systems
-
Agilent Technologies / Dako
-
Leica Biosystems (Danaher Corporation)
-
Thermo Fisher Scientific
-
Illumina
-
Qiagen
-
NeoGenomics.
-
NanoString Technologies
-
Akoya Biosciences
-
Bio-Techne / ACD
-
Leica Biosystems / Danaher
-
Guardant Health
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Roche Diagnostics
- Focus on expanding tissue biomarker portfolios through multiplex assays, spatial biology platforms, AI-enabled digital pathology, and companion diagnostics. These companies emphasize strategic collaborations with pharmaceutical firms, investment in biomarker validation, regulatory approvals, and integrated precision oncology solutions to strengthen clinical adoption and global commercialization.
- Benefit from established global distribution networks, broad diagnostics portfolios, advanced R&D capabilities, strong regulatory expertise, extensive clinical validation, and long-standing relationships with hospitals, pathology laboratories, and pharmaceutical companies, enabling rapid commercialization and leadership in precision diagnostics.
- Face challenges related to high product development and validation costs, lengthy regulatory approval timelines, integration complexities across multiple diagnostic platforms, and increasing competition from emerging AI and spatial biology innovators. Maintaining leadership requires continuous investment in biomarker discovery, software, and clinical evidence generation.
Emerging Players: Akoya Biosciences
- Concentrate on developing innovative spatial biology technologies, AI-powered image analysis software, multiplex tissue profiling solutions, and cloud-based pathology platforms. These companies leverage strategic collaborations with academic institutions, pharmaceutical companies, and clinical research organizations to accelerate biomarker discovery and expand clinical applications in precision medicine.
- Possess greater agility in technology innovation, specialized expertise in spatial biology and computational pathology, faster product development cycles, and AI-driven analytics that improve biomarker detection, workflow automation, and personalized treatment selection. Their focused approach enables rapid differentiation in high-growth precision oncology markets.
- Operate with relatively limited commercial infrastructure, lower global brand recognition, constrained financial resources, and dependence on strategic partnerships for clinical validation, regulatory approvals, and market expansion. Limited installed customer bases and reimbursement coverage may also slow large-scale adoption compared with established diagnostics companies.
Recent Developments
-
In July 2026, CellCarta, a leading global contract research organization (CRO) laboratory serving the biopharmaceutical industry, launched its Global Digital Pathology and AI Consortium. The initiative brings together a curated network of innovators in digital pathology, artificial intelligence, and precision diagnostics to help biopharmaceutical companies accelerate biomarker discovery, patient stratification, clinical trial execution, and companion diagnostic development across oncology, autoimmune diseases, Alzheimer's disease, and other therapeutic areas.
-
In February 2025, Biofidelity, a provider of genomic solutions, unveiled details about the launch of Enspyre, an innovative target enrichment technology with a wide range of potential applications. A groundbreaking target enrichment technology that greatly improves next-generation sequencing (NGS) efficiency by selectively eliminating background DNA.
-
In February 2025, Alida Biosciences (AlidaBio), a company in epigenomic research tools, officially announced the full commercial launch of its EpiPlex platform. This groundbreaking platform is the first to simultaneously detect and quantify multiple RNA modifications through short-read sequencing, while also providing gene expression data.
Next Generation Tissue Biomarkers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.3 billion
Estimated market size in 2026
USD 3.6 billion
Projected market size by 2033
USD 6.0 billion
Growth rate
CAGR of 7.5% from 2026 to 2033
Actual data
2021 - 2024
Forecast period
2025 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, type, application, technology, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Sweden; Denmark; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Roche Diagnostics / Ventana Medical Systems; Agilent Technologies / Dako; Leica Biosystems (Danaher Corporation); Thermo Fisher Scientific; Illumina; Qiagen; NeoGenomics; NanoString Technologies; Akoya Biosciences; Bio-Techne / ACD; Leica Biosystems / Danaher
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Next Generation Tissue Biomarkers Market Report Segmentation
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global next generation tissue biomarkers market report based on product, application, technology, type, end use, and region:
-
Product Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Reagents & Assays
-
Instruments & Platforms
-
Software & AI
-
-
Type Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Genomic Biomarkers
-
Proteomic Biomarkers
-
Epigenetic Biomarkers
-
Transcriptomic Biomarkers
-
Metabolomic Biomarkers
-
-
Technology Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Immunohistochemistry
-
Next-Generation Sequencing (NGS)
-
Mass Spectrometry (MS)-based Proteomics
-
Spatial Biology Platforms
-
Digital Pathology & AI Analysis
-
Others
-
-
Application Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Oncology
-
Companion Diagnostics
-
Drug Discovery & Development
-
Neurology
-
Others
-
-
End-use Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Hospitals & Reference Labs
-
Pharma & Biotech Companies
-
Academic & Research Institutes
-
Contract Research Organizations (CROs)
-
-
Regional Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Research Methodology
The next generation tissue biomarkers market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each next generation tissue biomarkers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Reagents & Assays
Market value is primarily captured through recurring sales of antibodies, probes, staining kits, sequencing panels, biomarker assay kits, controls, and consumables required for tissue biomarker detection, validation, and routine laboratory testing.
Instruments & Platforms
Revenue flows from one-time procurement of tissue processing systems, sequencing instruments, mass spectrometers, digital pathology scanners, imaging platforms, and integrated analytical hardware supporting biomarker identification and clinical workflows.
Software & AI
Market income is driven by licensing, subscription, and implementation of bioinformatics software, AI-powered image analysis, data interpretation platforms, workflow management tools, and clinical decision-support solutions for tissue biomarker analysis.
Segment - Type
Revenue capture definition
Genomic Biomarkers
Market value is derived from tissue-based biomarkers detecting DNA mutations, copy number variations, structural alterations, and genetic signatures that support disease diagnosis, therapy selection, and precision medicine applications.
Proteomic Biomarkers
Commercial demand arises from tissue biomarkers measuring protein expression, abundance, localization, and post-translational modifications using immunoassays and proteomic technologies for disease characterization and therapeutic guidance.
Epigenetic Biomarkers
Market contribution comes from biomarkers evaluating DNA methylation, histone modifications, chromatin organization, and other epigenetic alterations in tissue samples for disease detection, prognosis, and treatment response assessment.
Transcriptomic Biomarkers
Revenue capture is supported by tissue biomarkers measuring messenger RNA, non-coding RNA, and gene expression profiles that enable disease classification, molecular subtyping, and therapeutic decision-making.
Metabolomic Biomarkers
Market expansion is fueled by tissue biomarkers analyzing metabolites and metabolic pathways associated with disease progression, treatment response, and cellular activity using advanced analytical technologies.
Segment -Technology
Revenue capture definition
Immunohistochemistry
Market value is generated through tissue staining workflows utilizing antigen-antibody interactions for protein biomarker visualization, including antibodies, staining reagents, automated platforms, and associated analytical solutions.
Next-Generation Sequencing (NGS)
Revenue streams originate from sequencing-based tissue biomarker analysis covering library preparation, sequencing platforms, targeted panels, bioinformatics software, and data interpretation supporting comprehensive genomic profiling.
Mass Spectrometry (MS)-based Proteomics
Market demand is supported by protein identification and quantification using mass spectrometry instruments, sample preparation reagents, analytical software, and specialized proteomic workflows for tissue biomarker discovery.
Spatial Biology Platforms
Commercial value is captured through technologies preserving spatial tissue architecture while analyzing molecular expression, including imaging systems, multiplex assays, reagents, and spatial data analysis software.
Digital Pathology & AI Analysis
Revenue is primarily captured through digital slide scanners, image management software, AI-based pathology algorithms, cloud platforms, and computational tools enabling automated tissue biomarker interpretation.
Others
Market contribution includes emerging tissue biomarker technologies such as multiplex imaging, molecular imaging, single-cell analysis, and novel analytical platforms not classified under established technology segments.
Segment - Application
Revenue capture definition
Oncology
Market value is driven by tissue biomarker testing supporting cancer diagnosis, molecular profiling, prognosis, treatment selection, recurrence monitoring, and precision oncology across solid tumors and hematological malignancies.
Companion Diagnostics
Revenue capture is supported by tissue biomarker assays specifically developed to identify patients eligible for targeted therapies, ensuring safe and effective therapeutic selection alongside approved pharmaceutical products.
Drug Discovery & Development
Commercial demand arises from tissue biomarker applications used in target identification, biomarker validation, clinical trial stratification, pharmacodynamic assessment, and therapeutic response evaluation during drug development.
Neurology
Market value is derived from tissue biomarker applications supporting diagnosis, disease characterization, and therapeutic research for neurological disorders using molecular and cellular profiling techniques.
Others
Revenue flows from tissue biomarker applications across infectious diseases, autoimmune disorders, cardiovascular diseases, rare diseases, and additional clinical or research areas beyond the defined application categories.
Segment - End Use
Revenue capture definition
Hospitals & Reference Labs
Market value is captured through routine clinical tissue biomarker testing, pathology services, diagnostic workflows, and high-volume patient sample processing performed within hospitals and specialized reference laboratories.
Pharma & Biotech Companies
Commercial demand originates from tissue biomarker utilization in pharmaceutical and biotechnology research, companion diagnostic development, clinical trials, translational research, and precision medicine programs.
Academic & Research Institutes
Market contribution comes from procurement of tissue biomarker technologies for basic research, translational studies, biomarker discovery, validation projects, and government- or institution-funded scientific investigations.
Contract Research Organizations (CROs)
Revenue is primarily captured through outsourced tissue biomarker services including assay development, biomarker validation, laboratory testing, clinical trial support, and analytical services provided to life science companies.
Estimation Model
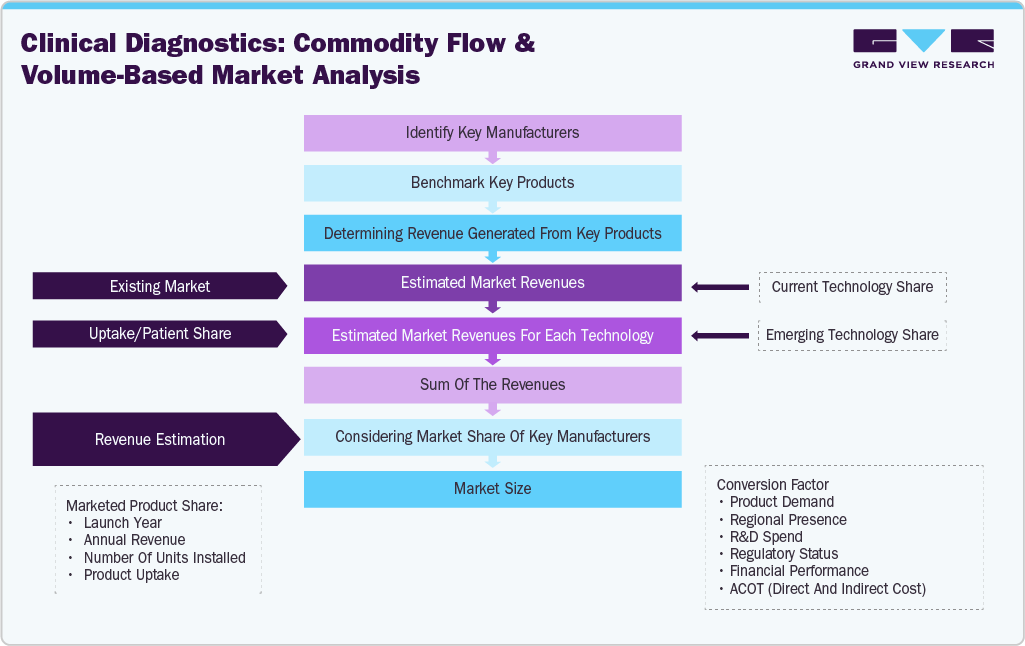
The market size was estimated by identifying leading manufacturers of next generation tissue biomarker products, benchmarking their portfolios, and analyzing revenue generated from key biomarker assays, instruments, and companion diagnostic solutions. These revenues were further validated using technology-wise adoption rates, patient uptake, and existing market trends, followed by aggregation and adjustment based on the market share of key manufacturers to derive the overall market size.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Next Generation Tissue Biomarkers Market Opportunity and Commercialization Strategy Assessment
Developed a comprehensive assessment of the global next generation tissue biomarkers market, evaluating market size, growth opportunities, competitive landscape, reimbursement environment, regulatory framework, technology advancements, and commercialization strategies across oncology, immunology, neurology, and companion diagnostics applications.
Enables diagnostic companies, pharmaceutical firms, biotechnology companies, and investors to identify high-growth market segments, optimize commercialization strategies, prioritize geographic expansion, and capitalize on emerging opportunities in precision medicine and biomarker-driven drug development.
Precision Diagnostics and Tissue Biomarker Clinical Adoption Analysis
Delivered an in-depth analysis of next generation tissue biomarker adoption across clinical and research settings, including biomarker utilization trends, pathology workflows, digital pathology integration, companion diagnostic adoption, physician acceptance, treatment decision pathways, and patient stratification strategies across major disease indications.
Provides actionable insights to improve market access strategies, strengthen clinical adoption, identify unmet diagnostic needs, optimize biomarker development programs, and align product portfolios with evolving precision oncology and personalized medicine trends.
Frequently Asked Questions About This Report
The Reagents & Assays segment dominated the global prostate cancer biomarker market and accounted for the largest revenue share of 55.3% in 2025.
Some key players operating in the next generation tissue biomarkers market include Roche Diagnostics / Ventana Medical Systems, Agilent Technologies / Dako, Thermo Fisher Scientific, Illumina, Qiagen, NeoGenomics, NanoString Technologies, Akoya Biosciences, Bio-Techne / ACD and Leica Biosystems / Danaher.
Next-generation tissue biomarkers are essential for advancing personalized medicine and play a crucial role in identifying disease conditions as in cardiovascular, chronic diseases, cancer, and several infections. Key driving factors such as increasing prevalence of chronic diseases, technological advancements in biomarker detection techniques and rising demand for personalized medicine are responsible for market growth.
North America dominated the tissue biomarkers market with the largest revenue share of 46.4% in 2025.
Asia Pacific is anticipated to witness the fastest growth of 17.3% CAGR over the forecast period. The Asia-Pacific next generation tissue biomarkers market is experiencing significant growth, propelled by healthcare reforms, infrastructure enhancements, and a large patient pool.
Based on type, the genomic biomarkers segment led the market with the largest revenue share of 32.9% in 2025.
The market for next-generation tissue biomarkers in disease diagnosis is experiencing significant growth, driven by advancements in precision medicine, digital pathology, and biomarker discovery technologies.
The global next generation tissue biomarkers market size was valued at USD 3.3 billion in 2025 and is estimated at USD 3.6 billion for 2026.
The global next generation tissue biomarkers market is expected to grow at a CAGR of 7.5% from 2026 to 2033, reaching USD 6.0 billion by 2033.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


