
- Home
- »
- Plastics, Polymers & Resins
- »
-
North America Rigid PET Bottles And Jars Market Report 2033GVR Report cover

North America Rigid PET Bottles And Jars Market (2026 - 2033)
Size, Share & Trends Analysis Report By Resin Type (Virgin PET (Polyethylene Terephthalate), Recycled PET (rPET), Hybrid PET/rPET), By Capacity, By Application, By Country, And Segment Forecasts
Market Size, 2025
$8.5BMarket Estimate, 2026
$8.8BMarket Forecast, 2033
$12.0BCAGR, 2026–2033
4.5%North America Rigid PET Bottles And Jars Market Summary
The North America rigid PET bottles & jars market size was valued at USD 8.5 billion in 2025 and is projected to grow from USD 8.8 billion in 2026 to USD 12.0 billion by 2033, at a CAGR of 4.5% from 2026 to 2033. Rigid PET bottles & jars are commonly used in beverage packaging, bottled water, carbonated soft drinks, juices, dairy products, edible oils, sauces, and condiments, as well as in personal care, household care, pharmaceutical, and nutraceutical applications. Their widespread adoption is attributed to their lightweight nature, high clarity, durability, impact resistance, and recyclability, which help manufacturers enhance product visibility, reduce transportation costs, and meet evolving sustainability requirements across diverse end-use industries.
Key Market Trends & Insights
- The U.S. dominated the North America rigid PET bottles & jars market with the largest revenue share of 78.6% in 2025.
- The Mexico rigid PET bottles & jars market is expected to grow at the fastest CAGR of 5.3% from 2026 to 2033.
- By resin type, the recycled PET (rPET) segment is expected to grow at a CAGR of 5.3% from 2026 to 2033 in terms of revenue.
- By capacity, the 250-500 ml segment is expected to grow at a CAGR of 5.0% from 2026 to 2033 in terms of revenue.
- By application, the pharmaceuticals segment is expected to grow at a CAGR of 5.1% from 2026 to 2033 in terms of revenue.
Market Size & Forecast
- Market size in 2025: USD 8.5 Billion
- Estimated market size in 2026: USD 8.8 Billion
- Projected market size by 2033: USD 12.0 Billion
- CAGR (2026-2033): 4.5%
Prism AI by Grand View Research Free to tryAsk a question about the north america rigid PET bottles and jars marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Virgin PET (Polyethylene Terephthalate) accounted for a significant share of the North America rigid PET bottles & jars market due to its superior clarity, strength, lightweight properties, and excellent barrier performance. The material remains widely preferred for bottled water, carbonated beverages, food products, personal care items, and household products where appearance, durability, and shelf life are critical. Continued growth in packaged beverage consumption, coupled with manufacturers' need for cost-effective and high-performance packaging solutions, continues to drive demand for virgin PET containers across the region.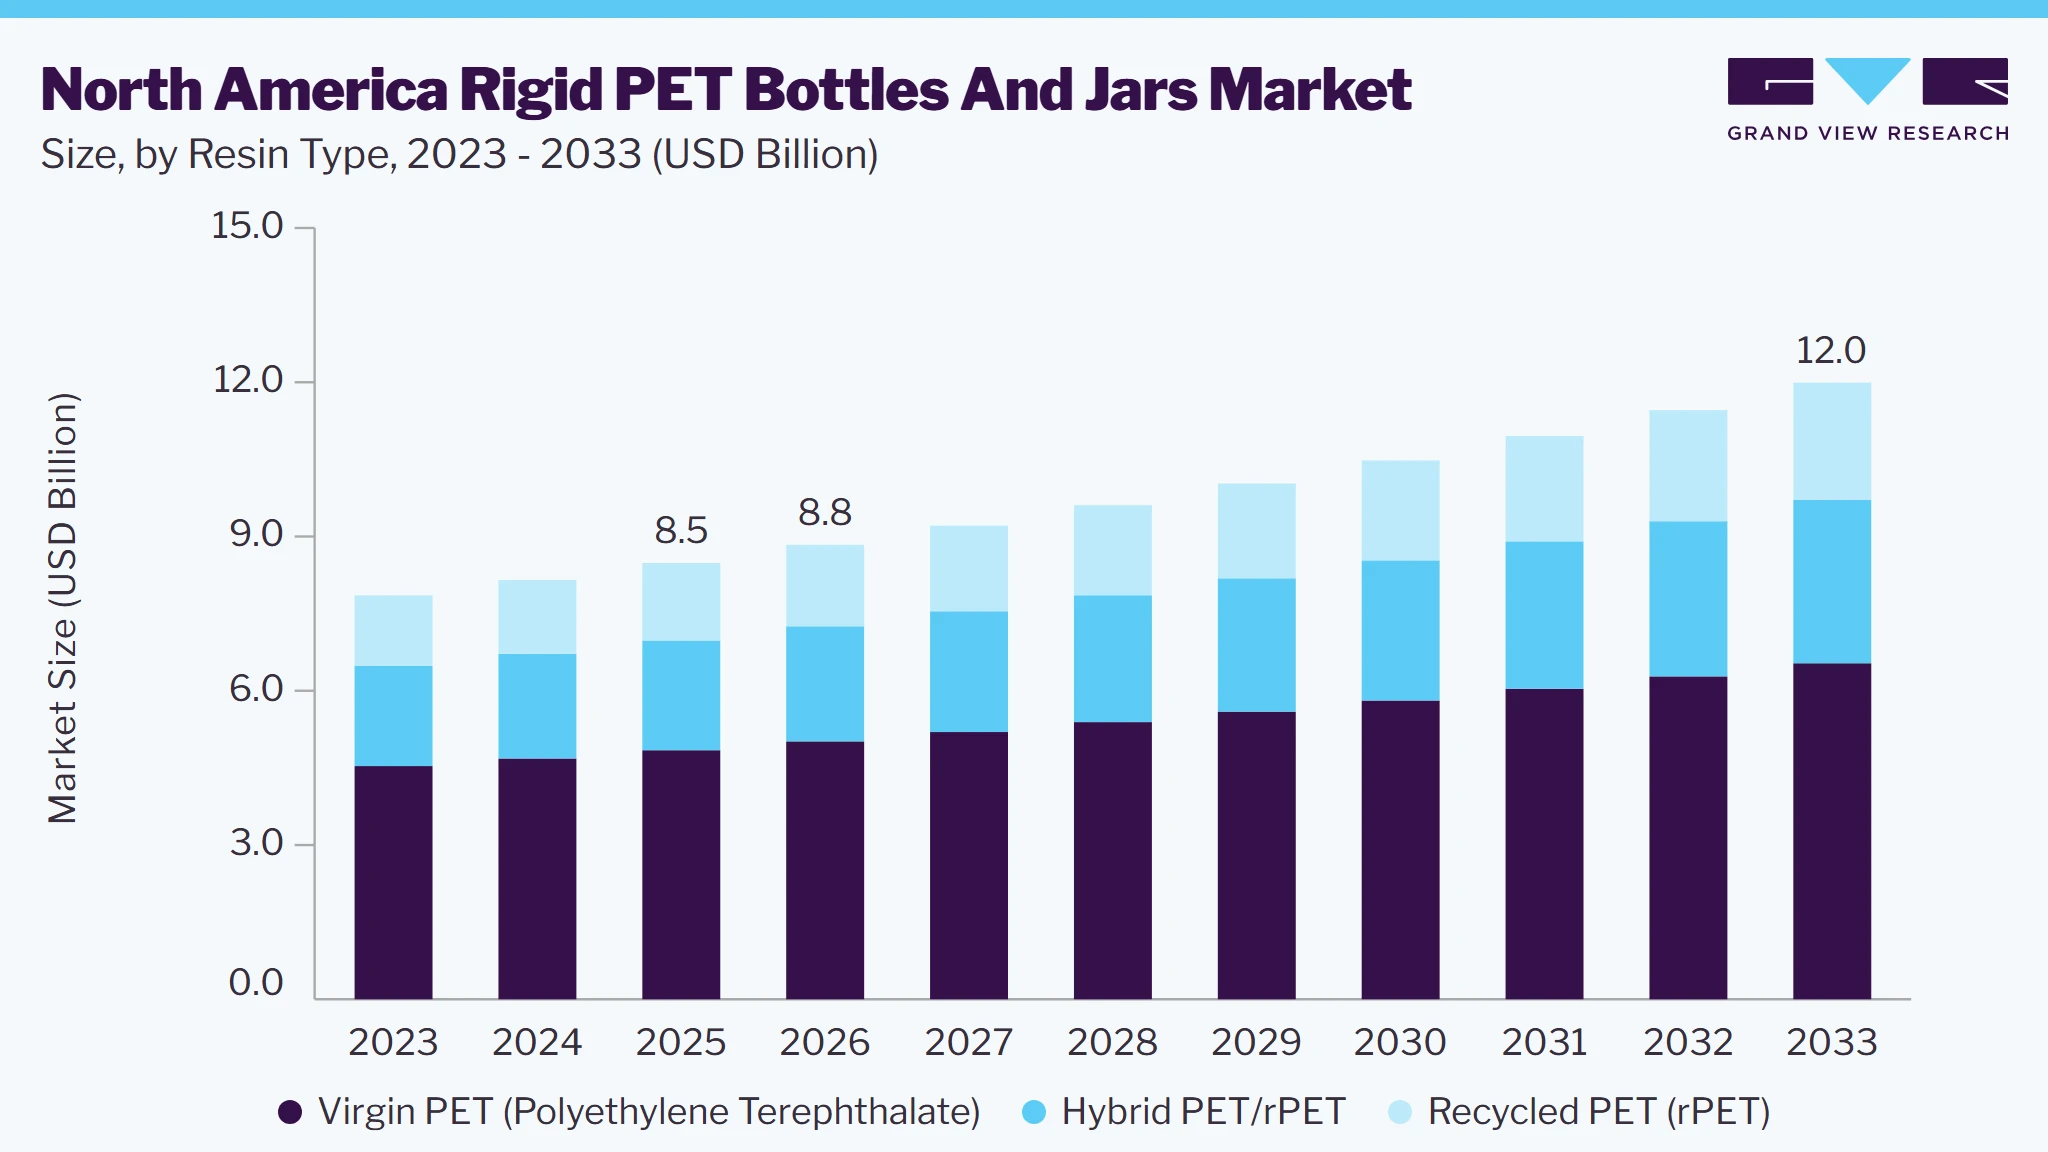 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Recycled PET (rPET) and Hybrid PET/rPET segments are experiencing strong growth, supported by increasing sustainability commitments from brand owners and tightening regulatory focus on circular packaging. Food and beverage companies are expanding the use of recycled content in bottles and jars to reduce virgin plastic consumption and meet environmental targets. Hybrid PET/rPET packaging is gaining traction as manufacturers seek to balance sustainability goals with performance, product safety, and supply chain reliability. Growing investments in recycling infrastructure and rising consumer preference for environmentally responsible packaging solutions are further accelerating the adoption of these resin types across North America.
Market Dynamics
The growing demand for packaged beverages and bottled water is a major driver of the North America rigid PET bottles & jars market. PET bottles are widely used for bottled water, carbonated soft drinks, sports drinks, and ready-to-drink beverages due to their lightweight, durable, and cost-effective nature. Rising consumer preference for convenient hydration products continues to increase bottled water consumption across the region. According to the International Bottled Water Association, bottled water remained the largest packaged beverage category in the U.S. in 2025, supporting sustained demand for PET bottle packaging. The increasing production and distribution of packaged beverages is consequently driving the consumption of rigid PET bottles and jars across North America.
Recent industry developments further demonstrate this trend. In June 2025, Perfect Hydration, a U.S.-based bottled water manufacturer, announced the addition of more than 3,000 new distribution points across North America to expand product availability through retail channels. The expansion reflects growing consumer demand for bottled water and packaged hydration products, which are predominantly packaged in PET bottles. As beverage manufacturers continue to expand production capacity, product portfolios, and distribution networks, demand for rigid PET bottles and jars is expected to remain strong throughout the forecast period.
Raw material price volatility is a key restraint for the North America rigid PET bottles & jars market. Prices of virgin PET resin are influenced by fluctuations in crude oil-derived feedstocks such as purified terephthalic acid (PTA) and monoethylene glycol (MEG), while increasing demand for food-grade recycled PET (rPET) can lead to supply shortages and higher material costs. These price uncertainties create challenges for bottle and jar manufacturers in managing production expenses, maintaining profit margins, and establishing long-term pricing agreements with customers. As a result, volatility in raw material costs can negatively impact operational efficiency and investment decisions across the PET packaging value chain.
The increasing adoption of recycled PET (rPET) and circular packaging solutions presents a significant opportunity for the North America rigid PET bottles & jars market. Growing sustainability commitments from beverage, food, personal care, and household product manufacturers are driving demand for packaging with higher recycled content. In response, PET packaging producers are investing in advanced recycling technologies, expanding food-grade rPET production capacity, and developing bottles and jars designed for improved recyclability. As regulatory requirements and corporate sustainability targets continue to encourage the use of recycled materials, the transition toward circular packaging is expected to create substantial growth opportunities for rigid PET bottle and jar manufacturers across North America.
Market Concentration & Characteristics
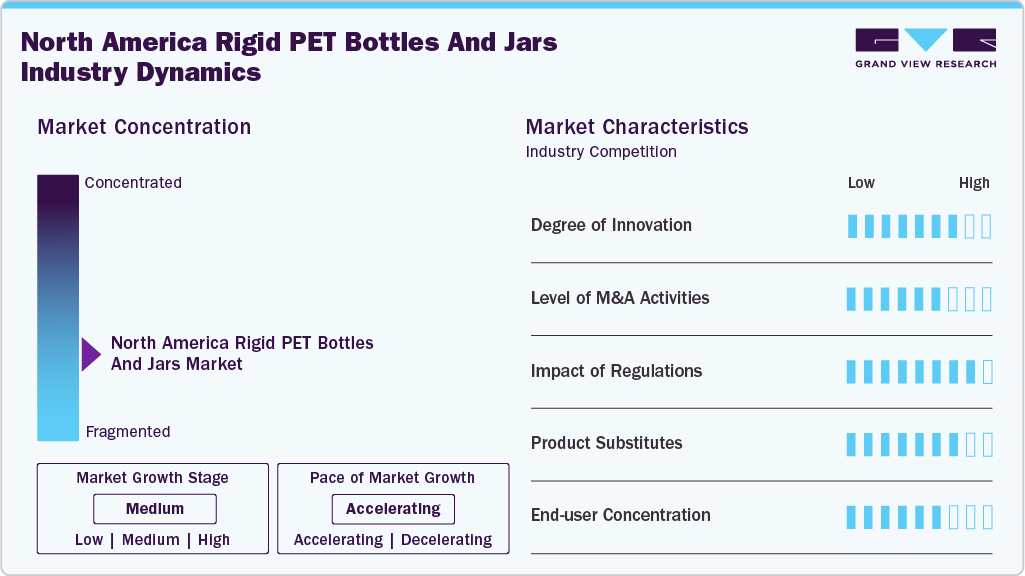
The market is characterized by strong demand from the food & beverage, personal care, household products, and pharmaceutical industries, where manufacturers increasingly prioritize lightweight, durable, and recyclable packaging solutions. Sustainability initiatives and the growing adoption of recycled PET (rPET) have emerged as key market drivers, supported by corporate commitments to circular packaging and evolving regulatory requirements. Demand for lightweight packaging that reduces transportation costs and carbon emissions further encourages the adoption of PET bottles and jars across multiple end-use sectors. Industry participants are investing in advanced bottle designs, lightweighting technologies, and greater integration of recycled content to strengthen their competitive positions.
 To learn more about this report, Download Free Sample Report
Recent developments highlight the North America rigid PET bottles & jars industry's focus on sustainability-led innovation. In October 2025, Amcor plc reported achieving its target of incorporating 10% post-consumer recycled plastic across its packaging portfolio and noted that 96% of its rigid packaging portfolio was designed for recyclability, reflecting increasing demand for circular PET packaging solutions. Moreover, Amcor’s 2025 “Bottles of the Year” program showcased innovative rigid bottle designs developed to address evolving consumer preferences and sustainability requirements. Meanwhile, the broader PET packaging industry continued to advance high-recycled-content packaging formats, as demonstrated by the rollout of 100% recycled PET canisters and jars in North America, reinforcing the growing market emphasis on recycled-content packaging and resource efficiency.
Resin Type Insights
The virgin PET (polyethylene terephthalate) segment dominated the market in 2025, accounting for 57.1% of the total market share. The segment's leadership is primarily attributed to its superior clarity, strength, lightweight properties, and consistent performance in food-contact and beverage packaging applications. Virgin PET continues to be widely preferred by manufacturers in the beverage, personal care, pharmaceutical, and household product sectors due to its ability to meet stringent quality and safety standards. Additionally, its reliable supply availability and compatibility with high-speed production processes support its continued adoption across large-scale packaging operations.
The recycled PET (rPET) segment is gaining traction in the North America rigid PET bottles & jars industry, due to increasing sustainability commitments from consumer goods companies, growing regulatory emphasis on recycled-content packaging, and rising investments in plastic recycling infrastructure across North America. Brand owners are increasingly incorporating rPET into bottles and jars to reduce virgin plastic consumption, lower carbon footprints, and align with circular economy objectives. Furthermore, advancements in recycling technologies and improved availability of food-grade rPET have enhanced its suitability for packaging applications, encouraging broader adoption across beverage, food, personal care, and household product industries.
Capacity Insights
The 500-1000 ml segment dominated the North America rigid PET bottles & jars market in 2025, accounting for 34.7% of the total revenue share. The segment's dominance is largely driven by its widespread use in bottled beverages, edible oils, household cleaning products, and personal care applications, where this capacity range offers an optimal balance between product volume, convenience, and cost efficiency. Manufacturers and brand owners favor 500-1000 ml containers due to their compatibility with high-volume retail distribution channels and consumer preference for family-sized and value-oriented packaging formats. Moreover, the segment benefits from extensive adoption across both food-grade and non-food packaging applications.
The 250-500 ml segment is gaining traction in the North America rigid PET bottles & jars industry due to increasing consumer demand for portable, single-serve, and on-the-go packaging solutions. Growing consumption of ready-to-drink beverages, functional drinks, personal care products, and travel-sized household items is supporting demand for smaller PET bottles and jars within this capacity range. Furthermore, changing lifestyle patterns, rising preference for portion-controlled packaging, and the expansion of convenience retail channels are encouraging manufacturers to introduce compact packaging formats that enhance product accessibility and consumer convenience.
Application Insights
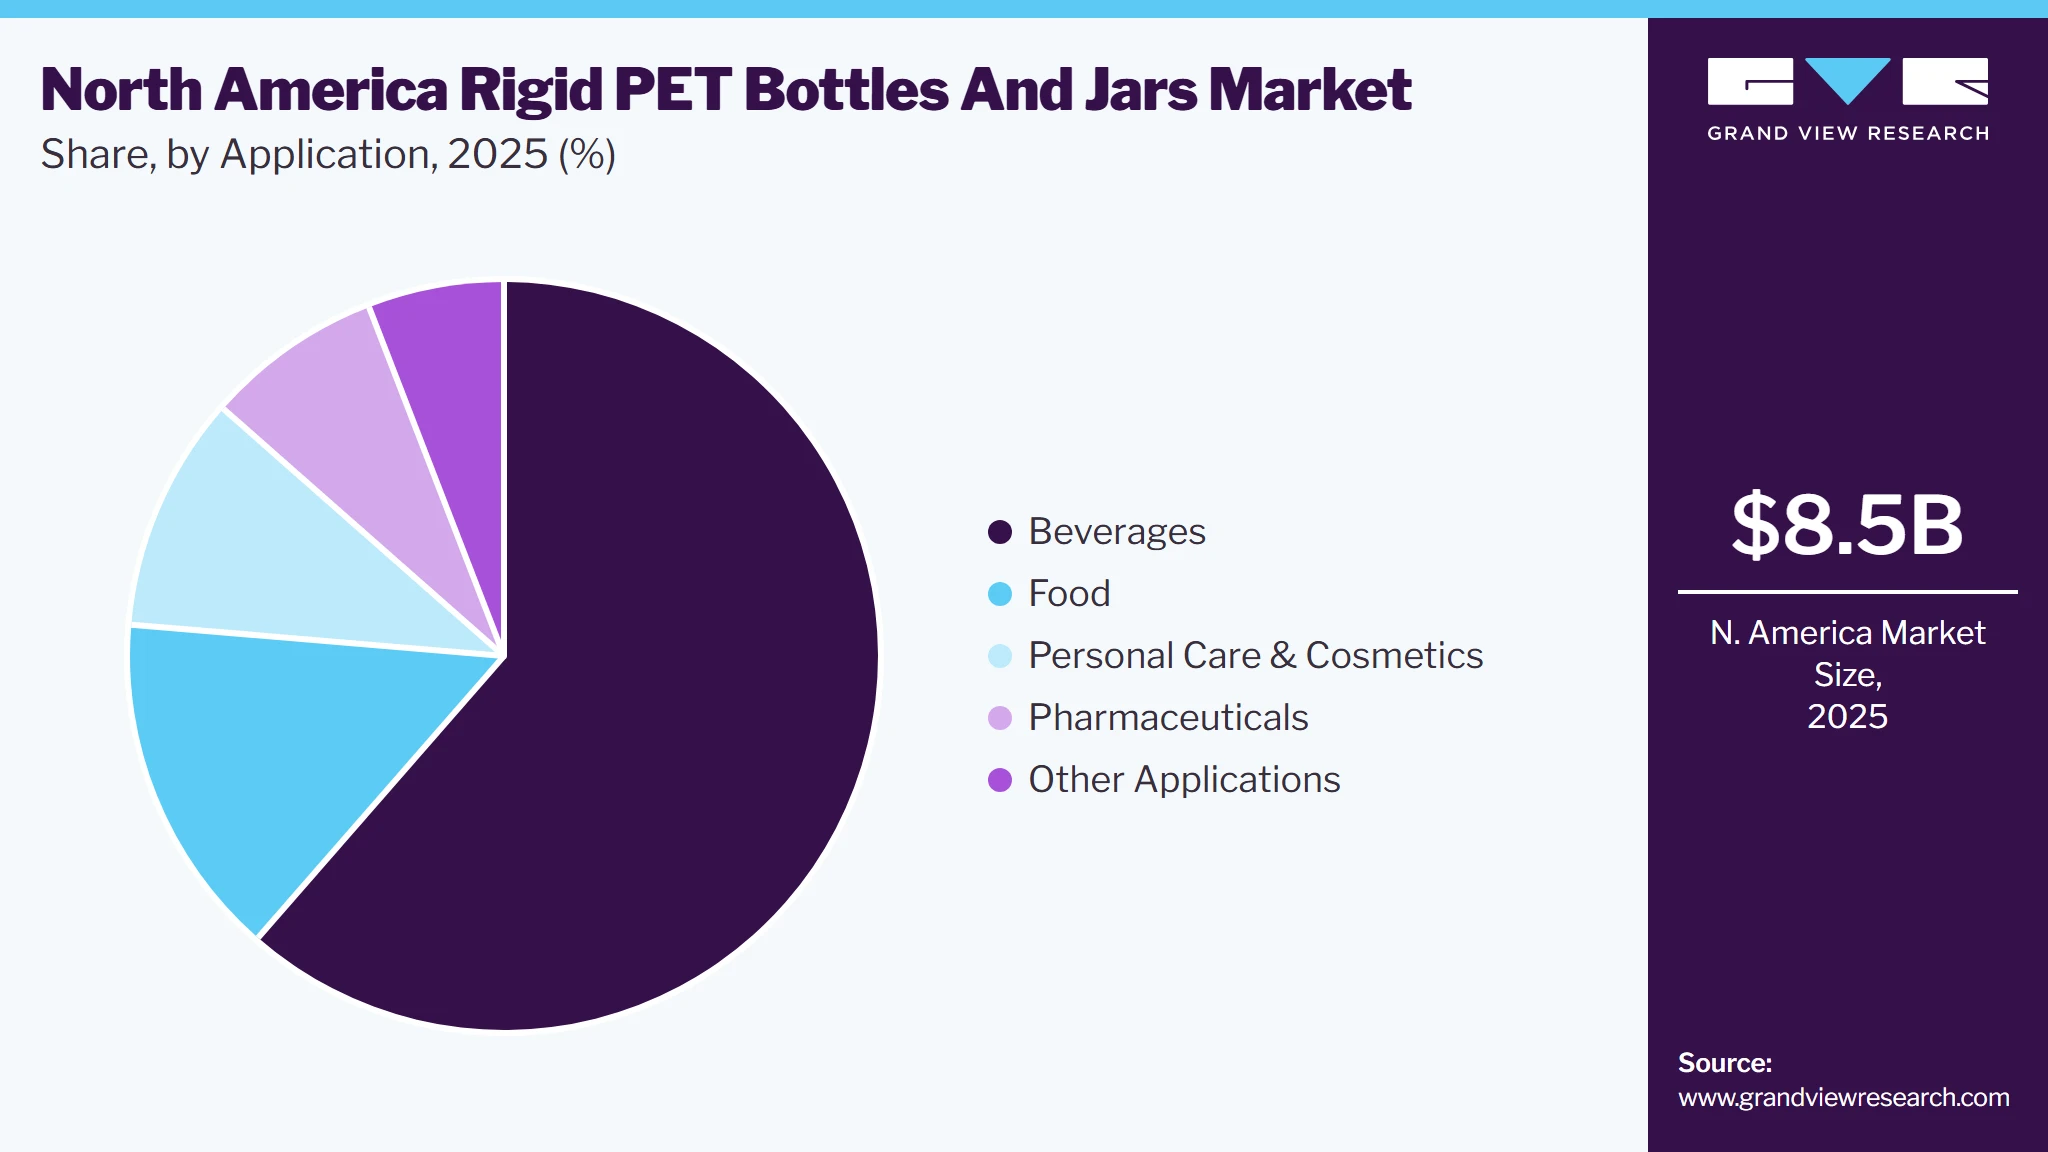
The beverages segment dominated the market in 2025, accounting for 61.4% of the total share. The segment's leading position is driven by the extensive use of PET packaging for bottled water, carbonated soft drinks, juices, sports drinks, and ready-to-drink beverages. PET bottles offer a combination of lightweight properties, durability, clarity, and cost-effectiveness, making them highly suitable for large-scale beverage production and distribution. Furthermore, growing consumer demand for convenient and portable beverage packaging, coupled with the beverage industry's focus on packaging efficiency and recyclability, continues to support strong demand for rigid PET bottles.
 To learn more about this report, Download Free Sample Report
The pharmaceuticals segment is gaining traction in the North America rigid PET bottles & jars industry, driven by the rising demand for secure, lightweight, and chemically resistant packaging solutions for medicines, nutraceuticals, and healthcare products. Increasing pharmaceutical production, an aging population, and growing consumption of over-the-counter medications and dietary supplements are contributing to higher demand for PET bottles and jars. Furthermore, PET packaging offers advantages such as product visibility, impact resistance, moisture protection, and compliance with stringent packaging standards, making it an increasingly preferred option for pharmaceutical manufacturers seeking reliable and cost-efficient packaging solutions.
Country Insights
U.S. Rigid PET Bottles And Jars Market Trends
The U.S. dominated the North America rigid PET bottles & jars market in 2025, driven by its large beverage, food, personal care, household products, and pharmaceutical industries, which collectively generate substantial demand for rigid plastic packaging. The country benefits from a well-established packaging manufacturing ecosystem, extensive PET recycling infrastructure, and the presence of major consumer goods and beverage producers that utilize PET bottles and jars at significant volumes. Furthermore, increasing investments in sustainable packaging solutions, lightweight container designs, and recycled-content packaging continue to strengthen the country's leadership position.
Mexico Rigid PET Bottles And Jars Market Trends
Mexicoaccounted for 12.0% of the North America rigid PET bottles & jars industry in 2025 and is expected to grow at the fastest CAGR during the forecast period. This growth is supported by expanding food and beverage production, rising pharmaceutical manufacturing, and increasing foreign direct investment in the packaging and consumer goods industries. The country's growing middle-class population, urbanization trends, and increasing consumption of packaged products are creating favorable conditions for PET packaging demand. Furthermore, Mexico's strategic role as a manufacturing hub for North American supply chains, coupled with ongoing investments in packaging production capacity and sustainability initiatives, is expected to accelerate market growth over the forecast period.
Key North America Rigid PET Bottles And Jars Company Insights
The market is moderately fragmented, with the presence of major packaging manufacturers, PET resin suppliers, and specialized container producers. Companies compete through packaging innovation, lightweighting, rPET integration, customization capabilities, production efficiency, and regulatory compliance. The market is witnessing growing investments in sustainable packaging, advanced recycling technologies, strategic acquisitions, and capacity expansions, which continue to strengthen competition across beverage, food, personal care, and pharmaceutical applications.
-
In May 2025, Pretium Packaging introduced a lightweight PET vitamin packer bottle portfolio designed for supplements and nutraceutical applications, achieving up to 42% reduction in plastic usage compared to conventional bottle designs. The new packaging solution supports manufacturers' sustainability goals by lowering material consumption while maintaining the functionality, durability, and product protection required for health and wellness products. For the North America rigid PET bottles & jars market, this development reflects the growing emphasis on lightweighting and resource-efficient packaging solutions and is expected to accelerate the adoption of sustainable PET containers across the pharmaceutical, nutraceutical, and consumer healthcare sectors.
-
In March 2025, Amcor plc introduced a 2 oz retort PET bottle featuring StormPanel technology, designed for nutritional shots, coffee, and dairy beverages that require shelf-stable packaging. The bottle is engineered to withstand high-temperature retort processing while maintaining product integrity, offering manufacturers a lightweight and durable alternative to traditional packaging formats. For the North America rigid PET bottles & jars industry, this development highlights the increasing demand for high-performance PET packaging solutions that support advanced food and beverage applications and is expected to drive the adoption of value-added PET containers in the shelf-stable beverage segment.
Key North America Rigid PET Bottles And Jars Companies
-
RSP Inc.
-
Amcor plc
-
Pretium Packaging
-
Plascene, Inc
-
CMG Plastics
-
Santa Clara Plastic Containers
-
Raziele Inc.
-
APG Packaging Group
-
Hub Plastics
-
Precision Plastics Packaging Co.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (Amcor plc, Pretium Packaging, CMG Plastics, APG Packaging Group, and Hub Plastics)
- Focus on large-scale production, lightweight packaging innovations, and long-term supply agreements with beverage, food, personal care, and pharmaceutical manufacturers.
- Invest in recycling infrastructure, PCR PET integration, and advanced manufacturing technologies to improve operational efficiency and sustainability compliance.
- Strong manufacturing networks, established customer relationships, and the ability to serve high-volume packaging requirements across North America.
- Broad product portfolios, extensive technical expertise, and greater financial resources for product development and capacity expansion.
- Higher operational and compliance costs associated with maintaining multiple production facilities and sustainability commitments.
- Slower response to niche market opportunities due to complex organizational structures and longer decision-making processes.
Emerging Players (RSP Inc., Plascene, Santa Clara Plastic Containers, Raziele Inc., and Precision Plastics Packaging Co.)
- Focus on customized PET bottles and jars, shorter production runs, and specialized packaging solutions for niche end-use markets.
- Emphasize customer-centric service, flexible manufacturing, and targeted regional expansion to strengthen market presence.
- Greater agility in addressing specific customer requirements and adapting to changing packaging trends.
- Ability to offer customized designs, lower minimum order quantities, and faster turnaround times for select applications.
- Limited production capacity and geographic reach compared with established industry leaders.
- Lower financial resources for large-scale investments in advanced manufacturing technologies, recycling initiatives, and market expansion.
North America Rigid PET Bottles And Jars Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.5 billion
Estimated market size in 2026
USD 8.8 billion
Projected market size by 2033
USD 12.0 billion
Growth rate
CAGR of 4.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Resin type, capacity, application, country
Country Scope
U.S.; Canada; Mexico
Key companies profiled
RSP Inc.; Amcor plc; Pretium Packaging; Plascene, Inc.; CMG Plastics; Santa Clara Plastic Containers; Raziele Inc.; APG Packaging Group; Hub Plastics; Precision Plastics Packaging Co.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
North America Rigid PET Bottles And Jars Market Report Segmentation
This report forecasts revenue growth at the regional & country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the North America rigid PET bottles and jars market report based on resin type, capacity, application, and country:
-
Resin Type Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Virgin PET (Polyethylene Terephthalate)
-
Recycled PET (rPET)
-
Hybrid PET/rPET
-
-
Capacity Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
<250 ml
-
250-500 ml
-
500-1000 ml
-
1-2 Liters
-
>2 Liters
-
-
Application Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Beverages
-
Bottled Water
-
Carbonated Soft Drinks (CSD)
-
Juices & Juice Drinks
-
Sports & Energy Drinks
-
RTD Tea & Coffee
-
Alcoholic Beverages
-
Dairy & Plant-Based Beverages
-
-
Food
-
Sauces & Condiments
-
Edible Oils
-
Honey, Syrups & Sweeteners
-
Jams, Preserves & Fruit Spreads
-
Peanut Butter & Nut Spreads
-
Dry Foods & Ingredients
-
-
Pharmaceuticals
-
Vitamins & Dietary Supplements
-
OTC Medicines
-
Prescription Medicines
-
Nutraceutical Products
-
-
Personal Care & Cosmetics
-
Hair Care Products
-
Skin Care Products
-
Body Wash & Shower Products
-
Liquid Hand Soap & Sanitizers
-
Cosmetics & Beauty Products
-
Oral Care Products
-
-
Other Applications
-
-
Country Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation Analysis
Detailed market size, forecast, and growth trend analysis for the U.S., Canada, and Mexico, including country-level demand patterns, manufacturing activity, and end-use consumption across rigid PET bottles and jars.
Enabled identification of country-specific growth opportunities, demand centers, and strategic expansion priorities across North America.
Cross-Segmentation Analysis
Comprehensive analysis of the market by Resin Type (Virgin PET, Recycled PET, Hybrid PET/rPET), Capacity (<250 ml, 250-500 ml, 500-1000 ml, 1-2 Liters, >2 Liters), Application (Beverages, Food, Pharmaceuticals, Personal Care & Cosmetics, Other Applications), and Country, including key growth intersections.
Provided deeper insights into high-growth segment combinations, emerging demand pockets, and application-specific opportunities for product portfolio optimization.
Competitive Benchmarking
Comparative assessment of major manufacturers based on product offerings across resin categories, capacity range coverage, application focus, production capabilities, sustainability initiatives, geographic presence, and strategic developments.
Supported competitive positioning analysis, market share evaluation, and identification of differentiation opportunities.
Frequently Asked Questions About This Report
The North America rigid PET bottles and jars market size was valued at USD 8.5 billion in 2025 and is estimated at USD 8.8 billion for 2026.
The North America rigid PET bottles and jars market is expected to grow at a CAGR of 4.5% from 2026 to 2033, reaching USD 12.0 billion by 2033.
U.S. dominated the North America rigid PET bottles and jars market with an 78.6% revenue share in 2025.
The 500-1000 ml segment led the North America rigid PET bottles & jars market with a 34.7% revenue share in 2025.
The beverages segment led the North America rigid PET bottles & jars market with a 61.4% revenue share in 2025.
Key players in the North America rigid PET bottles & jars market include RSP Inc., Amcor plc, Pretium Packaging, Plascene, Inc., CMG Plastics, Santa Clara Plastic Containers, Raziele Inc., APG Packaging Group, Hub Plastics, and Precision Plastics Packaging Co.
Mexico is the fastest-growing country in the North America rigid PET bottles & jars market with a CAGR of 5.3% over the forecast period.
The virgin PET (polyethylene terephthalate) segment led the North America rigid PET bottles & jars market with a 57.1% revenue share in 2025.
Key factors driving the North America rigid PET bottles & jars market include rising demand for packaged beverages, growing use in nutraceutical, pharmaceutical, and personal care packaging, increasing preference for lightweight packaging, and ongoing advancements in PET manufacturing technologies.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


