
- Home
- »
- Clinical Diagnostics
- »
-
Personalized Cancer Vaccine Market Size Report, 2026-2033GVR Report cover

Personalized Cancer Vaccine Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Dendritic Cell, Neoantigen-based), By Technology (Cell-based, mRNA PCV), By Distribution Channel (Hospitals, Clinics), By Region, And Segment Forecasts
Market Size, 2025
$226.7MMarket Estimate, 2026
$246.5MMarket Forecast, 2033
$2,236.3MCAGR, 2026–2033
37.0%Personalized Cancer Vaccine Market Trends
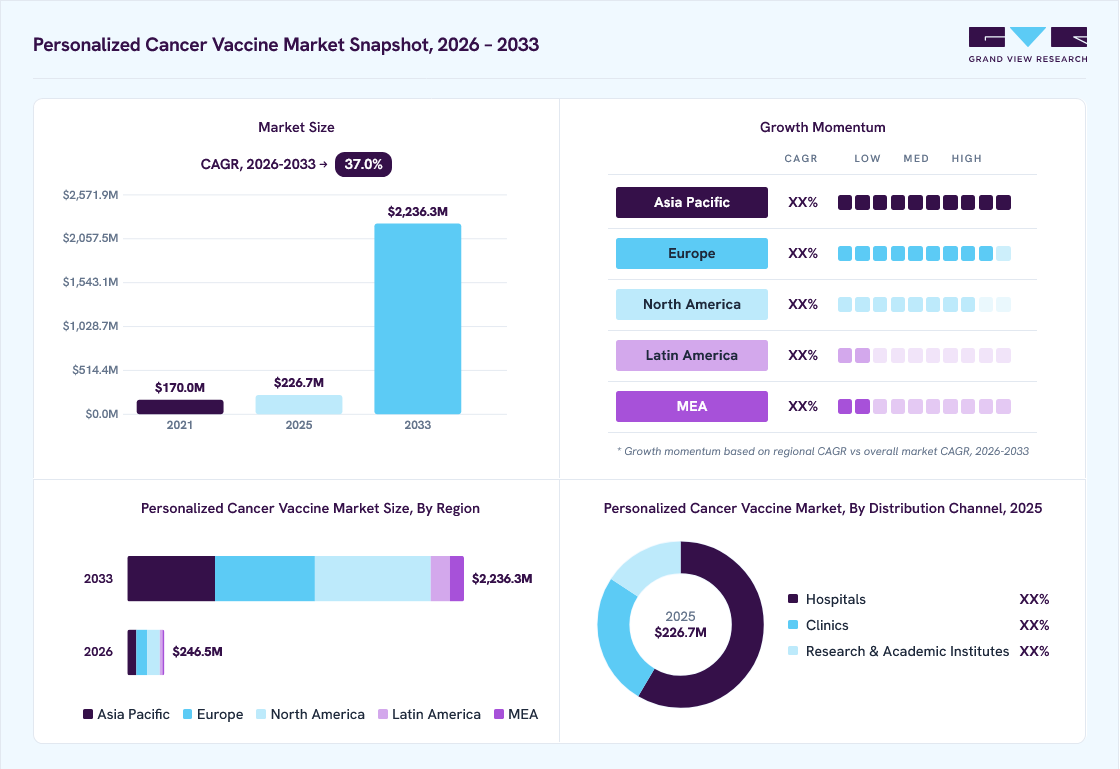
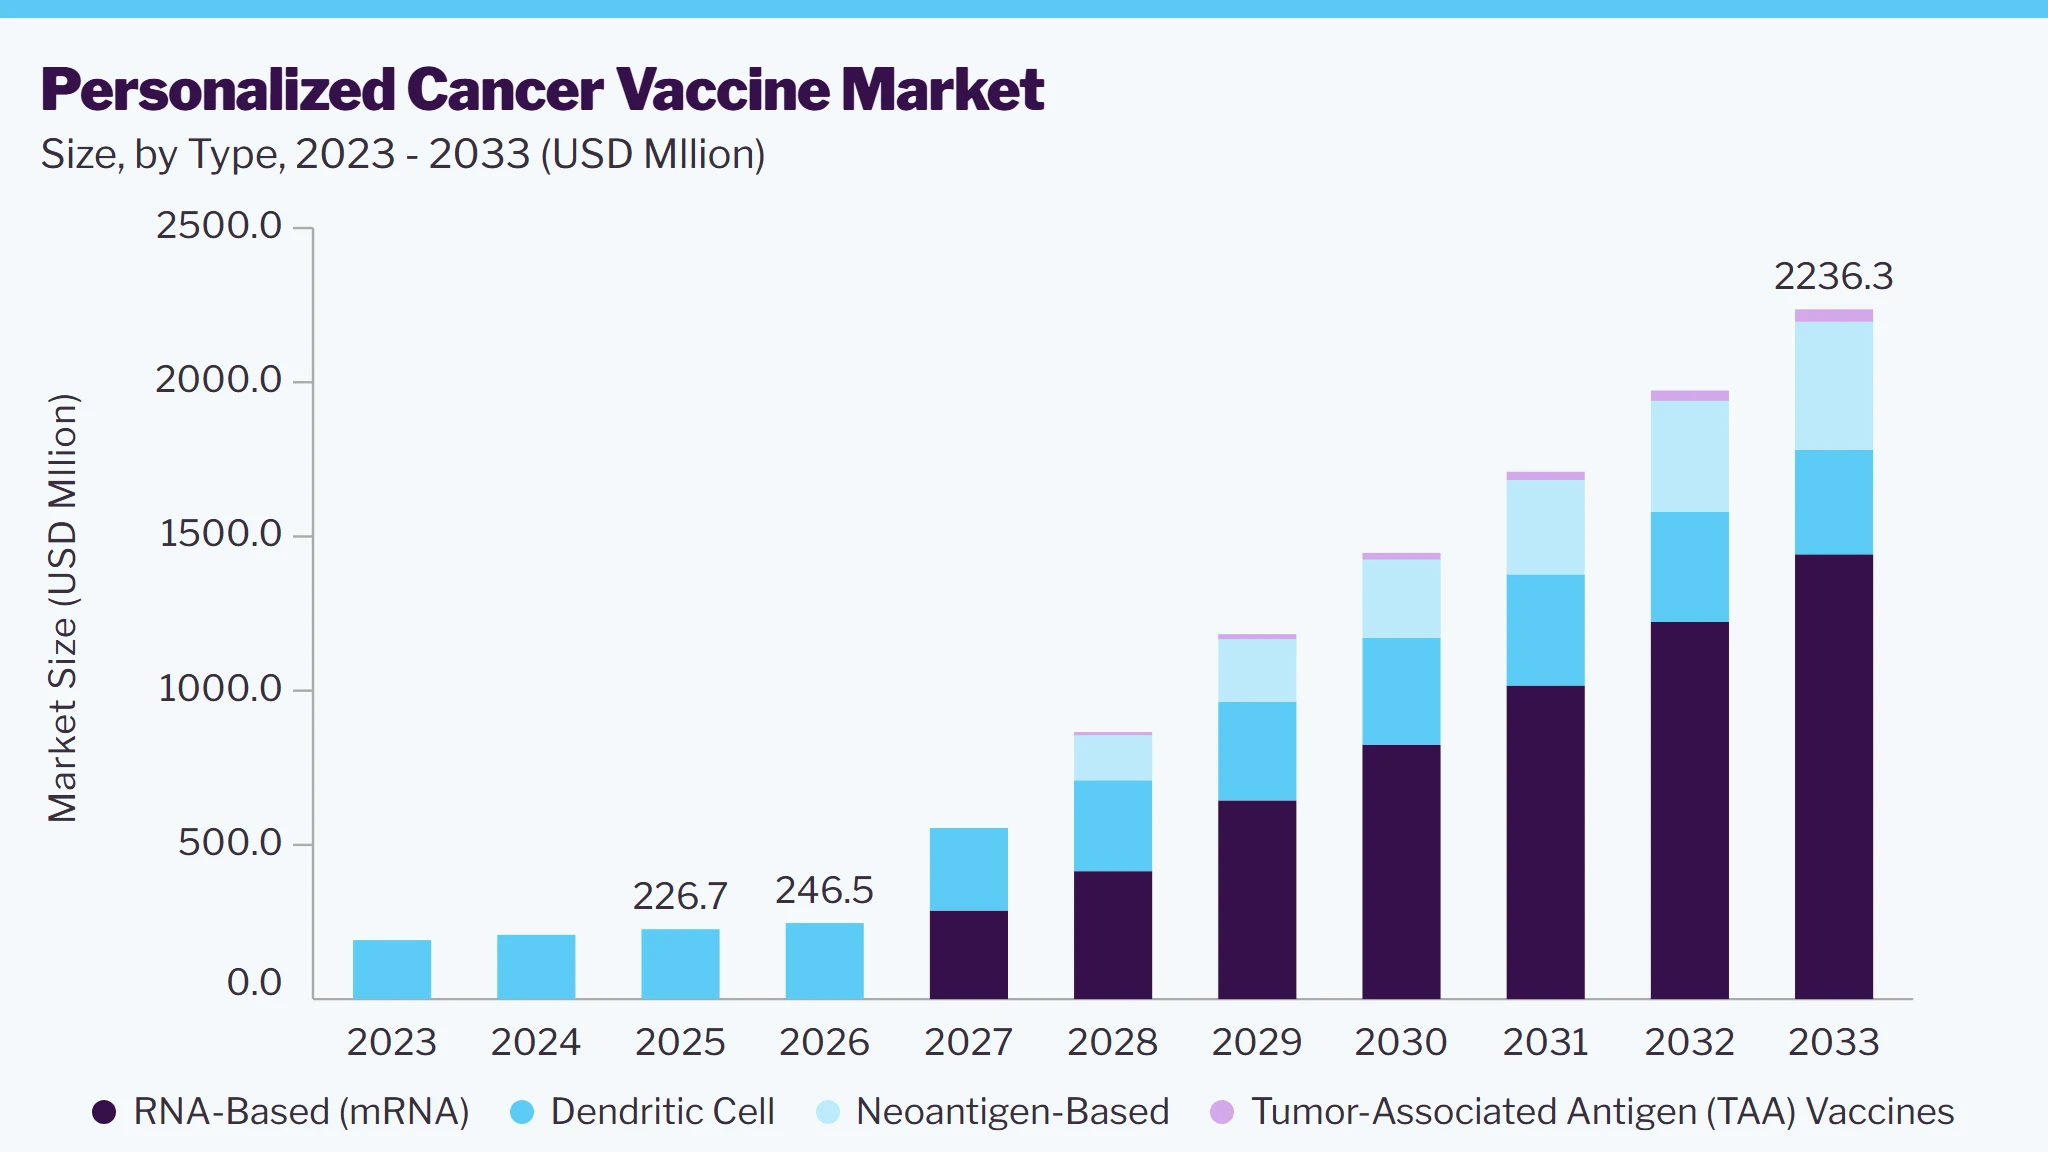
The global personalized cancer vaccine market size was valued at USD 226.7 million in 2025 and is projected to grow from USD 246.5 million in 2026 to USD 2,236.3 million by 2033, at a CAGR of 37.0% from 2026 to 2033. North America dominated the market, with a revenue share of 34.1% in 2025. Unlike conventional therapies, which offer broad-spectrum responses, personalized cancer vaccines utilize specific tumor neoantigens-mutations unique to an individual’s cancer-to trigger a more precise immune attack.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Dendritic cell segment led the market with the largest revenue share of 100.0% in 2025.
- By technology: Cell based segment led the market with the largest revenue share of 100.0% in 2025.
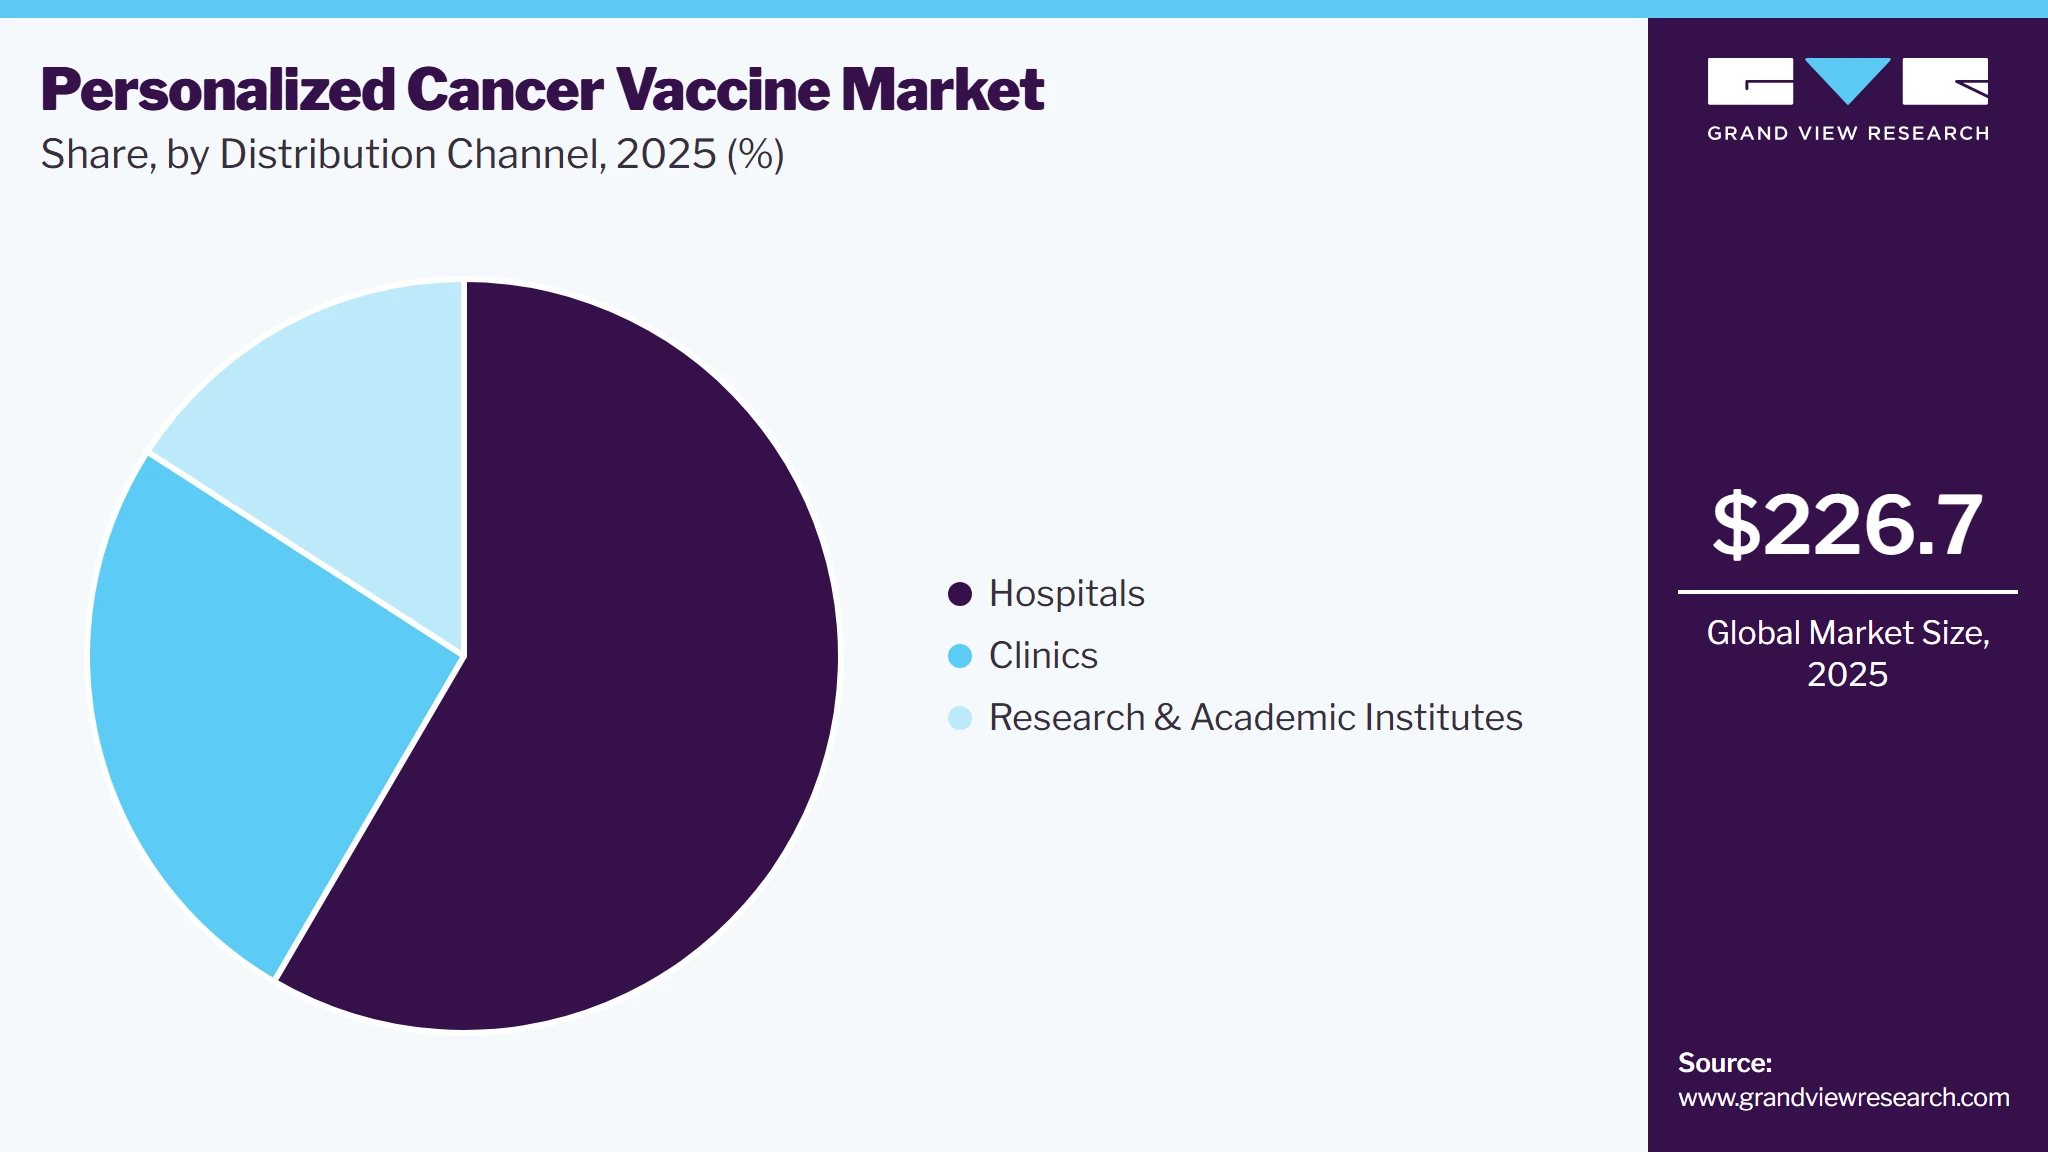
- By distribution channel: Hospital segment led the market with the largest revenue share of 58.4% in 2025.
Regional Highlights
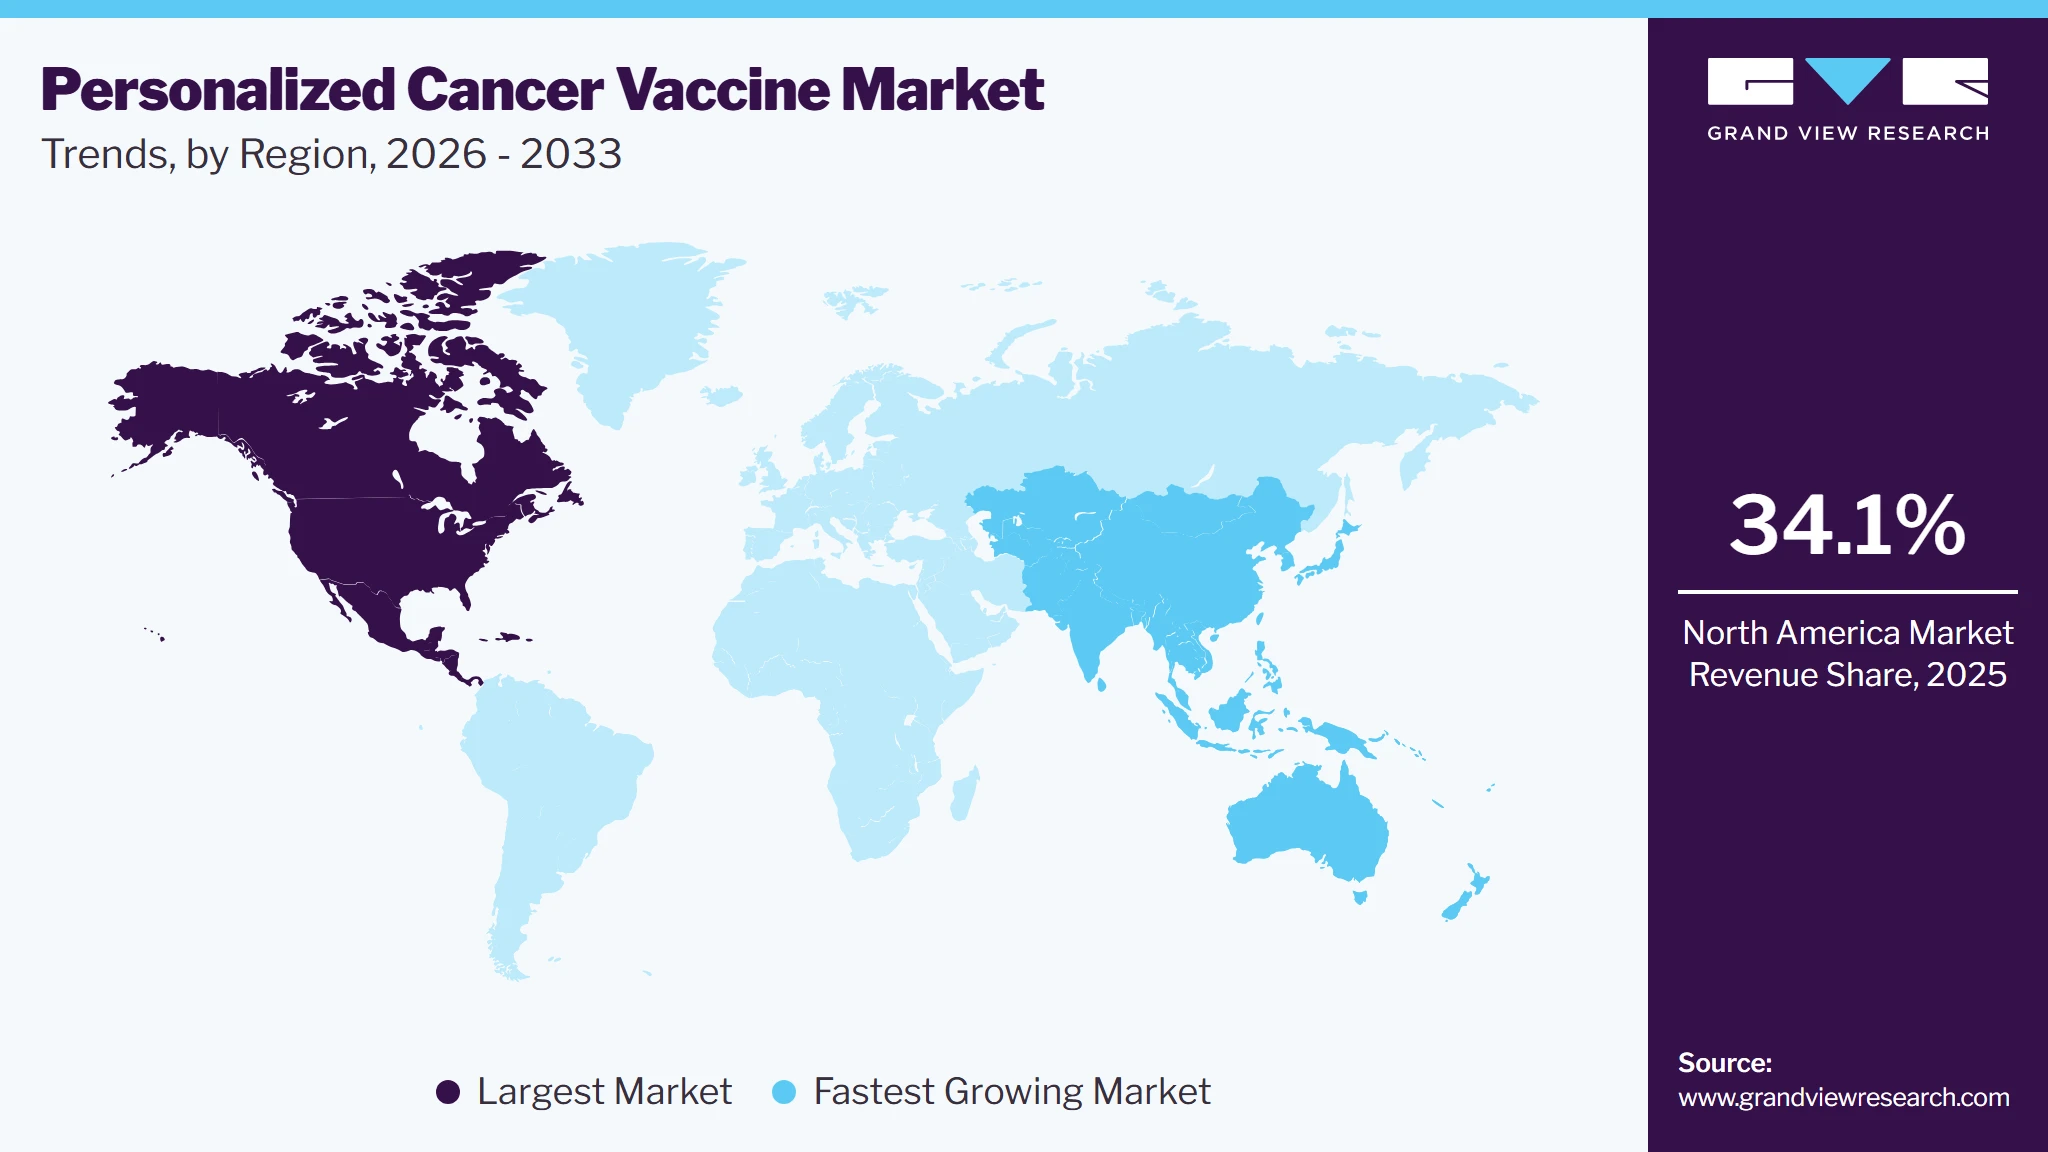
- Largest regional market: North America (34.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 226.7 Million
- Estimated market size in 2026: USD 246.5 Million
- Projected market size by 2033: USD 2,236.3 Million
- CAGR (2026-2033): 37.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These vaccines are often developed using cutting-edge technologies like next-generation sequencing (NGS), artificial intelligence, and mRNA platforms. Personalized vaccines show strong potential in treating cancers such as melanoma, non-small cell lung cancer, and glioblastoma. They are frequently paired with immune checkpoint inhibitors to improve outcomes. While the field is still largely in clinical development, the potential for technology remission with minimal side effects is high. Major players like BioNTech, Moderna, and Genentech are investing heavily in clinical trials and regulatory pathways. As biotechnology matures and regulatory frameworks adapt, personalized cancer vaccines are positioned to become a cornerstone of precision medicine in oncology.
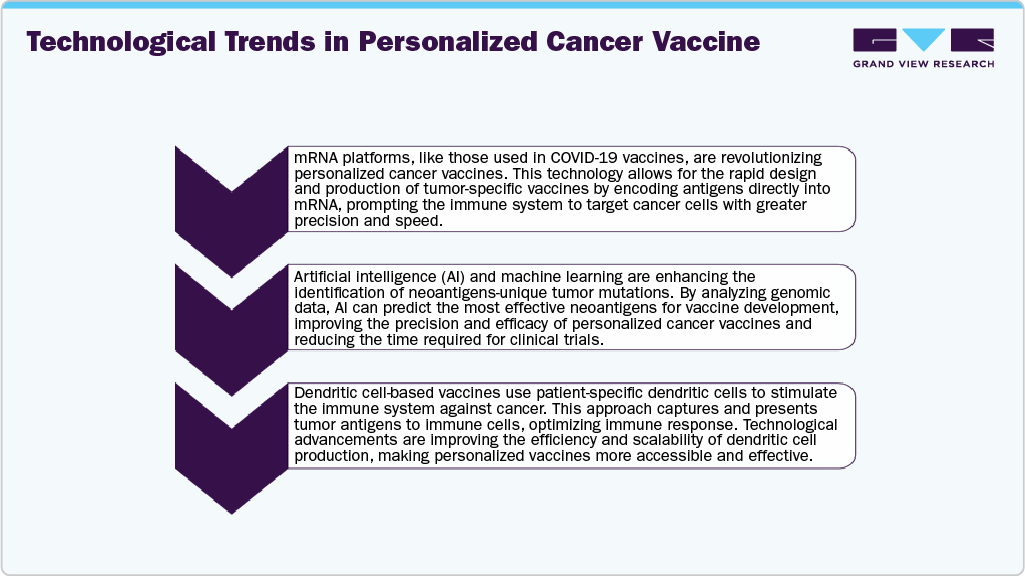
Technological progress plays a central role in accelerating the personalized cancer vaccine industry. Innovations in genomics and bioinformatics now allow for rapid identification of tumor-specific neoantigens through whole-exome and transcriptome sequencing. AI algorithms can predict which neoantigens are most likely to elicit an immune response, thereby streamlining vaccine design. mRNA technology, particularly spotlighted during the COVID-19 pandemic, has proven especially promising due to its speed, scalability, and flexibility. Companies like Moderna and BioNTech leverage mRNA to deliver instructions for making tumor-specific antigens directly into patient cells, training the immune system to target cancer. Dendritic cell-based platforms also offer high antigen specificity and are being optimized using nanotechnology. Moreover, improvements in delivery methods, like lipid nanoparticles, enhance vaccine stability and cellular uptake. As sequencing costs decline and computational power increases, these technologies will become more accessible, shortening development cycles and expanding patient eligibility for personalized immunotherapy.
 To learn more about this report, Download Free Sample Report
The rising global incidence of cancer continues to be a major catalyst for growth in the personalized cancer vaccine market. According to the World Health Organization (WHO, 2022), cancer remains one of the leading causes of death worldwide, with approximately 20 million new cases diagnosed annually. Traditional treatment approaches-such as chemotherapy, radiation therapy, and surgical interventions-often yield limited success, especially in advanced or metastatic stages, and are frequently associated with severe side effects. Moreover, many cancers eventually develop resistance to these conventional therapies, reducing long-term effectiveness.
 To learn more about this report, Download Free Sample Report
Personalized cancer vaccines represent a highly promising alternative by targeting individual tumor mutations (neoantigens), potentially offering improved efficacy with fewer adverse effects. This approach is particularly vital for malignancies with historically poor prognoses, such as pancreatic cancer, glioblastoma, and triple-negative breast cancer. As the global understanding of cancer evolves and it becomes more widely treated as a chronic condition, there is increasing demand for maintenance therapies that prevent recurrence while preserving patient quality of life. Personalized vaccines-customized to the shifting genetic profile of a patient’s tumor-are uniquely positioned to meet this urgent clinical and commercial need.
Strategic partnerships and investments are playing a pivotal role in propelling the personalized cancer vaccine industry. Leading biopharmaceutical companies are entering into collaborations with biotech startups, academic institutions, and genomics firms to advance research, streamline manufacturing, and accelerate clinical trials. For instance, BioNTech and Genentech have partnered on neoantigen vaccine development, while Moderna collaborates with Merck for mRNA-based cancer vaccines. Venture capital investment in personalized immunotherapy is also on the rise, reflecting confidence in the long-term potential of this market. Government funding, such as the U.S. Cancer Moonshot initiative, further underscores institutional commitment to innovation in oncology. Many companies are also acquiring or licensing AI and genomic platforms to enhance antigen prediction and patient selection. These collaborations help to mitigate the high R&D costs and regulatory hurdles inherent in personalized medicine. As the competitive landscape intensifies, partnerships will likely determine which players achieve scalability, regulatory success, and market dominance.
Despite its promise, the personalized cancer vaccine market faces several key challenges. The biggest hurdle is the complexity and cost of personalization-each vaccine must be custom-manufactured, demanding robust logistics, rapid genomic analysis, and tightly regulated production processes. Additionally, tumor heterogeneity and immune evasion remain scientific obstacles, as not all patients respond uniformly. Regulatory ambiguity and lack of universal reimbursement frameworks further slow market adoption. However, the outlook remains optimistic. As AI and automation reduce turnaround times and manufacturing costs, personalized vaccines are expected to become more scalable. Emerging trends such as off-the-shelf neoantigen libraries, pan-cancer platforms, and combination therapies with immune checkpoint inhibitors may help overcome clinical and economic barriers. In the next 5-10 years, we can anticipate a shift from clinical trials to broader commercial application, especially in developed markets. If ongoing trials yield successful outcomes, personalized cancer vaccines could redefine cancer treatment paradigms across the globe.
Market Dynamics
The personalized cancer vaccine market is driven by the increasing focus on precision oncology, advancements in genomic sequencing, and the growing adoption of individualized immunotherapy approaches for cancer treatment. Healthcare providers and research organizations are placing greater emphasis on developing vaccines tailored to a patient's unique tumor mutations to improve immune response and treatment outcomes. Continuous progress in next generation sequencing, bioinformatics, and messenger RNA technologies is supporting the development of personalized vaccine platforms with improved target specificity and manufacturing efficiency. Increasing investments from biotechnology companies, academic institutions, and government organizations are further supporting research and clinical development across multiple cancer indications. In addition, expanding collaborations between pharmaceutical companies and research institutions are accelerating innovation in personalized vaccine platforms and strengthening the precision oncology ecosystem. However, complex manufacturing processes, high development costs, and extended regulatory pathways continue to limit broader commercialization. Despite these challenges, continued innovation in precision medicine and immuno-oncology is supporting the long-term development of the personalized cancer vaccine market.
The increasing adoption of precision oncology and personalized immunotherapy is a key driver of the personalized cancer vaccine market. Advances in genomic profiling and molecular diagnostics have improved the identification of patient specific tumor mutations, enabling the development of vaccines designed to stimulate targeted immune responses against cancer cells. Unlike conventional cancer therapies, personalized cancer vaccines are developed using an individual's tumor characteristics, improving treatment specificity while minimizing damage to healthy tissues. The growing availability of next generation sequencing technologies and artificial intelligence driven neoantigen identification platforms has accelerated vaccine design and development timelines. Healthcare providers are increasingly integrating genomic testing into oncology treatment pathways, creating opportunities for personalized immunotherapies across melanoma, lung cancer, colorectal cancer, pancreatic cancer, and other solid tumors. The expanding clinical evidence supporting individualized treatment approaches is further encouraging pharmaceutical and biotechnology companies to increase investment in personalized vaccine development. An important industry example supports this trend. For instance, in 2025, Moderna and Merck & Co. continued advancing the Phase III clinical development of their individualized neoantigen therapy, INT, for patients with high risk melanoma, strengthening industry confidence in personalized mRNA based cancer vaccines. Continuous innovation in precision medicine technologies and increasing acceptance of individualized treatment strategies continue to support demand for personalized cancer vaccines across global oncology markets.
The complex manufacturing requirements associated with personalized cancer vaccines remain a significant restraint for market expansion. Unlike conventional vaccines that are manufactured in large production batches, personalized cancer vaccines require individual patient tumor sequencing, neoantigen identification, customized vaccine design, and patient specific manufacturing workflows. These processes increase production time, operational complexity, and overall treatment costs. Maintaining product quality while complying with regulatory standards requires specialized manufacturing facilities, advanced bioinformatics capabilities, and coordinated logistics between sequencing laboratories, manufacturing sites, and healthcare providers. The high cost of individualized production also limits accessibility in healthcare systems with constrained reimbursement frameworks. Smaller biotechnology companies often face additional challenges related to manufacturing scale, capital investment, and commercialization capabilities. A notable industry development reflects ongoing efforts to address these challenges. For instance, in 2025, CureVac continued expanding its manufacturing and technology capabilities to improve the scalability of messenger RNA based therapeutic platforms while supporting personalized oncology research. Although technological advances are improving manufacturing efficiency, production complexity and cost continue to limit broader adoption of personalized cancer vaccines, particularly across emerging healthcare markets with limited precision medicine infrastructure.
The increasing integration of messenger RNA technology and artificial intelligence into personalized cancer vaccine development presents a significant opportunity for the market. Artificial intelligence based algorithms are improving the identification and prioritization of tumor specific neoantigens, reducing the time required to design individualized vaccine candidates. At the same time, messenger RNA platforms provide flexible manufacturing approaches that support rapid production of patient specific vaccines while enabling repeated optimization during clinical development. Growing collaboration between biotechnology companies, pharmaceutical manufacturers, and academic research institutions is accelerating innovation across personalized immunotherapy programs. Continued investment in computational biology, genomic sequencing, and digital biomarker analysis is improving the precision of vaccine design and patient selection. The opportunity is further supported by increasing clinical research activity worldwide. For instance, in 2025, Evaxion Biotech continued advancing its artificial intelligence powered cancer vaccine development platform through ongoing clinical studies designed to improve neoantigen prediction and personalized immunotherapy development. As precision medicine becomes more integrated into oncology practice, the adoption of artificial intelligence enabled personalized vaccine platforms is expected to create new opportunities for technology developers, manufacturers, and healthcare providers.
Market Concentration & Characteristics
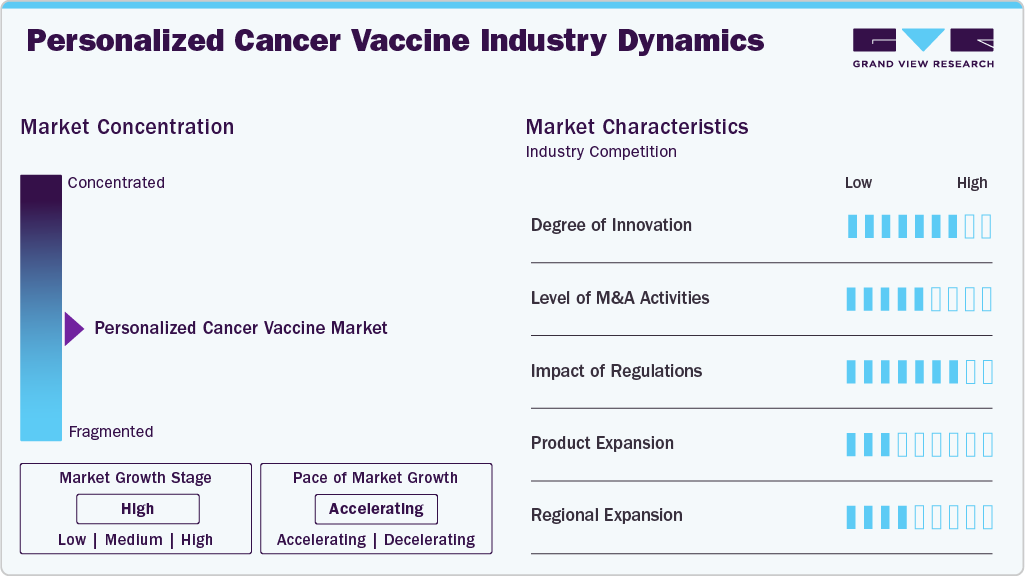
The personalized cancer vaccine market is highly innovative, with advancements in mRNA technology, artificial intelligence for neoantigen discovery, and dendritic cell-based therapies. These innovations enable the development of highly targeted vaccines that offer improved efficacy and fewer side effects compared to traditional therapies. The ongoing integration of cutting-edge technologies accelerates the potential for personalized vaccines to become a standard treatment for various cancer types.
Mergers and acquisitions are significant in the personalized cancer vaccine industry, as established pharmaceutical companies seek to enhance their portfolios and acquire innovative technologies. Notable acquisitions include Moderna's partnership with Merck for mRNA-based cancer vaccines and BioNTech's collaborations. These M&A activities enable access to novel platforms, boosting R&D capabilities and accelerating the clinical and commercial development of personalized therapies in the competitive oncology space.
 To learn more about this report, Download Free Sample Report
Regulation plays a critical role in shaping the personalized cancer vaccine market. Agencies like the FDA and EMA have implemented fast-track pathways, including Breakthrough Therapy and Orphan Drug designations, to expedite the approval of innovative treatments. However, the highly individualized nature of these vaccines poses challenges in standardizing manufacturing and clinical trial protocols, necessitating the creation of new regulatory frameworks to facilitate commercialization.
Product expansion is a key strategy in the market for personalized cancer vaccines. Companies are working to broaden their vaccine offerings by targeting a wider range of cancers, such as pancreatic, glioblastoma, and ovarian cancer. By leveraging platforms like mRNA, DNA, and dendritic cell vaccines, businesses are developing more versatile and scalable therapies, increasing their market reach and potential patient base, leading to more robust market growth.
Regional expansion in the personalized cancer vaccine market is driven by increasing cancer prevalence and demand for advanced therapies. North America and Europe are leading markets due to strong healthcare infrastructure. Asia Pacific is emerging as a key region due to improving access to biotechnology and rising cancer cases. Companies are focusing on expanding their presence globally, particularly in emerging markets, to capture growth opportunities and cater to diverse patient needs.
Analyst Perspective
The personalized cancer vaccine market is characterized by increasing integration of genomic sequencing, precision medicine, and advanced immunotherapy technologies to develop individualized cancer treatments. Market competition is centered on improving neoantigen identification, reducing manufacturing timelines, and enhancing clinical efficacy through patient specific vaccine design. Established biotechnology companies are expanding investments in messenger RNA platforms, artificial intelligence enabled antigen discovery, and precision oncology research, while emerging innovators continue developing specialized vaccine technologies targeting multiple solid tumor indications. Continued progress in sequencing technologies, computational biology, and scalable manufacturing processes is expected to strengthen clinical development and create long term opportunities for participants across the personalized cancer vaccine market.
Type Insights
Based on type, the dendritic cell segment led the market with the largest revenue share of 100.0% in 2025, driven by increasing demand for targeted and individualized immunotherapies. Dendritic cells (DCs) are pivotal in orchestrating immune responses, as they serve as antigen-presenting cells that initiate T-cell activation. Leveraging this mechanism, dendritic cell-based vaccines are engineered by isolating a patient’s own DCs, loading them with tumor-specific antigens, and reintroducing them to stimulate a precise immune attack on cancer cells. This highly personalized approach has gained traction, especially in treating malignancies such as melanoma, prostate cancer, and glioblastoma. Advancing biotechnologies bolster market expansion in this segment, increased clinical trial activity, and encouraging results in terms of patient survival and reduced relapse rates. Furthermore, regulatory approvals, such as the FDA's clearance of Sipuleucel-T (Provenge) for prostate cancer, have validated the potential of dendritic cell vaccines and paved the way for more commercial opportunities. Investment from pharmaceutical and biotech firms into dendritic cell research has surged, further driving innovation and scalability.
RNA-based (mRNA) vaccines are at the forefront of innovation, offering rapid, scalable production and high adaptability to individual patient tumor profiles. Following their success in infectious technologies, mRNA platforms-led by companies like BioNTech and Moderna-are now being tailored to encode tumor-specific neoantigens, generating robust immune responses with high specificity. This segment is expected to witness the fastest growth due to ongoing clinical trials and increasing investment in personalized oncology. Neoantigen-based vaccines, which target mutations unique to an individual’s tumor, represent the most personalized form of cancer immunotherapy. These vaccines demonstrate high specificity and low risk of off-target effects, making them a promising solution for tumors resistant to standard therapies. Advancements in next-generation sequencing and bioinformatics have significantly accelerated the identification of viable neoantigens, driving market growth. TAA-based vaccines, while less individualized, remain valuable due to their broader applicability and established targets across various cancer types. Ongoing enhancements in adjuvant technologies and combination therapies support their growth. Together, these segments are reshaping the landscape of cancer treatment, with strong future potential.
Technology Insights
Based on technology, the cell based segment led the market with the largest revenue share of 100.0% in 2025, underpinned by its ability to harness the body’s own immune system for targeted and adaptive anti-tumor responses. This segment includes therapies that utilize patient-derived cells, particularly dendritic cells, tumor-infiltrating lymphocytes (TILs), or engineered T-cells, to present tumor-specific antigens and stimulate a personalized immune attack against cancer cells. Cell-based vaccines, such as dendritic cell (DC) vaccines, have shown promising efficacy in treating aggressive cancers like glioblastoma, prostate cancer, and melanoma. These vaccines are designed by isolating dendritic cells from the patient, loading them with tumor antigens or neoantigens, and reinfusing them to trigger a T-cell-mediated immune response. Advancements in cell isolation, antigen-loading techniques, and supportive regulatory frameworks for personalized therapies drive their success.
The mRNA PCV segment is projected to register significant market growth during the forecast period, driven by technological advancements and successful clinical outcomes. A key driver of this growth is the promising clinical performance of mRNA-based PCVs. For instance, Moderna's mRNA-4157/V940, developed in collaboration with Merck, demonstrated a 44% reduction in the risk of cancer recurrence or death in patients with resected stage IIIB-IV melanoma when combined with pembrolizumab. This success has led to the vaccine receiving breakthrough therapy designation from the U.S. FDA and PRIME designation from the European Medicines Agency. The adaptability of mRNA technology allows for rapid development of vaccines tailored to individual tumor profiles, enhancing the specificity and efficacy of cancer treatments. This personalized approach is particularly effective in targeting neoantigens-unique mutations present in a patient's tumor-thereby minimizing off-target effects and improving patient outcomes.
Distribution Channel Insights
Based on distribution channel, the hospital segment led the market with the largest revenue share of 58.4% in 2025. Hospitals serve as primary centers for cancer diagnosis, treatment, and follow-up care. They are equipped with advanced diagnostic tools such as MRI, CT, and PET scans, enabling precise identification of tumor-specific antigens essential for developing personalized vaccines. Moreover, hospitals possess specialized facilities for vaccine storage and administration, ensuring the efficacy and safety of these treatments. The high volume of outpatient visits for cancer screening and consultations in hospitals contributes to their dominance in vaccine distribution. Patients often prefer hospitals due to the availability of multidisciplinary teams and comprehensive care services, which facilitate the administration of personalized cancer vaccines.
 To learn more about this report, Download Free Sample Report
The clinics segment is expected to grow significantly over the forecast period, driven by increasing patient demand for accessible, specialized care and the expansion of outpatient oncology services. Clinics, particularly specialty and preventive care centers, offer a more convenient and cost-effective alternative to hospitals for cancer screening, early diagnosis, and follow-up immunization. This accessibility is especially beneficial for patients in urban and semi-urban areas, where clinics can provide timely interventions without the need for hospital visits. The rising awareness of early cancer detection and the importance of personalized treatments has led to a higher patient turnout at clinics, bolstering their role in vaccine administration.
Regional Insights
North America dominated the personalized cancer vaccine market with the largest revenue share of 34.1% in 2025, driven by advancements in immunotherapy and a strong healthcare infrastructure. This growth is fueled by the increasing prevalence of cancer, with the U.S. alone reporting an estimated 1.9 million new cancer cases in 2022. The region's dominance is further supported by significant investments in research and development, particularly in mRNA-based personalized vaccines. For instance, Moderna and Merck's collaboration on the mRNA-4157/V940 vaccine has shown promising results in melanoma treatment. Additionally, institutions like the Center for Personal Cancer Vaccines (CPCV) in the U.S. are pioneering patient-specific therapies, enhancing the region's leadership in personalized oncology.
 To learn more about this report, Download Free Sample Report
U.S. Personalized Cancer Vaccine Market Trends
The personalized cancer vaccine market in the U.S. held the largest share in the North America region in 2025. The U.S. personalized cancer vaccine industry growth is robust, driven by advancements in immunotherapy, increasing cancer prevalence, and substantial investments in research and development. Additionally, institutions like the Center for Personal Cancer Vaccines (CPCV) in the U.S. are pioneering patient-specific therapies, enhancing the country's leadership in personalized oncology. The presence of major pharmaceutical companies, a supportive regulatory environment, and increasing awareness of personalized medicine among healthcare professionals and patients contribute to the market's robust growth.
Europe Personalized Cancer Vaccine Market Trends
Europe personalized cancer vaccine industry is expanding, driven by advancements in immunotherapy and increasing collaborations between research institutions and pharmaceutical companies. This growth is further supported by strategic partnerships, such as GlaxoSmithKline's USD 56.74 million collaboration with the University of Oxford to explore cancer vaccines. Additionally, BioNTech's phase 2 clinical trial of Autogene cevumeran, a personalized cancer vaccine targeting neoantigens, highlights positive developments in the region. These initiatives underscore Europe's commitment to advancing personalized oncology treatments.
The personalized cancer vaccine market in the UK is expected to witness growth due to the advancements in immunotherapy and strategic collaborations. Additionally, Moderna is establishing a manufacturing and research center in Oxfordshire dedicated to producing mRNA vaccines, enhancing the UK's readiness for future pandemics, and advancing personalized cancer treatments.
Germany personalized cancer vaccine market growth is driven by advancements in immunotherapy and a strong healthcare infrastructure. Additionally, Germany's robust research ecosystem and collaborations between academic institutions and pharmaceutical companies contribute to the market's expansion. The presence of well-known market firms like GlaxoSmithKline, CureVac AG, and others further enhances the country's position in the personalized cancer vaccine landscape.
Asia Pacific Personalized Cancer Vaccine Market Trends
The Asia Pacific personalized cancer vaccine industry is experiencing significant growth, driven by increasing cancer incidence, technological advancements, and supportive government initiatives. Countries like China, India, and Japan are leading this growth due to their large populations and rising cancer burdens. Technological advancements, such as mRNA-based vaccines and neoantigen-targeted therapies, are also contributing to market expansion. The region's improving healthcare infrastructure and increasing investments in research and development further support the adoption of personalized cancer vaccines. Additionally, collaborations between pharmaceutical companies and research institutions are accelerating vaccine development and commercialization.
The Japan personalized cancer vaccine market is experiencing significant growth. This growth is driven by factors such as an aging population, rising cancer incidence, and strong government initiatives supporting immunization programs and research funding. Technological advancements, including mRNA and gene-based vaccines, are accelerating development and production. Collaborations between government agencies, academic institutions, and pharmaceutical companies are fostering innovation. For instance, NEC Bio B.V. presented interim results from a Phase 1 clinical trial of NECVAX-NEO1, an AI-driven personalized oral cancer vaccine, demonstrating safety and immunogenicity in patients with solid tumors.
The personalized cancer vaccine market in China is witnessing substantial growth, fueled by government initiatives like "Healthy China 2030," which emphasize improving healthcare access and reducing dependence on imports. Chinese pharmaceutical companies are actively developing therapeutic cancer vaccines, with 23 different cancer vaccines in Phase I to Phase III clinical development as of August 2024, 60% of which are therapeutic.
Latin America Personalized Cancer Vaccine Market Trends
The Latin America personalized cancer vaccine industry is experiencing notable growth, driven by increasing cancer prevalence, advancements in immunotherapy, and supportive healthcare policies. Brazil stands out as the fastest-growing market within the region, supported by its robust public healthcare system and rising adoption of personalized therapies. Noteworthy innovations such as Racotumomab (Vaxira), co-developed by Argentina and Cuba for treating non-small cell lung cancer (NSCLC), highlight Latin America’s commitment to localizing advanced cancer treatment. These factors collectively position Latin America as an emerging hub for personalized cancer vaccine innovation and accessibility.
Middle East and Africa Personalized Cancer Vaccine Market Trends
The Middle East and Africa (MEA) personalized cancer vaccine industry is experiencing significant growth, driven by rising cancer incidence, government initiatives, and advancements in vaccine technology. In South Africa, initiatives such as the establishment of a new vaccine manufacturing plant in Cape Town aim to accelerate the production of cancer vaccines. Government programs, such as the introduction of HPV vaccination campaigns in countries like Saudi Arabia and Sierra Leone, are enhancing awareness and adoption of preventive cancer vaccines.
Key Personalized Cancer Vaccine Company Insights
Key market players in the personalized cancer vaccine industry are increasingly focusing on strategic initiatives to expand their global footprint and enhance competitiveness. These strategies include launching innovative new products tailored to specific cancer types, entering into research and development collaborations, forming strategic alliances, and expanding operations into emerging markets. Such efforts aim to accelerate clinical development, gain regulatory approvals, and improve market penetration. Leading companies actively driving these initiatives include Dendreon Pharmaceuticals, LLC, known for its immunotherapy advancements; Gritstone Bio, leveraging AI and neoantigen technology; CureVac, a pioneer in mRNA therapeutics; and the partnership between NeoCura and Innovent, which combines mRNA innovation with immuno-oncology expertise.
Key Personalized Cancer Vaccine Companies:
The following key companies have been profiled for this study on the personalized cancer vaccine market.
-
Dendreon Pharmaceuticals, LLC
-
Gritstone Bio
-
CureVac
-
NeoCura & Innovent
-
Stemirna Therapeutics
-
Elicio Therapeutics
-
Evaxion Biotech
-
Imugene
-
Nouscom
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Precision Oncology and mRNA Platform Developers (CureVac, Gritstone Bio, Stemirna Therapeutics, Innovent Biologics)
- Focus on advancing personalized cancer vaccine platforms through genomic sequencing, mRNA technology, and precision immunotherapy research. Invest in clinical trials, strategic collaborations, artificial intelligence enabled antigen discovery, and scalable manufacturing capabilities to strengthen oncology pipelines.
- Strong expertise in messenger RNA technologies, precision medicine, genomic analysis, and established research capabilities. Ability to integrate sequencing, bioinformatics, and vaccine manufacturing to support personalized treatment development.
- Continued dependence on clinical trial success, significant research investment requirements, and regulatory uncertainties associated with individualized cancer vaccine development.
Specialized Personalized Cancer Vaccine Innovators (Dendreon Pharmaceuticals, NeoCura, Elicio Therapeutics, Evaxion Biotech, Imugene, Nouscom)
- Focus on developing individualized cancer vaccines using dendritic cell technologies, neoantigen discovery platforms, artificial intelligence, peptide vaccines, and targeted immunotherapy approaches. Strengthen clinical development through academic collaborations, biotechnology partnerships, and technology innovation.
- High level of specialization in personalized immunotherapy, innovative vaccine platforms, and flexibility to rapidly develop next generation individualized cancer vaccines addressing multiple solid tumor indications.
- Limited commercial infrastructure, smaller product portfolios, reliance on external funding, and greater exposure to clinical development risks compared with diversified biotechnology companies.
Recent Developments
-
In March 2025, researchers from the Icahn School of Medicine at Mount Sinai, led by Dr. Nina Bhardwaj-Ward-Coleman Chair in Cancer Research and Director of the Vaccine and Cell Therapy Laboratory, conducted a Phase 1 clinical trial of a novel personalized cancer vaccine called PGV001. This multi-peptide neoantigen vaccine was tested in a small group of patients and represents a significant advancement in cancer immunotherapy. PGV001 is designed to stimulate the immune system by using multiple specific peptides (short chains of amino acids) that help the body recognize and attack cancer cells, potentially preventing the disease from returning. The promising results of this early study are detailed in the latest edition of Cancer Discovery, the journal of the American Association for Cancer Research.
-
In February 2025, researchers at Dana-Farber Cancer Institute announced encouraging results from a clinical trial involving patients with stage III or IV clear cell renal cell carcinoma, a type of kidney cancer. All nine participants in the study developed a strong anti-cancer immune response following treatment with a personalized cancer vaccine. The vaccines were given post-surgery, aiming to train the immune system to detect and destroy any residual cancer cells. At the data cut-off point, with a median follow-up of 34.7 months, all patients remained free of cancer recurrence.
-
In April 2024, a personalized vaccine for liver cancer demonstrated promising results in a clinical trial led by researchers at the Johns Hopkins Kimmel Cancer Center and its Convergence Institute. The study focused on patients with hepatocellular carcinoma, the most common form of liver cancer. Blood samples from participants revealed an increase in antitumor immune cells following treatment, suggesting a potential mechanism by which the personalized vaccine enhances the body’s immune response. The trial also showed that combining the personalized vaccine with standard immunotherapy was safe and nearly twice as effective in shrinking tumors compared to standard immunotherapy alone. These findings highlight the potential of personalized cancer vaccines to significantly improve treatment outcomes.
Personalized Cancer Vaccine Market Report Scope
Report Attribute
Details
Market size in 2025
USD 226.7 million
Estimated market size in 2026
USD 246.5 million
Projected market size by 2033
USD 2,236.3 million
Growth rate
CAGR of 37.0% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, technology, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Dendreon Pharmaceuticals, LLC; Gritstone Bio; CureVac, NeoCura & Innovent; Stemirna Therapeutics; Elicio Therapeutics; Evaxion Biotech; Imugene; Nouscom
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Personalized Cancer Vaccine Market Report Segmentation
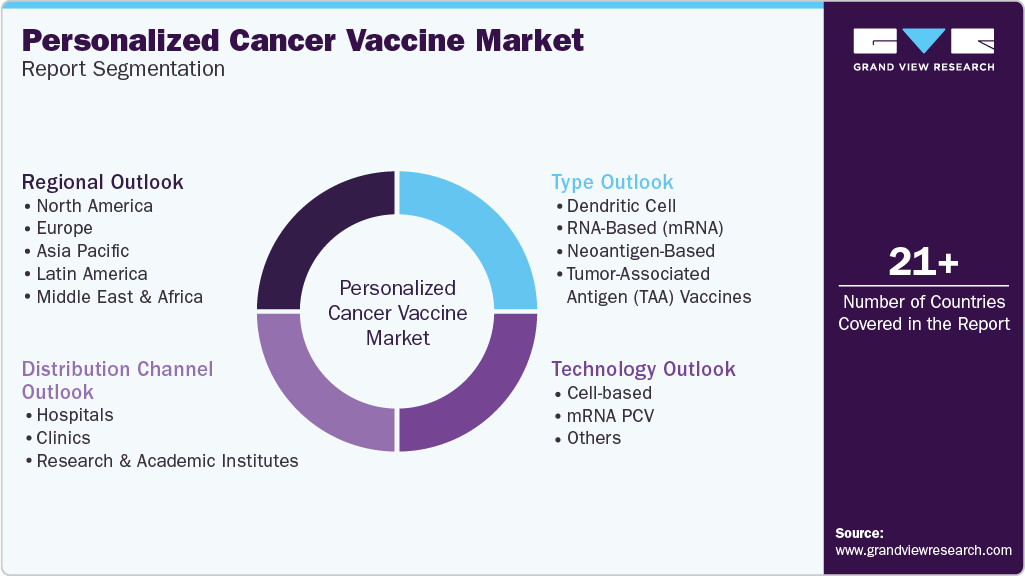
This report forecasts revenue growth and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the personalized cancer vaccine market report based on type, technology, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Dendritic Cell
-
RNA-Based (mRNA)
-
Neoantigen-Based
-
Tumor-Associated Antigen (TAA) Vaccines
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Cell-based
-
mRNA PCV
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Clinics
-
Research & Academic Institutes
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The personalized cancer vaccine market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each personalized cancer vaccine segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Dendritic Cell
This segment includes personalized cancer vaccines developed using autologous dendritic cells that are isolated, loaded with patient specific tumor antigens or neoantigens, and reinfused to stimulate an immune response against cancer cells. The segment captures revenue generated from dendritic cell based personalized vaccine products and associated therapeutic applications.
RNA-Based (mRNA)
This segment includes personalized cancer vaccines developed using messenger RNA technology to encode patient specific tumor antigens or neoantigens for therapeutic cancer treatment. The segment is classified based on the vaccine platform irrespective of the antigen source and captures revenue generated from individualized mRNA vaccine products used across oncology applications.
Neoantigen-Based
This segment includes personalized cancer vaccines designed using patient specific neoantigens identified through genomic sequencing and bioinformatics analysis. The segment is classified based on antigen selection irrespective of the delivery platform and captures revenue generated from individualized neoantigen targeted vaccine products developed for therapeutic cancer treatment.
Tumor-Associated Antigen (TAA) Vaccines
This segment includes personalized cancer vaccines targeting tumor associated antigens that are selectively expressed or overexpressed in cancer cells. The segment captures revenue generated from therapeutic vaccine products designed to enhance immune recognition of validated tumor associated antigens across multiple cancer indications.
Segment - Technology
Revenue capture definition
Cell-based
This segment includes personalized cancer vaccine technologies that utilize living autologous or patient derived immune cells for antigen presentation and immune activation. The segment captures revenue generated from cell processing, vaccine manufacturing, and personalized cell based immunotherapy products developed for cancer treatment.
mRNA PCV
This segment includes personalized cancer vaccine technologies utilizing messenger RNA platforms to deliver individualized genetic instructions encoding patient specific tumor antigens. The segment captures revenue generated from mRNA based personalized cancer vaccine platforms, manufacturing technologies, and therapeutic vaccine products irrespective of cancer indication.
Others
This segment includes personalized cancer vaccine technologies that do not utilize cell based or messenger RNA platforms, including DNA vaccines, peptide vaccines, viral vector vaccines, and other emerging personalized vaccine technologies. The segment captures revenue generated from alternative therapeutic vaccine platforms developed for individualized cancer immunotherapy.
Segment - Distribution Channel
Revenue capture definition
Hospitals
This segment includes revenue generated from personalized cancer vaccines procured and administered through hospitals, comprehensive cancer centers, and hospital based oncology departments. These facilities manage advanced cancer care, individualized treatment planning, and multidisciplinary therapeutic services requiring specialized clinical infrastructure.
Clinics
This segment includes revenue generated from personalized cancer vaccines distributed through specialty oncology clinics, ambulatory cancer treatment centers, and physician managed infusion facilities. These healthcare providers primarily deliver outpatient immunotherapy services and individualized cancer treatment with limited inpatient infrastructure.
Research & Academic Institutes
This segment includes revenue generated from personalized cancer vaccines supplied to research organizations, academic institutions, and clinical research centers for translational research, investigator initiated studies, and clinical trial activities. The segment supports vaccine discovery, clinical validation, and evaluation of emerging personalized immunotherapy technologies.
Estimation Model
 To learn more about this report, Download Free Sample Report
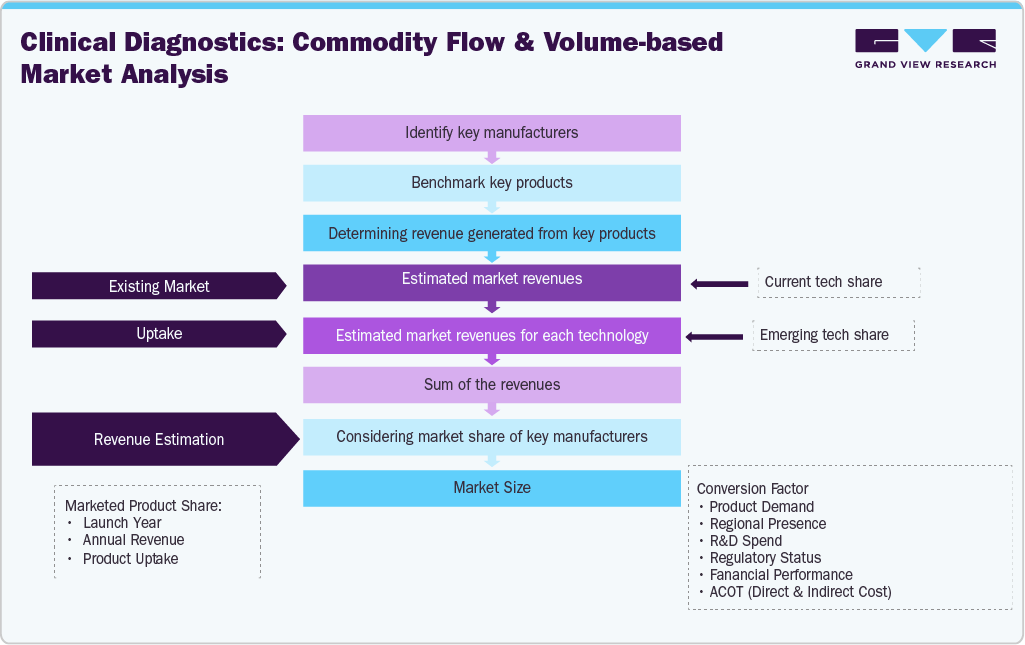
The personalized cancer vaccine market was estimated using a commodity flow market analysis by identifying key companies developing individualized cancer vaccine platforms, including mRNA, dendritic cell, neoantigen, and tumor associated antigen vaccines. Commercialized products, clinical-stage therapies with revenue generation, and technology licensing activities were benchmarked to estimate company-level revenues. Product revenues were validated through annual reports, investor presentations, regulatory filings, clinical pipeline assessments, licensing agreements, and manufacturing partnerships. Market estimates incorporated commercialization status, manufacturing capacity, geographic presence, technology platform adoption, and strategic collaborations to determine the contribution of each company. Revenue generated from personalized cancer vaccine products and associated platform technologies was aggregated and adjusted using market share analysis of leading participants. Primary interviews with biotechnology executives, oncology specialists, contract manufacturing organizations, and industry experts were conducted to validate revenue assumptions, product adoption trends, pricing, and regional demand, ensuring accurate global market estimation.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Personalized Cancer Vaccine Competitive Landscape & Pipeline Assessment
Conducted a targeted assessment of the global personalized cancer vaccine landscape, evaluating approved therapies, clinical stage pipeline assets, vaccine platforms, neoantigen discovery technologies, genomic sequencing capabilities, and competitive positioning. The study analyzed key participants including Gritstone Bio, CureVac, Dendreon Pharmaceuticals, Elicio Therapeutics, Evaxion Biotech, Stemirna Therapeutics, Nouscom, Immagene, NeoCura, and Imcare, along with emerging trends in individualized immunotherapy, messenger RNA vaccines, dendritic cell vaccines, and artificial intelligence enabled antigen identification.
Helped the client identify high potential vaccine platforms, evaluate competitive threats, benchmark pipeline differentiation, and prioritize licensing, acquisition, collaboration, and investment opportunities within the personalized cancer vaccine market.
Personalized Cancer Vaccine Technology & Platform Benchmarking Study
Delivered a comprehensive benchmarking analysis of personalized cancer vaccine technologies, focusing on messenger RNA platforms, dendritic cell vaccines, neoantigen identification, peptide-based vaccines, and artificial intelligence enabled antigen prediction, manufacturing scalability, and clinical performance. The assessment compared established and emerging technologies by evaluating scalability, manufacturing complexity, turnaround time, clinical development progress, regulatory positioning, and platform differentiation across leading vaccine developers.
Enabled the client to assess technology competitiveness, identify platform gaps, benchmark innovation strategies, and prioritize investments in next generation personalized cancer vaccine platforms, precision oncology technologies, and individualized immunotherapy programs.
Personalized Cancer Vaccine Manufacturing & Commercialization Feasibility Assessment
Conducted a strategic assessment of the personalized cancer vaccine ecosystem, evaluating patient specific manufacturing workflows, genomic sequencing integration, bioinformatics capabilities, supply chain requirements, regulatory pathways, contract manufacturing partnerships, distribution strategies, and commercialization readiness. The study analyzed manufacturing scalability, quality control requirements, treatment delivery models, reimbursement considerations, and regional infrastructure supporting the adoption of personalized cancer vaccines.
Supported strategic commercialization planning by identifying manufacturing optimization opportunities, evaluating technology partnerships, mitigating operational and supply chain risks, assessing reimbursement challenges, and strengthening long term scalability and market access strategies across global oncology markets.
Frequently Asked Questions About This Report
Cell based segment led the market with the largest revenue share of 100.0% in 2025.
The global personalized cancer vaccine market is expected to grow at a CAGR of 37.0% from 2026 to 2033, reaching USD 2,236.3 million by 2033.
The dendritic cell segment led the market with a 100.0% revenue share in 2025.
The global personalized cancer vaccine market size was valued at USD 226.7 million in 2025 and is estimated at USD 246.5 million for 2026.
Hospital segment led the market with the largest revenue share of 58.4% in 2025.
Key players include Dendreon Pharmaceuticals, LLC, Gritstone Bio, CureVac, NeoCura, Innovent Biologics, Stemirna Therapeutics, Elicio Therapeutics, Evaxion Biotech, Imugene, and Nouscom.
Key factors include the increasing adoption of precision oncology and personalized immunotherapy, advancements in genomic sequencing and neoantigen identification, growing development of mRNA-based vaccine platforms, and rising investments and collaborations in individualized cancer immunotherapy.
North America market dominated, with a revenue share of 34.1% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


