
- Home
- »
- Clinical Diagnostics
- »
-
Prostate Cancer Biomarker Market Size, Share Report, 2033GVR Report cover

Prostate Cancer Biomarker Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Genetic Biomarkers, Cell-based Biomarkers), By Application (Screening and Early Detection, Diagnosis & Risk Stratification), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$5.3BMarket Estimate, 2026
$6.0BMarket Forecast, 2033
$14.5BCAGR, 2026–2033
13.5%Prostate Cancer Biomarker Market Summary
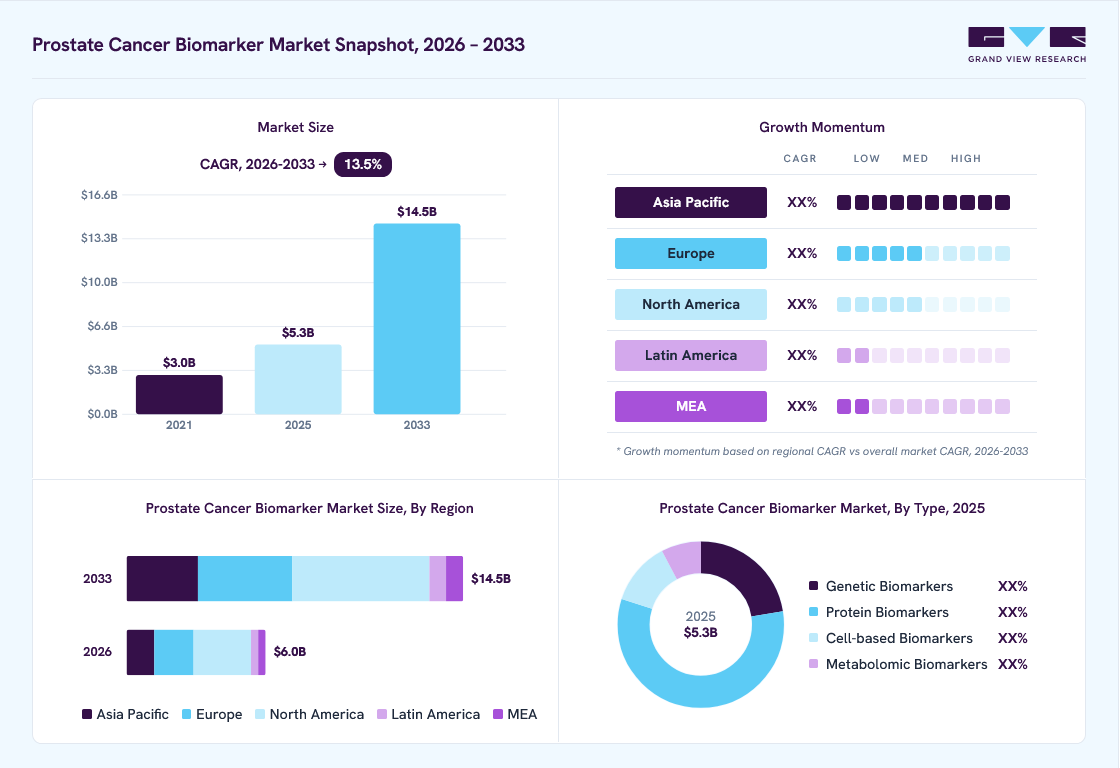
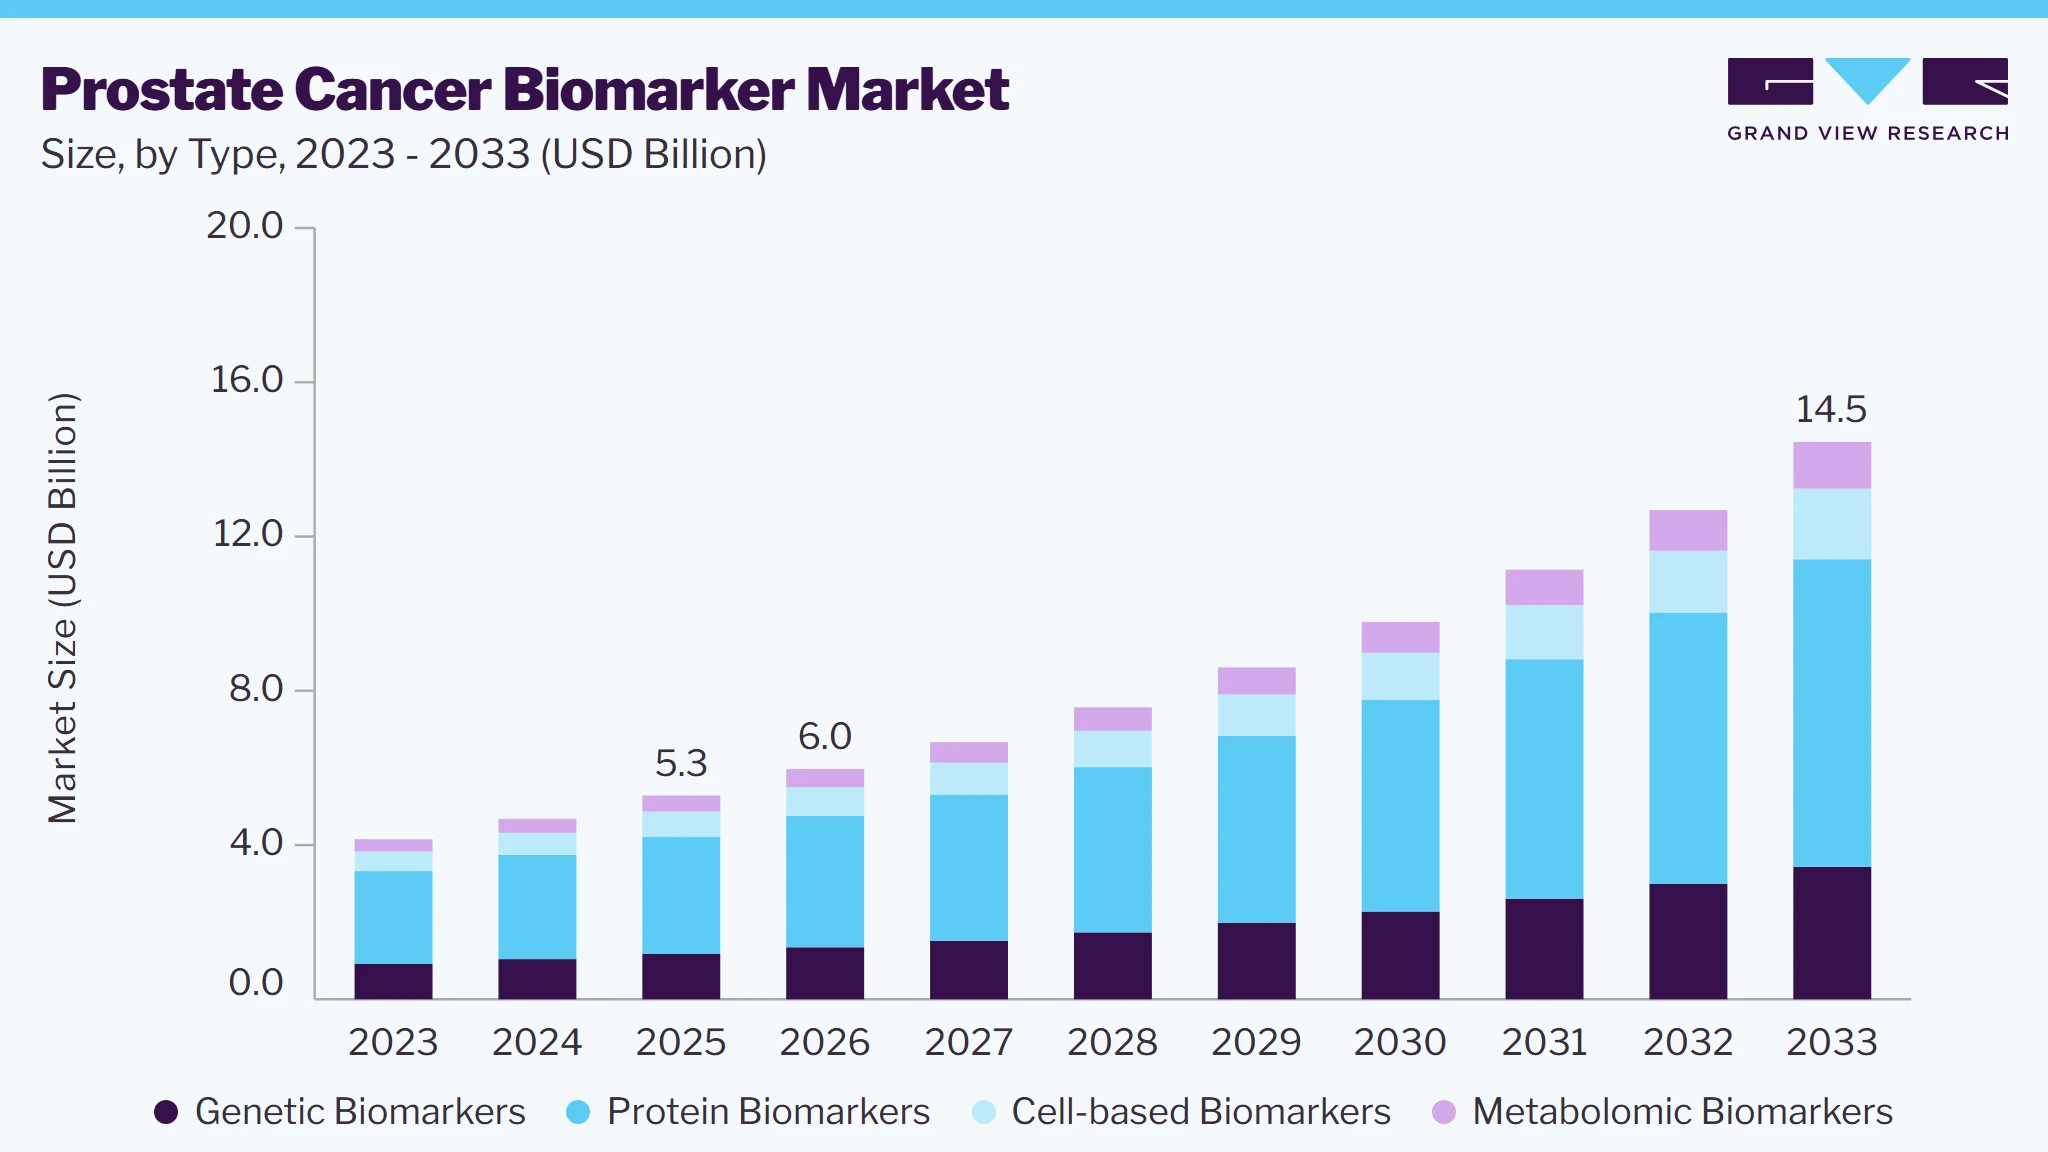
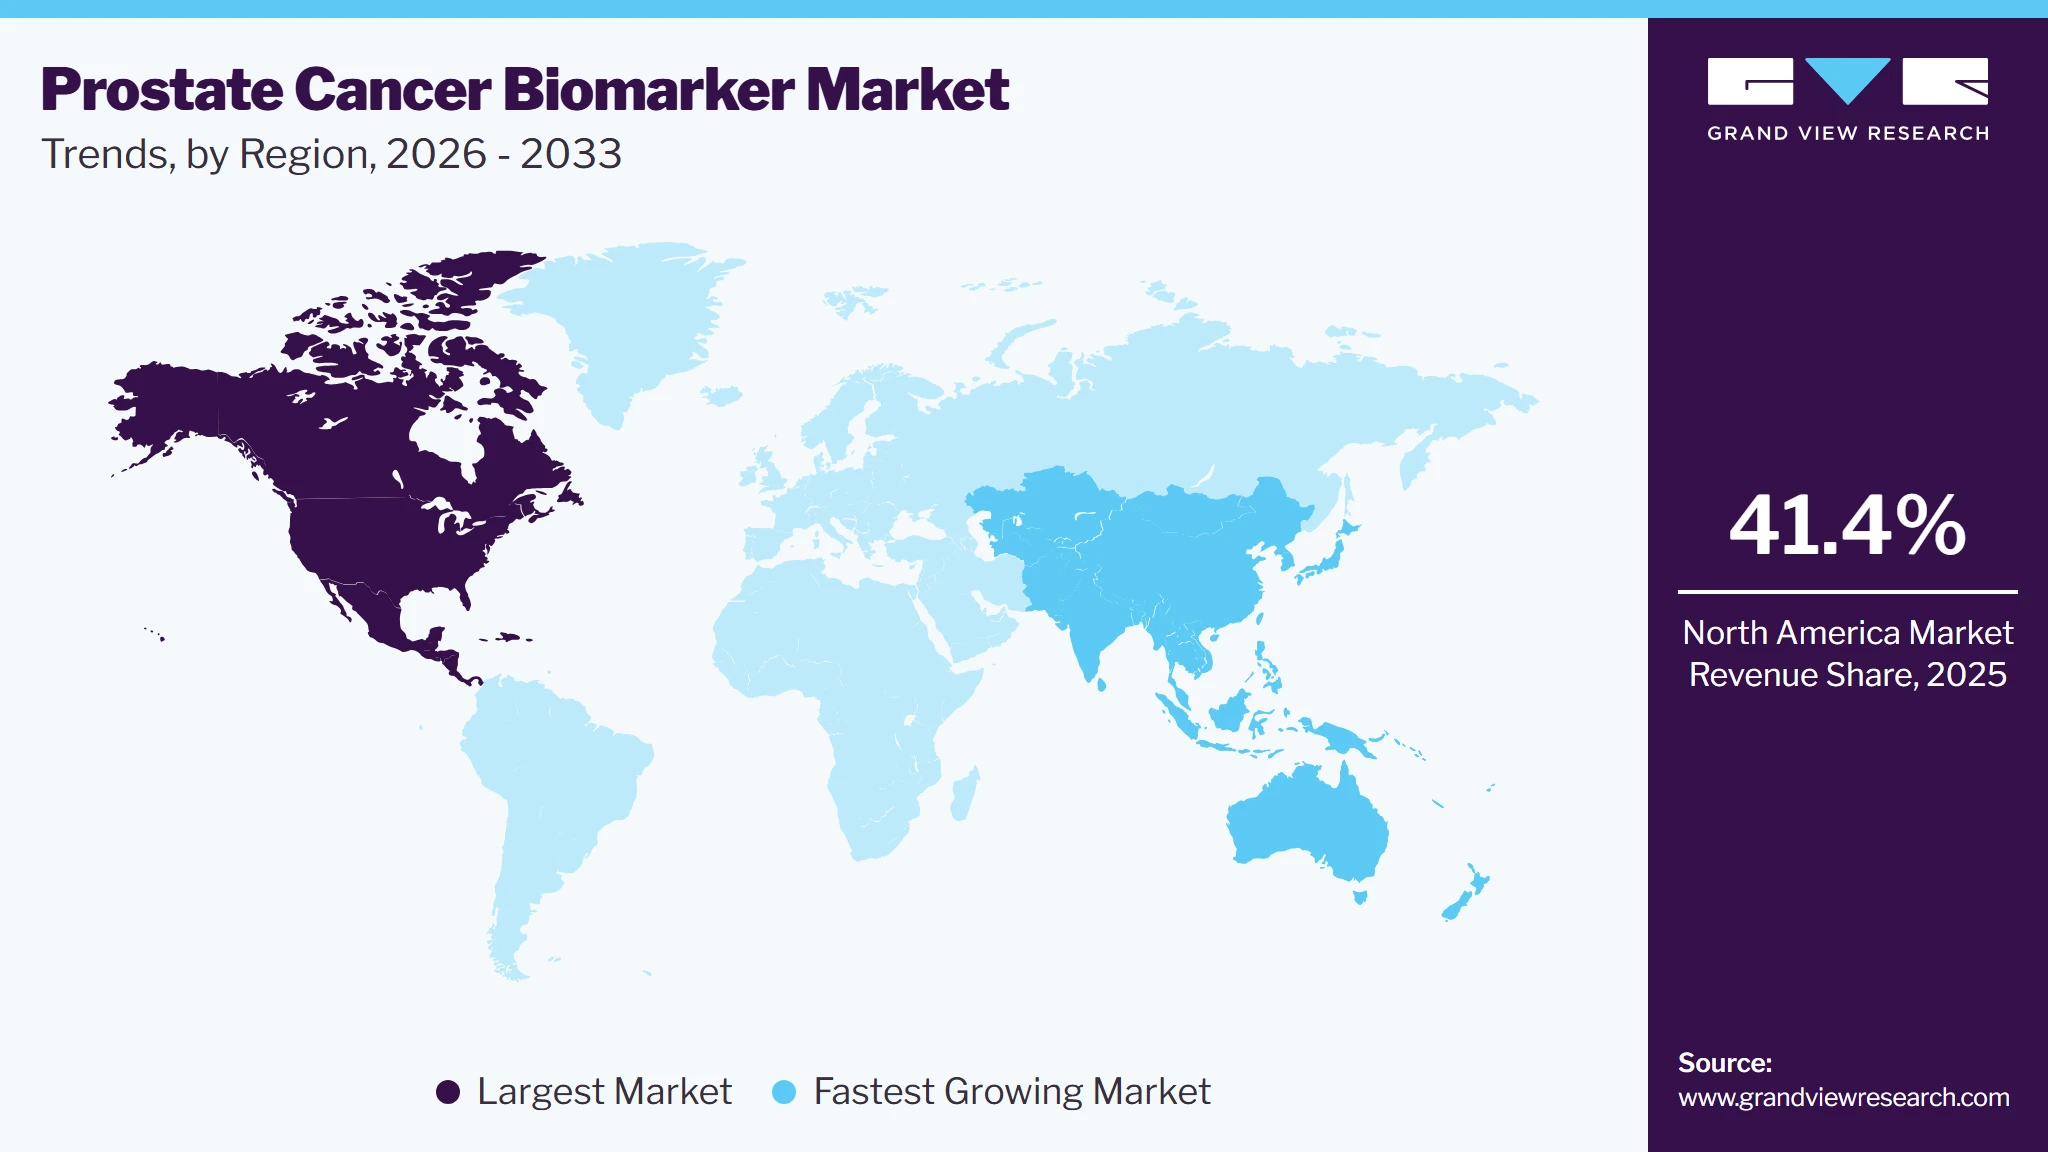
The global prostate cancer biomarker market size was valued at USD 5.3 billion in 2025 and is projected to grow from USD 6.0 billion in 2026 to USD 14.5 billion by 2033, growing at a CAGR of 13.5% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 41.4% in 2025. Some of the major factors expected to drive the market are the rising incidence of prostate cancer and increasing awareness among physicians & patients regarding early detection.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Protein biomarkers segment led the market with the largest revenue share of 57.4% in 2025.
- By application: Screening and early detection segment led the market with the largest share of 44.9% in 2025.
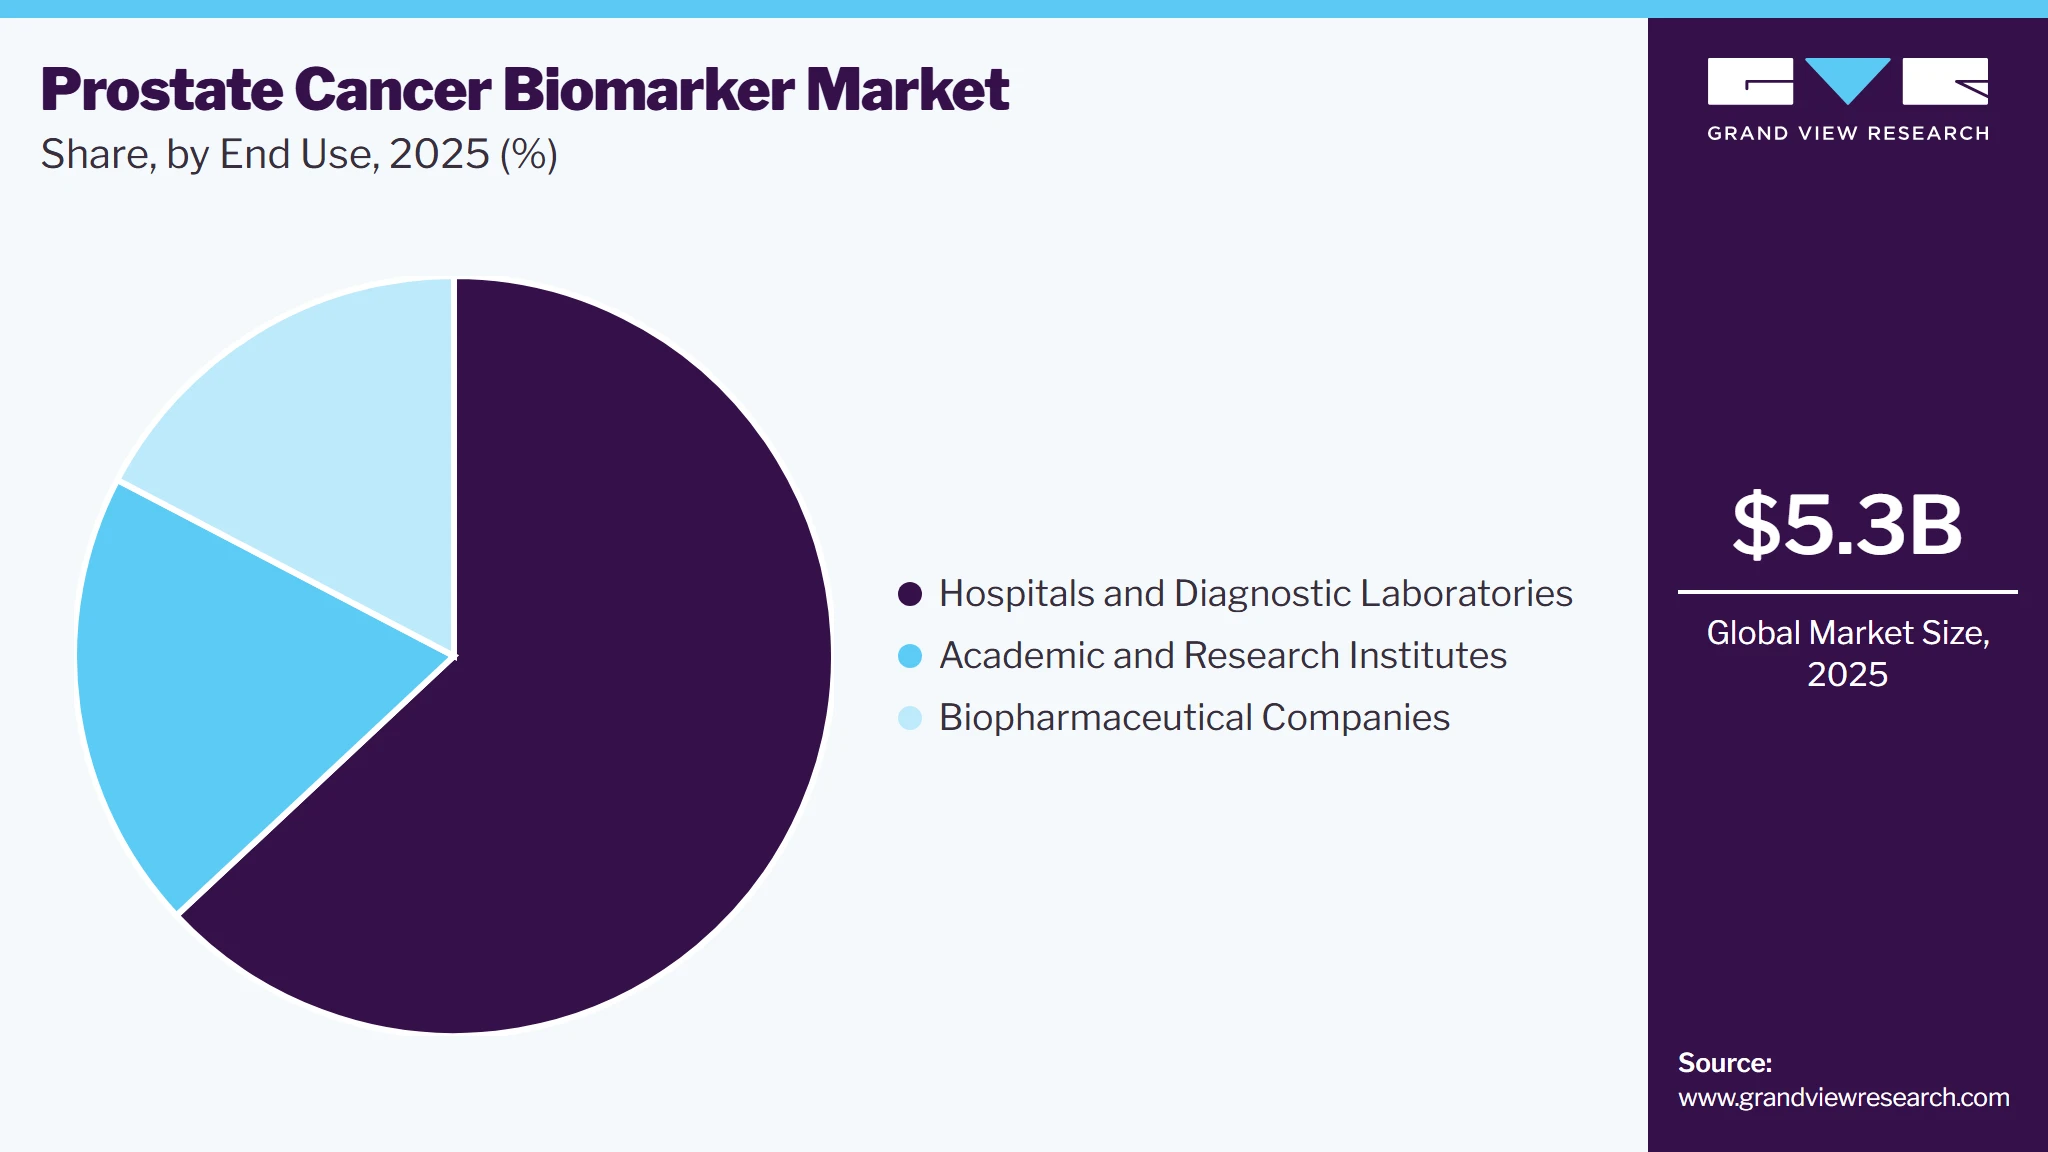
- By end-use: Hospitals and diagnostic laboratories segment led the market with the largest share of 63.0% in 2025.
Regional Highlights
- Largest regional market: North America (41.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.3 Billion
- Estimated market size in 2026: USD 6.0 Billion
- Projected market size by 2033: USD 14.5 Billion
- CAGR (2026-2033): 13.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Furthermore, advancements in biomarker technologies and growing research efforts for prostate cancer diagnosis & treatment are further propelling the overall market. The demand for prostate cancer biomarkers is rising due to the need for accurate and early-stage disease detection and the growing adoption of precision medicine. Factors such as the increasing application of biomarkers in targeted therapies and the development of minimally invasive diagnostic techniques further drive market expansion. Regulatory authorities emphasize the importance of biomarker-based diagnostic tools for improving clinical outcomes, leading to greater biomarker validation and standardization investment.
 To learn more about this report, Download Free Sample Report
Advancements in genomic, proteomic, and metabolomic technologies are enhancing the efficiency and accuracy of prostate cancer biomarker detection. Genomic biomarkers, including PCA3 and TMPRSS2-ERG, improve early diagnosis, while proteomic markers such as PSA and Prostate Health Index (PHI) refine risk stratification. Metabolomic approaches are gaining attention for their potential to distinguish aggressive from indolent prostate cancer. With growing awareness of biomarker-driven diagnostic and prognostic applications, the demand for highly specific and validated prostate cancer biomarkers is expected to continue expanding.
The increasing focus on biomarker-driven diagnostics is transforming prostate cancer detection and management. Advanced biomarker assays contribute to improved risk stratification and support personalized treatment approaches. In January 2025, OncoAssure Ltd announced the clinical validation of its biopsy-based test, OncoAssure Prostate, designed to enhance risk assessment for prostate cancer recurrence. The study, published in BJUI Compass, demonstrated the test’s ability to distinguish between aggressive and low-risk prostate cancers, supporting more precise treatment decisions. These advancements underscore the growing role of biomarker-based diagnostics in improving clinical outcomes and guiding more effective prostate cancer management strategies.
Table below presents Prostate Cancer Biomarkers Clinical Trials
Biomarker
Clinical trial phase
Type of cancer
Patients included
Clinical trial ID
TMPRSS2-ERG
Phase II
mCRPC and recurrent PCa
148
NCT01576172
Phase II
Recurrent PCa, stage IV PCa
29
NCT00330161
Phase II
Prostatic adenocarcinoma
148
NCT01682772
Phase I
Advanced or metastatic PCa
113
NCT00749502
Phase I
High risk PCa
65
NCT02588404
Phase I
Localized or locally advanced PCa, biochemical recurrent PCa
84
NCT03421015
Phase II
High risk PCa
208
NCT02573636
TP53
Phase III
mCRPC
750
NCT03903835
Phase I/II
Prostatic neoplasia
36
NCT00900614
Phase III
Localized PCa
7,776
NCT00001469
Phase I
Localized or locally advanced PCa, biochemical recurrent PCa
84
NCT03421015
AR
Phase I
Hormone refractory PCa
140
NCT00510718
Phase II
PCa
45
NCT01990196
Phase II
Recurrent PCa
42
NCT03311555
Phase I
mCRPC
58
NCT01516866
Phase II
Metastatic PCa, CRPC
60
NCT04090528
Phase I
PCa
40
NCT02411786
Phase II
mCRPC
8
NCT02379390
Phase II
Biochemical recurrent PCa
90
NCT01790126
Phase II
Advanced hormone dependent PCa
90
NCT01861236
BRCA2
Phase II
High risk PCa
100
NCT02154672
Phase III
mCRPC
408
NCT03075735
Phase III
Genetic predisposition to PCa
1,700
NCT00261456
Phase II
mCRPC
40
NCT04038502
Phase II
mCRPC
70
NCT03012321
Phase III
mCRPC
387
NCT02987543
PTEN/P13K/AKT/mTOR
Phase II
High risk PCa
208
NCT02573636
Phase III
CRPC
120
NCT03580239
Phase II
PCa previously treated
108
NCT01251861
Phase I
PCa previously treated with enzalutamide
36
NCT03310541
Phase I
Stage III and IV PCa
62
NCT01480154
Phase II
mCRPC
9
NCT02091531
MGMT
NA
NA
NA
NA
DNMT1
Phase I
mCRPC
19
NCT05037500
NA
Prostatic adenocarcinoma
19
NCT01118741
Phase III
Prostatic adenocarcinoma
80
NCT03535675
Phase I
Adenocarcinoma of the Prostate, Recurrent PCa, Stage I, IIA, IIB, III and IV PCa
32
NCT01912820
Phase I/II
Prostate Carcinoma
NA
NCT03709550
JMJD3
NA
NA
NA
NA
KDM4B
NA
NA
NA
NA
CDK9
Phase I
Castrate Resistant Prostate Cancer
100
NCT05159518
SF3B2
NA
NA
NA
NA
AR-V7
Phase III
Castrate Resistant Prostate Cancer
953
NCT02438007
AR-V3
NA
NA
NA
NA
HDAC6
NA
NA
NA
NA
PRUNE2
NA
NA
NA
NA
Circulating tumor cells
NA
Prostate Cancer Obesity
67
NCT02453139
Phase II
Patients with PSA 4–10 ng/mL
500
NCT03488706
Phase II
Localized PCa
200
NCT01961713
Phase II
mCRPC
11
NCT00887640
Phase II
Advanced PCa
24
NCT02552394
Phase II
mCRPC
140
NCT03050866
Phase I
PCa
60
NCT02450435
cell-free DNA
Phase III
Metastatic PCa
1038
NCT00134056
Phase I
PCa
12
NCT04081428
Phase II
Metastatic PCa
300
NCT02853097
Phase II
PCa
68
NCT02941029
Phase II
PCa
30
NCT03284684
Extracellular vesicles
NA
PCa
108
NCT04298398
miRNAs
Phase II
mCRPC
40
NCT02471469
Phase II
mCRPC
46
NCT04188275
Phase III
High risk PCa
300
NCT01220427
Phase I
PCa
240
NCT03911999
Phase I
PCa
60
NCT02366494
lncRNAS
NA
Prostatic neoplasia
507
NCT01024959
Market Dynamics
The prostate cancer biomarker market is witnessing steady growth driven by the rising incidence of prostate cancer, increasing adoption of precision medicine, and advancements in molecular diagnostics and liquid biopsy technologies. Growing demand for early detection, risk stratification, treatment selection, and disease monitoring is accelerating the use of genomic and protein biomarkers across clinical settings. However, high testing costs, reimbursement challenges, and the need for extensive clinical validation continue to limit adoption. Ongoing innovations in AI-assisted biomarker analysis, next-generation sequencing (NGS), companion diagnostics, and minimally invasive testing are expected to create significant long-term growth opportunities.
The increasing global burden of prostate cancer is a major driver of the prostate cancer biomarker market. Rising disease incidence, aging populations, and greater awareness of early cancer detection are encouraging healthcare providers to adopt biomarker-based diagnostics for screening, risk stratification, treatment selection, and disease monitoring. Biomarkers such as prostate-specific antigen (PSA), PCA3, TMPRSS2:ERG, circulating tumor DNA (ctDNA), and genomic signatures are increasingly being incorporated into clinical workflows to improve diagnostic accuracy while reducing unnecessary biopsies.
Recent clinical guideline updates continue to strengthen biomarker adoption. According to the American Cancer Society (ACS), approximately 313,780 new prostate cancer cases and 35,770 deaths are expected in the U.S. in 2025, making prostate cancer the most frequently diagnosed cancer among men excluding skin cancers. Furthermore, the National Comprehensive Cancer Network (NCCN) continues to recommend the use of validated genomic biomarkers alongside PSA testing to improve clinical decision-making for localized and advanced prostate cancer, supporting increasing demand for advanced biomarker assays.
Despite significant technological advancements, widespread adoption of advanced prostate cancer biomarkers remains constrained by high testing costs and inconsistent reimbursement across healthcare systems. Genomic assays, liquid biopsy tests, and molecular profiling often require sophisticated laboratory infrastructure and specialized expertise, increasing overall diagnostic expenses. Limited reimbursement coverage for newer biomarker assays in several countries further restricts access, particularly in community healthcare settings and emerging markets.
Clinical implementation is also affected by variability in physician adoption and differences in healthcare policies. While organizations such as the American Urological Association (AUA) and NCCN recognize the value of genomic biomarkers for selected patients, reimbursement eligibility differs among insurers and healthcare systems. Additionally, many molecular tests require extensive clinical validation before routine use, slowing commercialization and increasing development costs for diagnostic manufacturers.
The growing adoption of liquid biopsy technologies presents a significant opportunity for the prostate cancer biomarker market. Blood- and urine-based biomarker assays provide minimally invasive alternatives to tissue biopsies for early detection, recurrence monitoring, treatment response evaluation, and identification of actionable genomic alterations. Advances in next-generation sequencing (NGS), circulating tumor DNA (ctDNA) analysis, exosomal RNA biomarkers, and artificial intelligence are improving diagnostic sensitivity while supporting personalized treatment strategies.
Several recent initiatives highlight this trend. In 2024, the U.S. Food and Drug Administration (FDA) continued expanding approvals and indications for companion diagnostics and molecular profiling assays supporting precision oncology across multiple cancers, including prostate cancer applications. Additionally, the National Cancer Institute (NCI) continues supporting research into liquid biopsy technologies and AI-driven biomarker discovery through precision oncology programs aimed at improving early detection and individualized treatment planning. These advancements are expected to accelerate adoption of next-generation biomarker platforms over the coming years.
Market Concentration & Characteristics
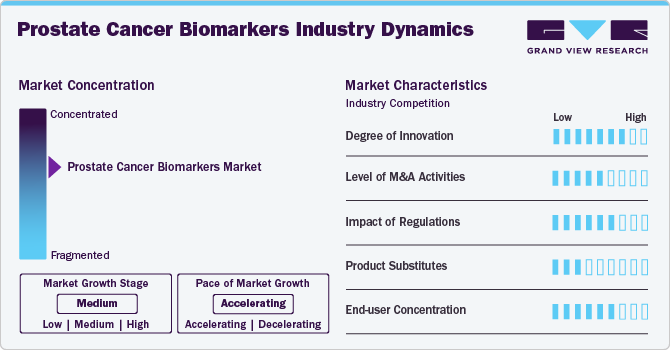
The degree of innovation in prostate cancer biomarkers is advancing rapidly, driving improvements in early detection, risk assessment, and personalized treatment strategies. Emerging biomarkers such as PCA3, TMPRSS2-ERG fusion, and the Prostate Health Index (PHI) enhance diagnostic accuracy beyond traditional PSA testing. Innovations in liquid biopsy technologies, such as circulating tumor cells (CTCs) and extracellular vesicles, provide non-invasive options for real-time monitoring of disease progression. In addition, artificial intelligence (AI)-driven biomarker analysis is refining predictive models, enabling more precise identification of aggressive versus indolent prostate cancer. These advancements are transforming clinical decision-making, optimizing therapeutic approaches, and improving patient outcomes while reducing unnecessary interventions.
The level of mergers and acquisitions (M&A) in the prostate cancer biomarkers industry is moderate but steadily rising as companies seek to expand their diagnostic capabilities and strengthen their biomarker portfolios. Several diagnostic and biotech firms engage in strategic acquisitions to access novel biomarker technologies, proprietary assays, and advanced molecular platforms. Collaborations between diagnostic and precision medicine firms are also shaping the competitive landscape, reflecting a growing interest in integrated biomarker solutions for prostate cancer. While large-scale acquisitions remain limited, targeted M&A efforts increasingly focus on enhancing expertise in genomics, liquid biopsy, and AI-based analytics for prostate cancer diagnostics.
 To learn more about this report, Download Free Sample Report
Regulatory frameworks significantly influence the development, approval, and commercialization of prostate cancer biomarkers. Authorities such as the FDA (U.S.), EMA (Europe), and PMDA (Japan) enforce rigorous standards to ensure biomarker accuracy, analytical reliability, and clinical relevance. The FDA’s Biomarker Qualification Program offers a structured path for biomarker acceptance but requires robust evidence, which can extend the time to market. Similarly, the EU’s In Vitro Diagnostic Regulation (IVDR) has reclassified many diagnostic tests, increasing the burden of documentation and compliance for prostate cancer biomarker developers. In parallel, regulations such as HIPAA in the U.S. and GDPR in Europe govern patient data used in biomarker research, impacting study design and data accessibility. These evolving requirements shape innovation timelines and influence the strategic direction of diagnostic development.
The market faces competition from several conventional and emerging diagnostic approaches. Traditional methods such as digital rectal examination (DRE), prostate-specific antigen (PSA) testing, and multiparametric MRI (mpMRI) continue to serve as primary tools in prostate cancer screening and diagnosis. These techniques, while accessible and cost-effective, often lack the precision of newer biomarker-based tests. In addition, tissue biopsies and genomic profiling—when used without biomarker integration—can offer diagnostic insights but may not fully support risk stratification or treatment personalization. In cost-sensitive healthcare systems, the reliance on these established tools may limit the adoption of newer biomarker technologies, particularly where reimbursement frameworks are not well aligned with advanced diagnostics.
The market is expanding geographically due to rising investments in cancer diagnostics, increasing awareness of early detection, and ongoing research efforts. In North America, the use of biomarker-based tests is supported by established screening programs, access to advanced technologies, and regulatory initiatives. Europe is witnessing steady growth through government-backed cancer research and public health strategies. In Asia-Pacific, awareness and adoption of these tests are growing as healthcare systems improve and research activities increase in countries such as China, Japan, and India. Latin America and the Middle East are gradually adopting biomarker diagnostics with support from improvements in healthcare infrastructure and focused efforts to enhance cancer detection, contributing to broader market growth across regions.
Analyst Perspective
The Prostate Cancer Biomarker Market is expected to witness robust growth, driven by increasing prostate cancer incidence, expanding adoption of precision oncology, and continuous advancements in molecular diagnostics and liquid biopsy technologies. Market participants should focus on developing highly sensitive genomic, proteomic, and cell-based biomarker assays that improve early detection, risk stratification, treatment selection, and disease monitoring. Strengthening collaborations with hospitals, cancer centers, diagnostic laboratories, academic institutions, and biopharmaceutical companies will be essential to accelerate clinical adoption and companion diagnostic development. Companies should also invest in AI-enabled biomarker interpretation, next-generation sequencing (NGS), and minimally invasive testing platforms while generating strong clinical evidence to support reimbursement and regulatory approvals. Expanding access to cost-effective biomarker testing in emerging markets and integrating biomarkers into personalized treatment pathways will create significant long-term growth opportunities and strengthen competitive positioning.
Type Insights
Based on type, the protein biomarkers segment led the market with the largest revenue share of 57.4% in 2025. Protein biomarkers are essential in prostate cancer diagnostics, enabling early detection and monitoring of disease progression by identifying abnormal protein expression patterns. The rising demand for personalized medicine and targeted therapies drives the adoption of protein-based diagnostic tools. Technological advancements such as mass spectrometry and immunoassays have improved the accuracy and efficiency of protein analysis in biological fluids like blood and urine. These developments support broader clinical adoption and research applications, strengthening the segment’s contribution to the market.
Metabolomic biomarkers are expected to grow fastest, with a CAGR of 14.4% over the forecast period. The rising interest in understanding metabolic changes associated with prostate cancer is driving the growth of this segment. Metabolomic biomarkers provide insights into disease mechanisms by analyzing small molecule profiles in biofluids such as urine, serum, and plasma. These markers support early detection and offer the potential for distinguishing aggressive from indolent cancer forms. Advances in analytical techniques like NMR spectroscopy and mass spectrometry have improved the detection and quantification of metabolic changes. Growing investments in precision oncology and increasing use of metabolomics in research and clinical trials are further accelerating the segment’s expansion.
Applications Insights
Based on application, the screening and early detection segment led the market with the largest revenue share of 44.9% in 2025. This segment's growth is driven by the rising need for timely identification of prostate cancer to improve treatment outcomes and reduce disease burden. Biomarkers play a vital role in detecting cancer at an early stage, often before symptoms appear, allowing for more effective and less invasive interventions. Integrating biomarker-based tests in routine health check-ups and screening programs is increasing across hospitals and diagnostic centers. Advances in non-invasive testing methods, such as liquid biopsies and multiplex assays, also improve detection accuracy and patient compliance. These developments support the growing adoption of biomarkers in prostate cancer screening and early diagnosis.
Companion diagnostics is expected to grow fastest at a CAGR of 14.8% over the forecast period. This segment is gaining traction due to the increasing need for personalized treatment strategies in prostate cancer management. Companion diagnostics help identify patients most likely to benefit from targeted therapies based on specific biomarker profiles. These tools improve treatment accuracy and reduce the risk of adverse effects by guiding therapeutic decisions. Advances in molecular testing and regulatory support for precision medicine drive the development and approval of companion diagnostic tests. With more targeted therapies entering the market, the demand for reliable biomarker-based companion diagnostics is expected to grow steadily, supporting this segment’s expansion.
End Use Insights
Based on end-use, the hospitals and diagnostic laboratories segment led the market with the largest revenue share of 63.0% in 2025. These facilities are central to adopting and applying prostate cancer biomarkers, as they handle large volumes of diagnostic testing and patient monitoring. Their role in early detection, treatment planning, and ongoing disease surveillance supports the growing use of biomarker-based diagnostics. With advancements in clinical workflows and access to improved testing platforms, hospitals, and labs can process biomarker tests faster and more accurately. The emphasis on personalized care and integration of molecular diagnostics into routine practice continues to strengthen the position of this segment in the market.
 To learn more about this report, Download Free Sample Report
Academic and research institutes are expected to grow at the fastest CAGR of 14.7% over the forecast period. These institutions are actively involved in discovering and validating prostate cancer biomarkers, contributing significantly to translational research and clinical innovation. With strong academic networks and access to research funding, they are advancing biomarker studies through collaborative projects and clinical trials. The increasing focus on personalized medicine and precision diagnostics encourages the adoption of novel biomarkers in academic research. Moreover, partnerships with healthcare providers and biotech firms help translate research findings into practical diagnostic tools, supporting the segment's steady growth.
Regional Insights
North America prostate cancer biomarker market accounted for the largest revenue share of 41.4% in 2025. The increasing recognition of biomarkers in guiding prostate cancer diagnostics and therapy decisions contributes to market expansion. In addition, strong support from local regulatory agencies is helping facilitate the development and validation of biomarker-based tests. These agencies are actively involved in promoting awareness of precision medicine and its role in improving prostate cancer outcomes, which is encouraging broader adoption across healthcare systems in the region.
 To learn more about this report, Download Free Sample Report
U.S. Prostate Cancer Biomarkers Market Trends
The prostate cancer biomarker market, U.S. held the largest share in the North America region in 2025, driven by advanced healthcare infrastructure, significant research funding, and the increasing adoption of biomarker-based diagnostics. The market is bolstered by high awareness and institutional support for early detection and precision medicine in prostate cancer care. Research organizations and academic institutions actively engage in studies to validate novel biomarkers, enhancing clinical confidence in these diagnostic tools.
For instance, in February 2022, Datar Cancer Genetics Inc. received the U.S. Food and Drug Administration's Breakthrough Device Designation for its 'TriNetra-Prostate blood test, designed to detect early-stage prostate cancer. This test demonstrated high accuracy (>99%) without false positives and requires only a 5 mL blood sample. It is indicated for males aged 55-69 years with serum PSA of 3 ng/mL or higher. The test identifies prostate adenocarcinoma-specific Circulating Tumor Cells (CTCs) in the blood, potentially reducing the need for invasive biopsies among individuals with benign prostate conditions and improving detection rates among those with prostate cancer.
Europe Prostate Cancer Biomarkers Market Trends
The Europe prostate cancer biomarkers market is growing steadily with rising awareness about early cancer detection and personalized treatment. Governments across countries such as Germany, France, and the UK are supporting research and encouraging the use of advanced diagnostic tools. The European Medicines Agency (EMA) is helping by providing clear guidelines supporting biomarkers' use in drug development. Research partnerships across universities, hospitals, and companies are also helping discover new and more accurate biomarkers. With better access to non-invasive tests like liquid biopsies and wider insurance coverage, the use of prostate cancer biomarkers is gradually increasing across the region.
The prostate cancer biomarkers market in France is growing with support from national research programs and strong public-private partnerships. The government has invested in projects focused on improving cancer diagnostics, helping research centers like Inserm work closely with biotech companies. There is also a push to use digital tools and artificial intelligence in labs to make biomarker testing faster and more accurate. France’s well-developed clinical trial network and partnerships with international pharmaceutical companies are also helping expand access to advanced biomarker-based tests. This progress supports early detection and more personalized treatment approaches across the country.
The prostate cancer biomarkers market in Germany is showing steady growth due to strong research capabilities, well-established healthcare systems, and rising interest in early cancer detection. Government-backed programs and partnerships between universities, hospitals, and diagnostic companies support developing and using biomarker-based tests. The German Cancer Research Center (DKFZ) plays a key role in promoting biomarker research through national initiatives focused on precision oncology. There is growing use of genetic and protein-based biomarkers in hospitals to improve diagnosis and treatment planning for prostate cancer. Ongoing clinical studies and access to advanced lab technologies are also helping expand the market. These factors contribute to the wider adoption of prostate cancer biomarkers nationwide.
Asia Pacific Prostate Cancer Biomarkers Market Trends
The Asia Pacific prostate cancer biomarkers market is expected to register the fastest CAGR of 14.4% during the forecast period, supported by a growing aging population, rising cancer awareness, and greater emphasis on early diagnosis. Countries such as Japan, China, and South Korea are making notable progress in biomarker research through public health initiatives and institutional collaborations. Japan focuses on improving non-invasive diagnostics, while China is strengthening its biomarker testing capabilities through increased R&D investments.
India is also witnessing a gradual shift toward personalized medicine, with hospitals and diagnostic centers adopting biomarker-based approaches for improved disease detection. With healthcare infrastructure improving and clinical research activities expanding across the region, biomarker integration in prostate cancer diagnostics is expected to gain more traction.
The Japan prostate cancer biomarkers market is expanding with growing awareness of early detection and personalized cancer care. The country’s aging population and focus on precision medicine have encouraged research on genetic and protein-based biomarkers. National institutions such as RIKEN and the National Cancer Center are supporting studies aimed at improving prostate cancer diagnosis through non-invasive biomarker tests. The Pharmaceuticals and Medical Devices Agency (PMDA) is streamlining the approval of innovative diagnostics, which is helping more hospitals and labs adopt these technologies. This supportive environment contributes to steadily adopting prostate cancer biomarkers across Japan.
Latin America Prostate Cancer Biomarkers Market Trends
Latin America prostate cancer biomarkers market is growing with better access to diagnostic services and increasing efforts in cancer awareness. Countries such as Brazil, Mexico, and Argentina focus on early detection strategies through biomarker-based testing. In Brazil, research centers like Fiocruz support the development of diagnostic tools to improve prostate cancer outcomes. Mexico is encouraging academic and private sector partnerships to enhance biomarker research, while Argentina’s CONICET is contributing to studies on genetic and protein markers for cancer detection. These regional efforts and gradual improvements in healthcare infrastructure are helping expand the prostate cancer biomarkers market across Latin America.
The prostate cancer biomarkers market in Brazil is progressing with support from national research institutions, growing awareness, and efforts to improve early cancer detection. Organizations such as Fiocruz and the University of São Paulo are involved in biomarker research focused on improving diagnostic accuracy and treatment planning for prostate cancer. Government funding bodies like FAPESP and CAPES are encouraging research in precision medicine, contributing to local innovation. Collaborations between public hospitals and biotech firms are also helping expand access to biomarker-based diagnostics. These combined efforts are driving the adoption of prostate cancer biomarkers across Brazil’s healthcare sector.
Middle East & Africa Prostate Cancer Biomarkers Market Trends
The prostate cancer biomarkers market in the Middle East & Africa is gradually expanding with increasing efforts to improve early cancer detection, modernize healthcare systems, and promote research in precision oncology. Countries like Saudi Arabia and the UAE support prostate cancer diagnostics through national health strategies and collaborations with global institutions. Saudi Arabia’s Vision 2030 encourages investment in biomarker-based innovations, including those focused on prostate cancer. In Africa, institutions like the University of Cape Town are exploring biomarker applications to enhance prostate cancer diagnosis and treatment planning. While these developments create opportunities, challenges such as limited access to specialized testing and uneven research funding continue to affect wider market adoption.
The prostate cancer biomarkers market in Saudi Arabia is expanding with a growing emphasis on early cancer detection, precision medicine, and healthcare modernization. National health programs under Vision 2030 prioritize research and innovation in oncology, creating a favorable environment for biomarker-based diagnostics. Government-backed institutions such as King Faisal Specialist Hospital and Research Centre are involved in developing and validating prostate cancer biomarkers for clinical use. Additionally, partnerships with international research organizations are helping advance diagnostic capabilities. These efforts, along with improved access to laboratory infrastructure and a strong focus on personalized care, are contributing to the growth of the prostate cancer biomarkers market in the country.
Key Prostate Cancer Biomarkers Company Insights
Major market players engage in various strategies, such as distribution agreements, mergers and acquisitions, and expansions. Most crucially, they exhibit a high degree of innovation in product research and development to improve their market penetration.
Key Prostate Cancer Biomarkers Companies
The following key companies have been profiled for this study on the prostate cancer biomarkers market.
-
Exact Sciences Corporation
-
Myriad Genetics, Inc.
-
Bio-Techne
-
ExoDx
-
OPKO Health,Inc.
-
mdxhealth
-
Veracyte, Inc.
-
Beckman Coulter, Inc.
-
Nucleix
-
DiaCarta
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well-Established Players (Roche Diagnostics, Thermo Fisher Scientific, Bio-Techne, Exact Sciences, Myriad Genetics, QIAGEN, Illumina)
Focus on expanding prostate cancer biomarker portfolios through next-generation sequencing (NGS), liquid biopsy platforms, genomic assays, protein biomarker tests, companion diagnostics, AI-assisted biomarker interpretation, and integrated bioinformatics solutions. Emphasize collaborations with hospitals, cancer centers, diagnostic laboratories, academic institutions, and pharmaceutical companies while investing in assay development, clinical validation, regulatory approvals, and global commercialization through strategic partnerships, acquisitions, and continuous product innovation.
Strong global commercial presence, established molecular diagnostics portfolios, advanced sequencing technologies, extensive regulatory expertise, comprehensive bioinformatics capabilities, and significant R&D investments. Integrated offerings comprising sequencing platforms, biomarker assays, reagents, software, laboratory services, and companion diagnostics enable high diagnostic accuracy, operational efficiency, and widespread adoption across prostate cancer screening, precision oncology, and treatment monitoring.
High R&D expenditure, increasing regulatory compliance costs, reimbursement variability across regions, dependence on clinical guideline updates, and continuous investment required to maintain technological leadership. Large organizations may also experience longer product development timelines, pricing pressure, and complex global supply chain management.
Emerging & Regional Players (MDxHealth, Genomic Health, Veracyte, OPKO Health, Proteomedix, regional molecular diagnostics laboratories)
Focus on innovative genomic and protein biomarker assays, liquid biopsy technologies, AI-enabled biomarker analytics, affordable molecular diagnostics, and personalized oncology solutions. Emphasize collaborations with hospitals, urology clinics, cancer centers, research institutes, and diagnostic laboratories while strengthening regional distribution, localized laboratory services, customized testing solutions, and clinical research partnerships to improve accessibility and affordability of prostate cancer biomarker testing.
High innovation capability, rapid commercialization of biomarker technologies, competitive pricing, specialized expertise in prostate cancer diagnostics, and agility in adopting emerging molecular technologies. Advanced genomic assays, liquid biopsy platforms, and AI-driven clinical decision support enable faster adoption across early detection, prognosis, treatment monitoring, and precision oncology applications.
Limited global commercial presence, smaller laboratory infrastructure, lower brand recognition, dependence on reimbursement policies and strategic collaborations, and challenges in obtaining regulatory approvals across multiple countries. Emerging companies may also face scalability constraints, limited financial resources, and intense competition from multinational diagnostics companies offering broader oncology and molecular testing portfolios.
Recent Developments
-
In February 2025, Myriad Genetics partnered with PATHOMIQ to exclusively license PATHOMIQ_PRAD, an AI-driven technology platform for prostate cancer, in the U.S. This partnership integrates AI-enabled diagnostics into Myriad's oncology portfolio, supporting more informed treatment decisions before and after prostate cancer therapy. By leveraging advanced artificial intelligence, the collaboration aims to strengthen diagnostic precision in prostate cancer care, aligning with evolving needs in the Prostate Cancer Biomarker market.
-
In February 2024, DiaCarta entered a strategic collaboration with OncoAssure Ltd to commercialize a prostate cancer prognostic test. This 6-gene expression assay evaluates the risk of aggressive disease following diagnosis and estimates the probability of biochemical recurrence within five years post-surgery. The partnership utilizes DiaCarta's clinical diagnostic capabilities to support validation and market expansion of the test, contributing to more tailored prostate cancer management through biomarker-based risk stratification.
Prostate Cancer Biomarkers Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 5.3 billion
Market size value in 2026
USD 6.0 billion
Revenue forecast in 2033
USD 14.5 billion
Growth rate
CAGR of 13.5% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, end-use, regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; and Kuwait
Key companies profiled
Exact Sciences Corporation; Myriad Genetics, Inc.; Bio-Techne; ExoDx; OPKO Health, Inc.; mdxhealth; Veracyte, Inc.; Beckman Coulter, Inc.; Nucleix; DiaCarta; Genomic Health
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Prostate Cancer Biomarker Market Report Segmentation
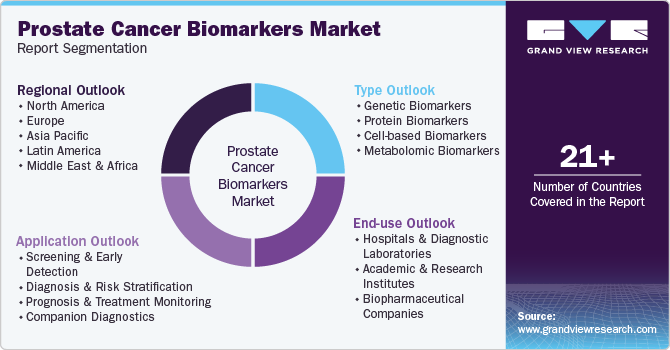
This report forecasts revenue growth and provides an analysis on the market trends in each of the sub-markets from 2021 to 2033. For this study, Grand View Research has segmented the global prostate cancer biomarkers market report on the basis of type, application, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (USD Million; 2021 - 2033)
-
Genetic Biomarkers
-
Protein Biomarkers
-
Cell-based Biomarkers
-
Metabolomic Biomarkers
-
-
Application Outlook (USD Million; 2021 - 2033)
-
Screening and Early Detection
-
Diagnosis and Risk Stratification
-
Prognosis and Treatment Monitoring
-
Companion Diagnostics
-
-
End Use Outlook (USD Million; 2021 - 2033)
-
Hospitals & Diagnostic Laboratories
-
Academic & Research Institutes
-
Biopharmaceutical Companies
-
-
Regional Outlook (USD Million; 2021 - 2033)
-
North America
-
U.S
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
India
-
China
-
Japan
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Argentina
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
Kuwait
-
-
Research Methodology
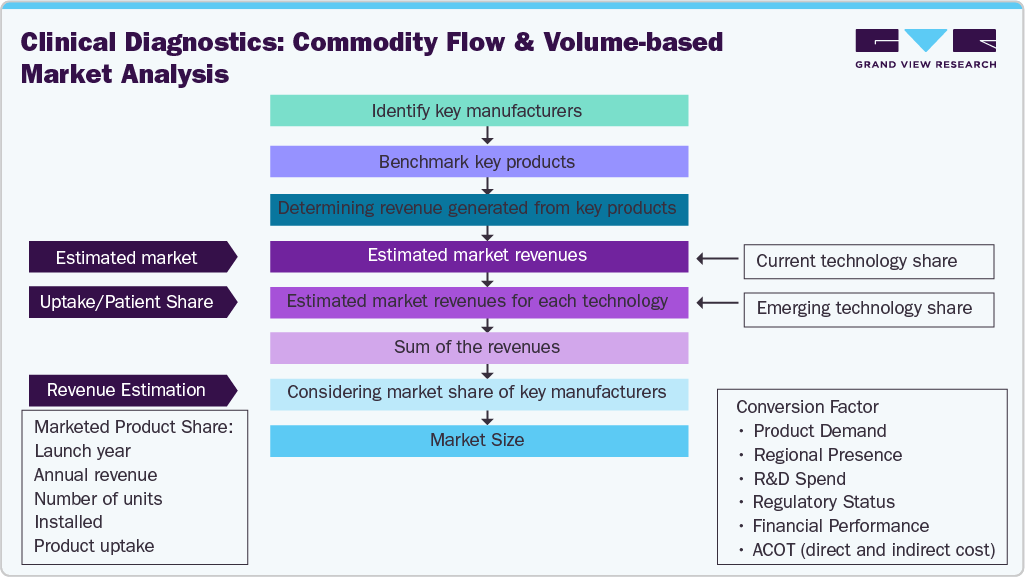
The prostate cancer biomarker market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each prostate cancer biomarker segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Genetic Biomarkers
Revenue generated from genomic biomarker assays detecting inherited or acquired genetic alterations supporting prostate cancer screening, risk assessment, treatment selection, and disease monitoring.
Protein Biomarkers
Revenue generated from protein-based biomarker tests, including PSA and novel protein markers, enabling prostate cancer detection, prognosis, recurrence monitoring, and therapeutic response evaluation.
Cell-based Biomarkers
Revenue generated from circulating tumor cell (CTC) assays and other cell-based diagnostics supporting disease progression assessment, prognosis, precision oncology, and treatment monitoring.
Metabolomic Biomarkers
Revenue generated from metabolomic biomarker assays analyzing metabolic signatures for early prostate cancer detection, disease stratification, treatment response assessment, and personalized clinical management.
Segment - Application
Revenue capture definition
Screening and Early Detection
Revenue generated from biomarker tests used for population screening, early cancer detection, and identification of high-risk individuals requiring further clinical evaluation.
Diagnosis and Risk Stratification
Revenue generated from biomarker assays supporting prostate cancer diagnosis, disease classification, aggressiveness assessment, and personalized clinical risk stratification for treatment planning.
Prognosis and Treatment Monitoring
Revenue generated from biomarker testing used to predict clinical outcomes, monitor disease progression, evaluate therapeutic effectiveness, and detect recurrence following treatment.
Companion Diagnostics
Revenue generated from biomarker assays guiding targeted therapy selection, patient eligibility determination, and precision oncology decisions alongside approved pharmaceutical treatments.
Segment - End Use
Revenue capture definition
Hospitals and Diagnostic Laboratories
Revenue generated from prostate cancer biomarker testing performed in hospitals and diagnostic laboratories for screening, diagnosis, prognosis, treatment monitoring, and precision oncology applications.
Academic and Research Institutes
Revenue generated from biomarker research activities, clinical studies, translational medicine programs, assay validation, and discovery of novel prostate cancer biomarkers.
Biopharmaceutical Companies
Revenue generated from biomarker development supporting drug discovery, companion diagnostics, clinical trials, precision medicine research, and targeted therapy development for prostate cancer.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Prostate Cancer Biomarker Competitive Landscape & Technology Assessment - Genomic Biomarkers, Liquid Biopsy & Precision Oncology
Assessed the global prostate cancer biomarker ecosystem across diagnostic manufacturers, hospitals, cancer centers, urology clinics, diagnostic laboratories, academic research institutes, and biopharmaceutical companies. Evaluated leading developers of genetic, protein, cell-based, and metabolomic biomarkers, next-generation sequencing (NGS) platforms, liquid biopsy technologies, companion diagnostics, AI-assisted biomarker interpretation platforms, and molecular diagnostic assays.
Enabled benchmarking of leading prostate cancer biomarker providers, identified innovation opportunities in liquid biopsy, AI-assisted biomarker analysis, genomic profiling, companion diagnostics, and integrated precision oncology solutions. Evaluated competitive differentiation across molecular diagnostics, disease monitoring, predictive biomarker testing, and personalized treatment portfolios.
Prostate Cancer Biomarker Regulatory, Clinical Guidelines & Reimbursement Assessment
Analyzed evolving regulatory frameworks governing prostate cancer biomarker testing across major global markets, including IVD approvals, laboratory accreditation requirements, clinical validation standards, reimbursement policies, companion diagnostic regulations, and oncology clinical practice guidelines. Assessed the impact of regulatory updates, healthcare reimbursement reforms, biomarker standardization initiatives, and quality assurance requirements on commercialization, clinical adoption, patient access, and testing utilization.
Supported regulatory risk assessment, identified commercialization and reimbursement challenges, evaluated compliance readiness among diagnostic manufacturers and clinical laboratories, and highlighted the impact of evolving regulatory standards, reimbursement frameworks, and clinical guidelines on market growth, biomarker adoption, and competitive positioning within prostate cancer diagnostics.
Frequently Asked Questions About This Report
The global prostate cancer biomarkers market size was valued at USD 5.3 billion in 2025 and is estimated at USD 6.0 billion for 2026.
Some key players operating in the prostate cancer biomarker market include Exact Sciences Corporation; Myriad Genetics, Inc.; Bio-Techne; ExoDx; OPKO Health, Inc.; mdxhealth; Veracyte, Inc.; and Beckman Coulter, Inc
Key factors that are driving the prostate cancer biomarker market growth include rising incidence of prostate cancer and increasing awareness among physicians & patients regarding early detection. Furthermore, advancements in biomarker technologies and growing research efforts for prostate cancer diagnosis & treatment are further propelling the overall market..
The Asia Pacific prostate cancer biomarkers market is expected to register the fastest CAGR during the forecast period, supported by a growing aging population, rising cancer awareness, and greater emphasis on early diagnosis.
Based on type, the protein biomarkers segment led the market with the largest revenue share of 57.4% in 2025.
Based on application, the screening and early detection segment led the market with the largest revenue share of 44.9% in 2025.
The growing adoption of liquid biopsy technologies presents a significant opportunity for the prostate cancer biomarker market. Blood- and urine-based biomarker assays provide minimally invasive alternatives to tissue biopsies for early detection, recurrence monitoring, treatment response evaluation, and identification of actionable genomic alterations.
The global prostate cancer biomarkers market is expected to grow at a CAGR of 13.5% from 2026 to 2033, reaching USD 14.5 billion by 2033.
North America dominated with a 41.4% revenue share in 2025.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


