
- Home
- »
- Biotechnology
- »
-
Research Antibodies Market Size, Share Report, 2026-2033GVR Report cover

Research Antibodies Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Primary, Secondary), By Specificity (Monoclonal, Polyclonal), By Technology (Immunofluorescence, Western Blotting), By Source, By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$1.9BMarket Estimate, 2026
$2.1BMarket Forecast, 2033
$3.9BCAGR, 2026–2033
9.2%Research Antibodies Market Summary
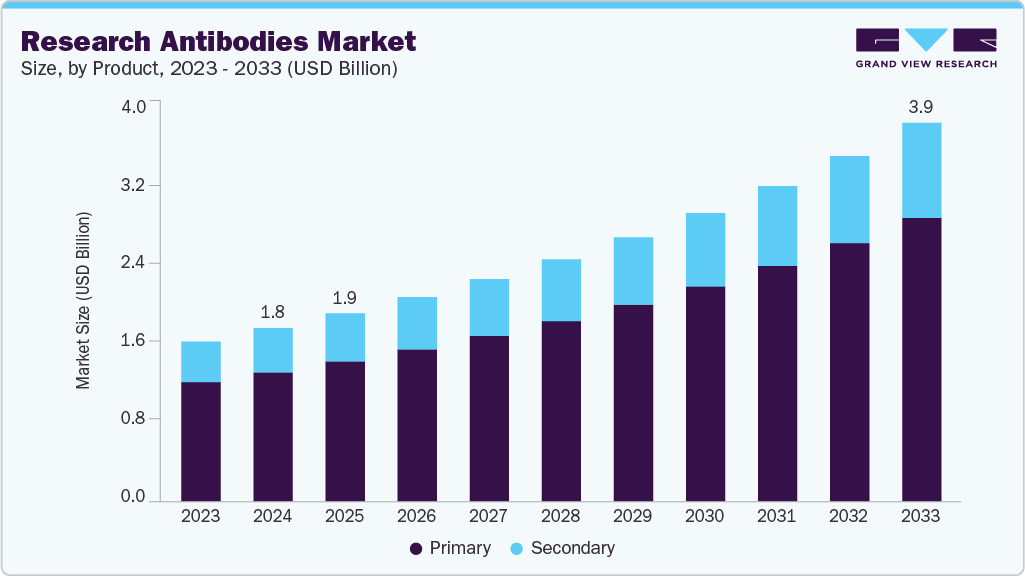
The global research antibodies market size was valued at USD 1.9 billion in 2025 and is projected to grow from USD 2.1 billion in 2026 to USD 3.9 billion by 2033, growing at a CAGR of 9.2% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 40.4% in 2025. The market for research antibodies is expanding rapidly due to the rising incidence of infectious and chronic illnesses, improvements in proteomics and genomics research, and the growing use of personalized medicine.
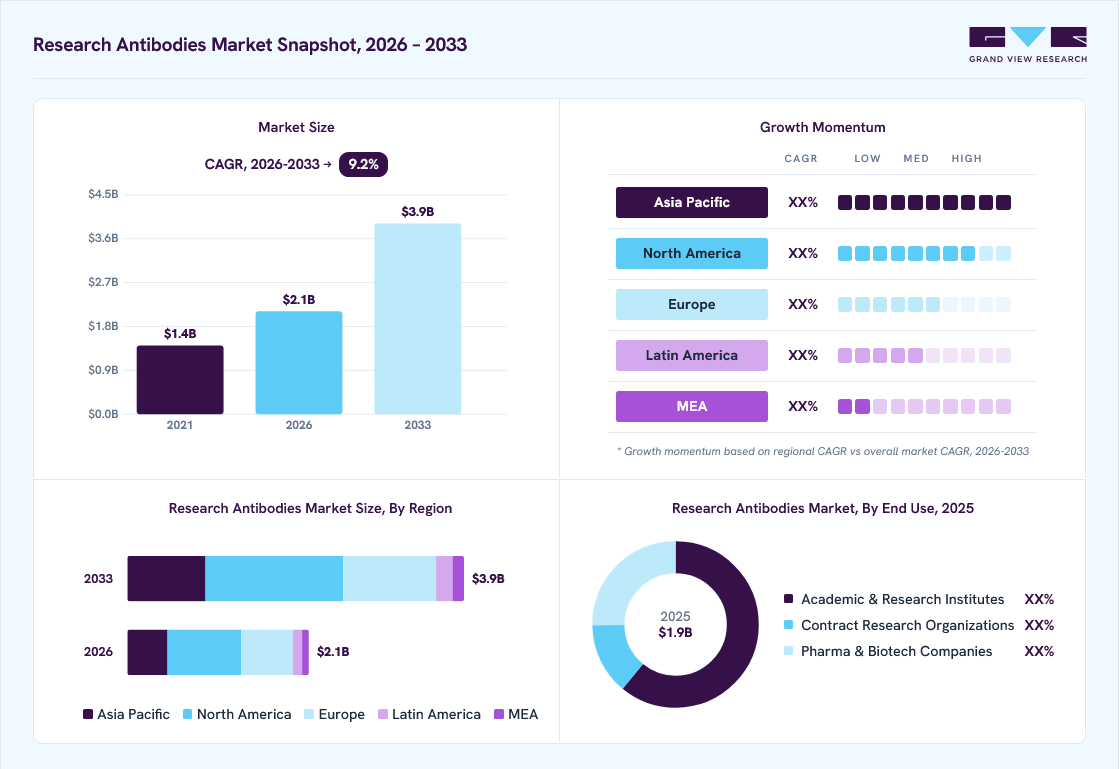 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Primary segment held the largest revenue share of over 74.5% in 2025.
- By specificity: Monoclonal antibodies segment held the largest share of 60.3% in 2025.
- By technology: Western blotting segment held the largest share of 29.7% in 2025.
- By source: Rabbit segment held the largest revenue share of over 50.3% in 2025.
- By application: Oncology segment held the largest revenue share of 32.9% in 2025.
Regional Highlights
- Largest regional market: North America (40.4% revenue share, 2025)
- Fastest-growing regional market: Asia pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.9 Billion
- Estimated market size in 2026: USD 2.1 Billion
- Projected market size by 2033: USD 3.9 Billion
- CAGR (2026-2033): 9.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
Rising burden of chronic and infectious diseases
The growing prevalence of infectious and chronic illnesses worldwide is one of the main factors propelling the growth of the research antibodies industry. The need for cutting-edge research instruments to examine disease pathways and find new therapeutic targets has increased due to the rising prevalence of cancer, cardiovascular diseases, autoimmune diseases, and neurodegenerative conditions. To identify, measure, and examine proteins implicated in disease development, research antibodies are essential tools that help scientists decipher intricate biological processes. For instance, antibodies are widely used in oncology to validate druggable targets, identify tumor markers, and study signaling pathways.
Estimated Number of New Cancer Cases and Deaths by Sex, US, 2025
Cancer Type
Estimated New Cases (2025)
Breast
319,750
Prostate
313,780
Lung & Bronchus
226,650
Colorectal
154,270
Urinary Bladder
84,870
Other
942,590
The continuous threat of infectious diseases, which includes new pathogens like SARS-CoV-2 and seasonal influenza, has also increased demand for research antibodies. In virology and microbiology labs, antibodies are essential for pathogen identification, immune response profiling, and vaccine development. Investment in antibody technologies has increased due to the global COVID-19 pandemic, which highlighted the value of antibody-based assays in therapeutic research and diagnostic testing. Research organizations and pharmaceutical companies are anticipated to increase their reliance on antibodies to spur innovation in preventive and therapeutic solutions due to the emergence of viral outbreaks and antimicrobial resistance, which will sustain market growth over the forecast period.
Expansion of life sciences and biomedical research
One of the main factors propelling the market expansion for research antibodies is the rapid development of biomedical and life sciences research. Research antibodies are widely used by academic institutions, biotechnology companies, and pharmaceutical firms as the emphasis on comprehending intricate cellular and molecular processes grows. Antibodies are indispensable tools in cell biology, molecular biology, and biochemistry, enabling researchers to identify, isolate, and analyze proteins with high specificity and sensitivity.
The role of research antibodies in target validation, lead optimization, and preclinical testing has also been strengthened by the robust pipeline of drug discovery and development programs. Antibodies are being used more and more by biotech and pharmaceutical companies to investigate protein interactions, clarify signaling pathways, and create potential treatments. The constant need for high-quality antibodies is also fueled by the growth of academic-industry partnerships and the construction of cutting-edge research facilities across the globe.
Market Dynamics
The research antibodies market is experiencing significant growth, driven by the increasing demand for high-quality antibodies in life sciences research, drug discovery, and disease diagnostics. The rising prevalence of chronic and infectious diseases, growing research activities in genomics, proteomics, and cell biology, and expanding focus on biomarker discovery and precision medicine are driving market expansion. In addition, increasing investments in biomedical and pharmaceutical R&D, advancements in recombinant antibody technologies, antibody validation methods, and high-throughput screening techniques, coupled with the growing adoption of antibodies in immunology, oncology, and cell and gene therapy research, are expected to further support market growth over the forecast period.
The growing prevalence of chronic diseases, including cancer, cardiovascular diseases, autoimmune disorders, and neurodegenerative diseases, is significantly driving demand for research antibodies. According to the World Health Organization (WHO), 2025, noncommunicable diseases (NCDs) caused approximately 43 million deaths globally in 2021, accounting for nearly 75% of all non-pandemic-related deaths worldwide. In addition, the International Agency for Research on Cancer (IARC) estimated around 20 million new cancer cases and 9.7 million cancer deaths in 2022 and projects global cancer incidence to exceed 35 million cases by 2050, representing an increase of about 77% compared with 2022 levels. This rising disease burden has intensified research efforts to understand disease mechanisms and identify novel therapeutic targets and biomarkers.
Research antibodies are essential tools in disease-focused research and precision medicine initiatives, widely used in protein expression analysis, biomarker discovery, target validation, immunophenotyping, and molecular diagnostics through techniques such as ELISA, Western blotting, immunohistochemistry, and flow cytometry. The growing emphasis on personalized medicine and targeted therapies has further heightened the need for highly specific, well-validated antibodies to identify disease-specific biomarkers and stratify patient populations.
The high cost of high-quality and recombinant antibodies remains a major restraint in the research antibodies market, as the development of highly specific and extensively validated antibodies requires substantial investments in antibody engineering, cell-line development, quality control, and validation studies. Recombinant and carrier-free antibodies are generally priced significantly higher than conventional polyclonal antibodies, increasing the overall cost of research projects. For academic institutions, small biotechnology companies, and laboratories in emerging economies, these high costs can limit access to premium antibodies and constrain the scale of experimental studies.
For example, several recombinant monoclonal antibodies sold through Fisher Scientific's catalog are priced above USD 500 per vial. The Invitrogen Atidortoxumab Recombinant Human Monoclonal Antibody (100 μg) is listed at approximately USD 503.10 per vial, while the B-Raf (V600E) Recombinant Rabbit Monoclonal Antibody (RM8), Invitrogen, is priced at around USD 632.50 per vial. These examples demonstrate the substantial costs of highly validated recombinant antibodies and highlight the financial burden on academic laboratories and smaller biotechnology companies in conducting large-scale proteomics and biomarker research.
The rapid growth of cell and gene therapy, immunotherapy, and precision medicine research presents a significant opportunity for the research antibodies market. The development of advanced therapies, including CAR-T cell therapies, gene-editing technologies, and personalized treatments, requires highly specific antibodies for target identification, biomarker discovery, cell characterization, and quality-control testing. Research antibodies are extensively used in flow cytometry, immunophenotyping, and protein expression analysis to support the development and validation of these therapies.
According to the American Society of Gene & Cell Therapy and the Citeline, the global cell and gene therapy pipeline comprised more than 4,000 therapies in development in 2024, reflecting substantial growth in advanced therapeutic research. The increasing number of clinical-stage cell and gene therapies and rising investments in precision medicine initiatives are expected to create significant demand for high-quality, highly specific, and recombinant research antibodies, thereby offering lucrative growth opportunities for market participants over the forecast period.
Market Concentration & Characteristics
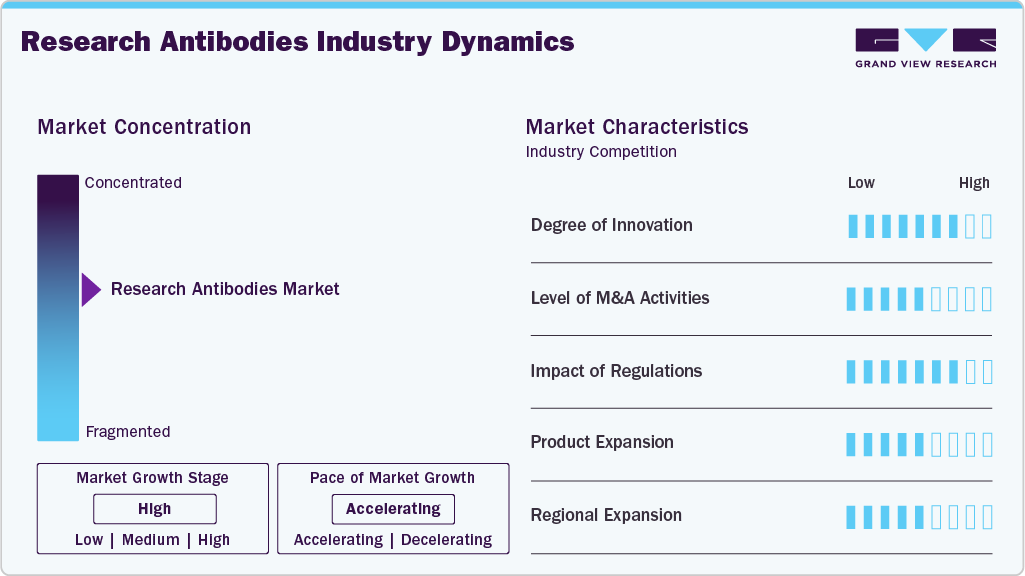
The research antibodies market shows a high degree of innovation, driven by the shift from traditional polyclonal and monoclonal antibodies to recombinant and engineered variants that offer greater specificity and reproducibility. Proteomics, diagnostics, and precision medicine applications are growing thanks to innovations like nanobodies, multiplex assays, and AI-enabled antibody discovery, which make the market dynamic and highly innovative.
Several key players are undertaking mergers and acquisitions in the research antibodies industry to maintain their market presence. For instance, in April 2025, UK-based Epsilogen acquired Boston’s TigaTx, expanding its oncology pipeline with IgA and IgE antibody assets to establish a leading pan-isotype cancer antibody company. Such strategies are anticipated to drive the market growth.
 To learn more about this report, Download Free Sample Report
Regulations in the research antibodies market include guidelines for enhancing data reproducibility and trust in experimental outcomes. However, navigating complex regulatory landscapes can pose challenges for companies, impacting product development timelines and research and development activities costs.
Product expansion in the industry is driven by the shift from conventional antibodies to recombinant, nanobodies, and conjugated variants tailored for applications like immunohistochemistry, flow cytometry, and proteomics. Companies are broadening portfolios with multiplex-ready antibodies and assay kits, supporting advanced research needs and boosting market growth.
Regional expansion in the research antibodies market is driven by strong R&D funding in North America, government-backed initiatives in Europe, and rapid growth in Asia-Pacific, particularly China and India. Companies leverage these opportunities to strengthen distribution, tap new research hubs, and boost antibody adoption globally.
Analyst Perspective
The research antibodies market is driven by the expanding applications of antibodies in life sciences research, drug discovery, biomarker identification, and precision medicine. The increasing prevalence of chronic diseases, rising investments in genomics, proteomics, and cell biology research, and growing demand for highly specific and reproducible antibodies for target validation and molecular diagnostics are accelerating market adoption. Technological advancements in recombinant antibody engineering, antibody validation technologies, multiplex assays, and high-throughput screening platforms also drive the market growth. Key players are focusing on developing highly validated recombinant antibodies, expanding custom antibody services, and integrating advanced antibody engineering technologies to address reproducibility challenges and meet the evolving needs of translational research, immuno-oncology, and cell and gene therapy development.
Product Insights
Based on product, the primary segment held the largest revenue share of over 74.5% in 2025, and expected to grow at fastest CAGR over the forecast period. This can be attributed to the increasing availability of primary antibodies using rabbit, mouse, goat, and other species as hosts, as well as the wide range of utility offered by such antibodies for applications in the R&D space. Also, the segment is predicted to grow exponentially owing to the usage of primary antibodies for frequently performed laboratory procedures, such as staining and imaging.
The secondary antibodies segment is expected to grow at a significant CAGR from 2025 to 2033, as these are more convenient and cost-effective to develop. The demand for secondary research antibodies is also anticipated to increase due to the availability of ready-to-use conjugated antibodies that can improve product development activities by assisting in identifying, grouping, and purifying targeted antigens.
Specificity Insights
Based on specificity, monoclonal antibodies segment held the largest revenue share of over 60.3% in 2025, due to a sharp increase in the number of cancer research projects that demand high specificity antibodies. As monoclonal antibodies can efficiently adhere to or block antigens on cancer cells, they are employed in the identification and development of new medicines for various cancer types. This factor is expected to expand the growth prospects for the segment in the near future.
The polyclonal antibodies segment is projected to grow significantly over the forecast period, as these antibody structures are essential for research focusing on the purification of antigens and the examination of histopathological tissue. Furthermore, polyclonal antibodies provide benefits like stability, practical storage methods, strong affinity, and excellent compatibility for ELISA and western blotting technologies, propelling market growth. For instance, in November 2024, U.S.-based GigaGen dosed the first patient in a Phase 1 trial of GIGA-2339, a recombinant polyclonal antibody candidate to provide a functional cure for chronic hepatitis B.
Technology Insights
Based on Technology, western blotting segment held the largest revenue share of over 29.7% in 2025, due to the widespread availability and adoption of the technique. In addition, due to the increased accuracy that the western blotting technique offers, it is typically chosen over alternative technologies for applications involving the detection of important protein entities. These attributes are expected to positively affect the segment growth.
The immunohistochemistry segment is projected to grow at the fastest CAGR throughout the forecast period. The segment is anticipated to expand steadily due to its significant applications in detecting enzymes, antigens, tumor suppressor genes, and tumor cell growth for cell-based research. Moreover, rising R&D spending and a high level of scientific awareness regarding the technique have led to increasing growth prospects for immunohistochemistry. Furthermore, benefits provided by the method, such as high sensitivity & simplicity of use, are some of the factors anticipated to drive market growth.
Source Insights
Based on source, the rabbit segment held the largest revenue share of over 50.3% in 2025. Rabbits are extensively used for antibody production, owing to several advantages, such as higher-affinity antibodies provided by rabbits than those obtained from other animal hosts. Furthermore, the higher specificity provided by these antibodies makes them ideal for detecting small molecules, hormones, toxins, and other biologically important substances.
The mice source segment is anticipated to witness the fastest CAGR over the forecast period, because of its small size and higher production rate. Mice have been the primary animal used in the production of antibodies. The primary element driving their extensive use is the structural resemblance between human and mouse antibodies, which can greatly accelerate their uptake for research and development applications.
Application Insights
Based on application, the oncology segment held the largest revenue share of over 32.9% in 2025, driven by the rising cancer burden and growing use of antibodies in tumor marker detection, biomarker discovery, and targeted therapy development. According to the National Cancer Institute, Cancer is among the leading causes of death worldwide. In 2022, there were almost 20 million new cases and 9.7 million cancer-related deaths worldwide. Moreover, strong R&D investments and precision oncology initiatives are expected to sustain this dominance.
The stem cells segment is expected to grow significantly over the forecast period, owing to increased global stem cell research activities. The growth is also attributable to increased adoption of stem cells for treating various chronic ailments such as diabetes, cancer, Alzheimer’s, Parkinson’s, rheumatoid arthritis, and kidney and lung diseases. Furthermore, antibodies are also used for stem cell research areas that include disease modeling, developmental biology, drug screening, reprogramming techniques development, and cell therapy, which can positively affect market growth.
End Use Insights
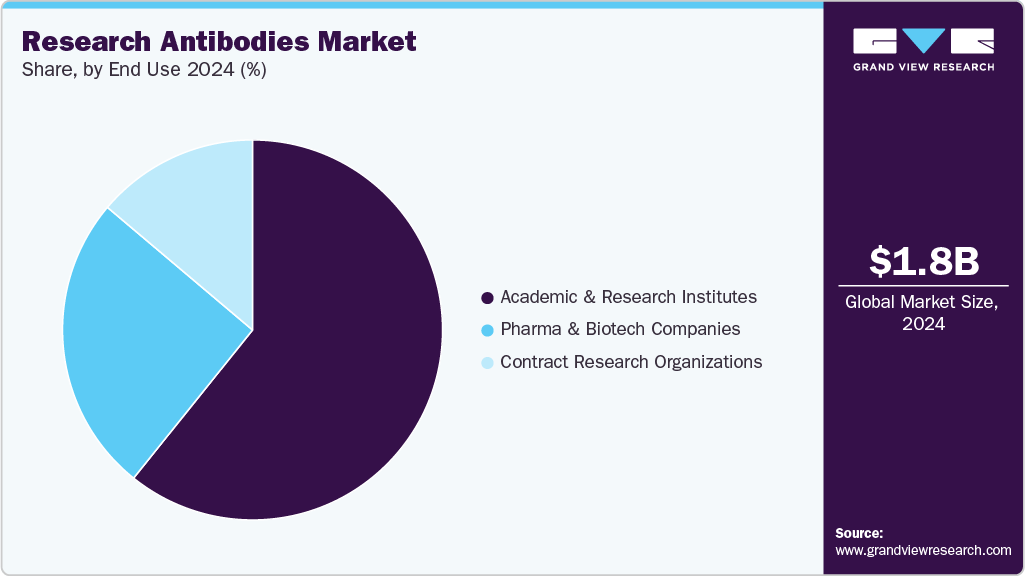
Based on end use, the academic & research institutes segment held the largest revenue share of over 60.9% in 2025. This can be attributed to the increased scientific initiatives by such centers to develop novel therapies and tests for chronic diseases. For instance, in January 2021, researchers at The University of Texas Medical Branch at Galveston (UTMB Health) and The University of Texas Health Science Center at Houston (UTHealth) discovered two novel antibodies, CoV2-06 and CoV2-14, for a potential novel antibody therapy for COVID-19 infection. Such initiatives can positively affect the segment growth over the forecast period.
 To learn more about this report, Download Free Sample Report
The pharmaceutical and biotechnology companies segment is expected to grow at a significant CAGR over the forecast period. This can be attributed to the increase in R&D activities in the life sciences domain. Furthermore, the increasing importance of antibodies in the development of novel biologic products and the rising demand for quality control applications for various techniques, such as PCR and electrophoresis, are likely to boost the segment's growth.
Regional Insights
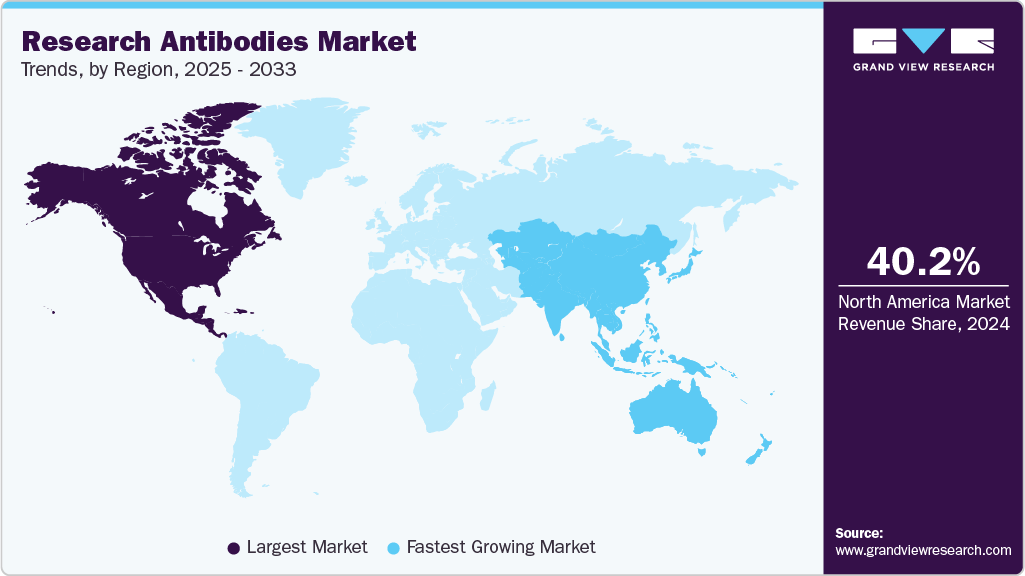
North America dominated the research antibodies market with the largest revenue share of 40.4% in 2025, supported by strong healthcare spending, robust government and private R&D investments, and a high concentration of pharmaceutical and biotech companies. The region benefits from widespread clinical adoption of antibody-based tools in genomics, proteomics, and precision medicine.
 To learn more about this report, Download Free Sample Report
U.S. Research Antibodies Market Trends
The research antibodies market in the U.S. held the largest share in the North America region in 2025. The U.S. remains the largest contributor to the regional growth of the research antibodies industry, driven by its dense network of academic research centers, extensive NIH funding, and active biopharma pipeline. Research in immunology, neurology, and oncology extensively uses antibodies, and drug discovery and biomarker development initiatives are driving up demand for them. The FDA's approval of antibody-linked diagnostics and recent advancements in antibody-based assays strengthen the nation's position as a leader.
Europe Research Antibodies Market Trends
Europe shows steady expansion, supported by well-established research ecosystems, collaborative EU-funded programs, and growing demand for reproducible antibodies in translational research. European academic centers and biotech hubs are heavily engaged in biomarker discovery, antibody validation, and large-scale cohort studies. Harmonized regulatory pathways and increased adoption of open-science standards are helping Europe strengthen its role in high-quality antibody research.
The UK research antibodies market benefits from strong academic-industry collaborations, national genomics programs, and the NHS infrastructure that supports translational antibody research. Focus areas that incorporate antibody-based tools into diagnostics and therapeutic development include immunology, neurobiology, and oncology. Targeted government funding and venture-backed biotech startups are expediting the commercialization of antibody-based assays and companion diagnostics.
The research antibodies market in Germany is expected to grow over the forecast period. Germany represents a key European hub with strong demand for antibodies in biologics R&D, immuno-oncology, and biomarker-driven clinical trials. German research institutes and pharma companies are leaders in validating novel recombinant and monoclonal antibodies for drug discovery and advanced diagnostics. Strategic partnerships between academia and industry continue to accelerate antibody innovation and commercialization.
Asia Pacific Research Antibodies Market Trends
The Asia Pacific research antibodies industry is projected to grow at the fastest CAGR of 10.0% during the forecast period, fueled by rising investments in biomedical research, expanding biotech hubs, and government-backed initiatives in China, India, Japan, and South Korea. The region's use of antibodies is being strengthened by the growing use of proteomics and genomics in academic institutions as well as the rising demand for precision medicine. Local manufacturing capabilities and international partnerships are also accelerating adoption. For instance, in August 2025, India's BRIC-THSTI invited biopharma partners to co-develop a novel monoclonal antibody drug, advancing it from research to GMP manufacturing and IND-enabling studies under a ₹10 crore project.
The China research antibodies market is rapidly expanding as a major space, supported by favorable government funding, fast-track regulatory approvals, and heavy investment in genomics and precision medicine. Local biotech companies and research institutions are advancing recombinant and monoclonal antibody platforms tailored to cancer and infectious disease research. Strategic partnerships with Western firms are boosting technology transfer and scaling domestic production.
The research antibodies market in Japan is expected to grow during the forecast period. Japan’s strong biomedical research infrastructure, focus on precision medicine, and aging population drive demand for advanced antibody products. The use of antibodies in translational research is growing, especially in neurology, age-related diseases, and oncology. Academic-industry collaborations and government funding for antibody innovation programs reinforce Japan’s role as a leading Asia-Pacific market.
MEA Research Antibodies Market Trends
The MEA research antibodies industry is in an early but growing phase, driven by rising investment in healthcare infrastructure, academic collaborations, and research funding in major hubs such as Saudi Arabia, the UAE, and South Africa. Although adoption is concentrated in leading urban centers, antibody demand for infectious disease research and precision medicine programs is rising. International collaborations are gradually building local capacity for antibody production and utilization.
The Kuwait research antibodies market is projected to grow over the forecast period. Kuwait’s research antibody market is developing and is supported by government-led healthcare modernization and targeted investments in life sciences. Strategic partnerships with academic institutions and international research organizations make the introduction of sophisticated antibody-based assays for drug discovery and diagnostics possible. Early-stage precision medicine and biomarker development initiatives are creating new growth opportunities for global antibody suppliers entering the market.
Key Research Antibodies Company Insights
The research antibodies industry is characterized by several well-established players that dominate through extensive product portfolios, global reach, and continuous investments in research and development. By providing high-quality, validated antibodies for a variety of applications, including oncology, immunology, neuroscience, and infectious disease research, industry leaders like Abcam Plc, Merck KGaA, Thermo Fisher Scientific, Inc., Cell Signaling Technology, Inc., and Santa Cruz Biotechnology Inc. maintain a substantial market presence. Their emphasis on reproducibility, proprietary platforms, and robust distribution networks has strengthened their leadership positions.
By creating novel and application-specific antibody solutions, such as recombinant antibodies, secondary antibodies, and assay kits, businesses like PerkinElmer, Inc., Becton, Dickinson and Company, Bio-Techne Corporation, Proteintech Group, Inc., and Jackson ImmunoResearch Inc. are actively growing their footprints.
 To learn more about this report, Download Free Sample Report
As a result, the market for research antibodies sees a dynamic balance between established leaders and up-and-coming innovators. The industry is changing due to increased competition from technical developments in antibody engineering and validation. Businesses are well-positioned to provide long-term value in this quickly growing industry if they can effectively combine innovation with customer-focused solutions and strong technical support.
Key Research Antibodies Companies
The following key companies have been profiled for this study on the research antibodies market.
-
Abcam Plc.
-
Merck KGaA
-
Thermo Fisher Scientific, Inc.
-
Cell Signalling Technology, Inc.
-
Santa Cruz Biotechnology Inc.
-
PerkinElmer, Inc.
-
Becton, Dickinson and Company
-
Bio-Techne Corporation
-
Proteintech Group, Inc.
-
Jackson ImmunoResearch Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Thermo Fisher Scientific, Merck KGaA, Danaher Corporation, etc.)
- Focus on expanding research antibody portfolios through the development of recombinant and highly validated antibodies, custom antibody services, multiplex immunoassays, and integrated solutions for proteomics, genomics, immunology, and translational research applications.
- Broad product portfolios, extensive global distribution networks, strong brand recognition, large-scale manufacturing capabilities, and established relationships with pharmaceutical and biotechnology companies, academic institutions, and contract research organizations.
- High dependence on life sciences research funding and pharmaceutical R&D spending, substantial investments required for antibody validation and quality control, and increasing competition from specialized recombinant antibody providers and emerging reagent technologies.
Emerging Players (Bio X Cell, Proteintech Group, Absolute Antibody Ltd, etc.)
- Expand market presence through innovations in recombinant antibody engineering, custom antibody development, trispecific and multispecific antibody formats, niche application-specific antibodies, and advanced validation services targeting immuno-oncology, cell and gene therapy, and precision medicine research applications.
- Greater flexibility, specialized expertise, and faster innovation cycles, enabling rapid development of customized, highly specific, and application-validated antibodies for emerging research areas and complex biological targets.
- Narrower product portfolios, limited geographical presence and distribution capabilities, lower economies of scale, and comparatively lower adoption among large pharmaceutical companies and global research organizations due to lower brand recognition and constrained commercial reach.
Recent Development
-
In June 2026, Bio X Cell launched the first commercially available ready-to-use anti-mouse PD-L1 × TIGIT × LAG3 trispecific antibody for preclinical research. The tetravalent trispecific antibody enables simultaneous investigation of three immune checkpoint pathways within a single in vivo system, supporting studies of T-cell exhaustion, immunosuppression, and combinatorial checkpoint blockade. The product expands the range of advanced recombinant antibody offerings and addresses the growing need for sophisticated preclinical tools in immuno-oncology research.
"Checkpoint biology is inherently combinatorial, and researchers increasingly need tools that reflect that complexity. This trispecific format brings PD-L1, TIGIT, and LAG3 together within a single in vivo system, expanding the experimental approaches available for studying checkpoint interactions."
-Kaitlyn Bushey, Director of Development and Strategic Alliances at Bio X Cell.
-
In May 2026, Aspera Biomedicines Inc. launched its second ADAR1p150 research antibody experiment to the International Space Station aboard the SpaceX CRS-34 mission. The company is leveraging microgravity-enabled research antibodies to obtain high-resolution structural insights into ADAR1-Rebecsinib interactions, accelerating the development of an oral formulation of Rebecsinib and next-generation therapies targeting more than 20 cancer types.
“This is the second launch for Aspera’s research antibodies experiments with ADAR1, as part of a NASA InSPA Phase 2 award to further elucidate the mechanism of action of Rebecsinib and to develop an oral formulation for clinical trials in a broad array of advanced malignancies. This is a fundamentally important mission aimed at defining the mechanism of action of Aspera’s ADAR1 inhibitor in addition to accelerating the development of a Rebecsinib oral formulation that could prevent cancer stem cell cloning (malignant regeneration) and cloaking from the immune system in 20 different cancers.”
Dr. Catriona Jamieson, Founder and Board Member of Aspera Biomedicines.
Research Antibodies Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.9 billion
Market size value in 2026
USD 2.1 billion
Revenue forecast in 2033
USD 3.9 billion
Growth rate
CAGR of 9.2% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, specificity, technology, source, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, China, Japan, India, South Korea, Australia, Thailand, Brazil, Argentina, Saudi Arabia, South Africa, UAE, and Kuwait
Key companies profiled
Abcam Plc; Merck KGaA; Thermo Fisher Scientific, Inc.; Cell Signalling Technology, Inc.; Santa Cruz Biotechnology Inc.; PerkinElmer, Inc.; Becton, Dickinson and Company; Bio-Techne Corporation; Proteintech Group, Inc.; Jackson ImmunoResearch Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Research Antibodies Market Report Segmentation
This report forecasts revenue growth and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global research antibodies market report based on product, specificity, technology, source, application, end use, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Primary Antibodies
-
Secondary Antibodies
-
-
Specificity Outlook (Revenue, USD Million, 2021 - 2033)
-
Monoclonal Antibodies
-
Polyclonal Antibodies
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Immunohistochemistry
-
Immunofluorescence
-
Western Blotting
-
Flow Cytometry
-
Immunoprecipitation
-
ELISA
-
Others
-
-
Source Outlook (Revenue, USD Million, 2021 - 2033)
-
Mouse
-
Rabbit
-
Goat
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Infectious Diseases
-
Immunology
-
Oncology
-
Stem Cells
-
Neurobiology
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Academic & Research Institutes
-
Contract Research Organizations
-
Pharmaceutical & Biotechnology Companies
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The research antibodies market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each research antibodies segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Product
Revenue Capture Definition
Primary Antibodies
Revenue generated from antibodies that directly bind to specific target antigens or proteins of interest in research applications. This segment includes monoclonal and polyclonal primary antibodies used in immunohistochemistry, Western blotting, flow cytometry, ELISA, immunofluorescence, and other protein detection and characterization techniques.
Secondary Antibodies
Revenue generated from antibodies designed to bind to primary antibodies for signal amplification and detection. This segment includes enzyme-conjugated, fluorescently labeled, biotinylated, and other secondary antibodies used in immunoassays and imaging applications to enhance sensitivity and visualization.
Segment-Technology
Revenue Capture Definition
Monoclonal Antibodies
Revenue generated from antibodies derived from a single B-cell clone and designed to recognize a single epitope on a target antigen. This segment includes hybridoma-derived and recombinant monoclonal antibodies used for highly specific protein detection, target validation, and biomarker research.
Polyclonal Antibodies
Revenue generated from antibodies comprising heterogeneous immunoglobulin populations that recognize multiple epitopes on the same antigen. This segment includes animal-derived polyclonal antibodies widely used in protein detection, immunoprecipitation, and applications requiring high sensitivity and broad antigen recognition.
Segment-Technology
Revenue Capture Definition
Immunohistochemistry (IHC)
Revenue generated from antibodies used in immunohistochemistry applications for detecting and visualizing protein expression in tissue sections through chromogenic or fluorescent labeling methods.
Immunofluorescence (IF)
Revenue generated from antibodies used in immunofluorescence assays for detecting and localizing proteins, antigens, and cellular structures through fluorescent dye-conjugated antibody labeling.
Western Blotting
Revenue generated from antibodies used in Western blot applications for protein identification, quantification, and characterization following electrophoretic separation and membrane transfer.
Flow Cytometry
Revenue generated from antibodies used in flow cytometry and fluorescence-activated cell sorting (FACS) applications for cellular phenotyping, immunophenotyping, and multiparametric analysis of cell populations.
Immunoprecipitation (IP)
Revenue generated from antibodies used in immunoprecipitation applications for isolating and enriching specific proteins, protein complexes, and protein interactions from biological samples.
ELISA
Revenue generated from antibodies used in enzyme-linked immunosorbent assay (ELISA) applications for the quantitative and qualitative detection of proteins, antigens, antibodies, and biomarkers in biological specimens.
Others
Revenue generated from antibodies used in other research techniques, including immunocytochemistry, chromatin immunoprecipitation (ChIP), protein arrays, lateral flow assays, multiplex immunoassays, and emerging antibody-based analytical methods.
Segment- End Use
Revenue Capture Definition
Mouse
Revenue generated from research antibodies produced in or derived from mouse hosts, including monoclonal and polyclonal antibodies used extensively for protein detection, biomarker discovery, and cell-based assays.
Rabbit
Revenue generated from research antibodies produced in rabbit hosts, including rabbit monoclonal and polyclonal antibodies known for high affinity, specificity, and broad epitope recognition capabilities.
Goat
Revenue generated from research antibodies produced in goat hosts, including primary and secondary antibodies commonly used in immunoassays, protein detection, and signal amplification applications.
Others
Revenue generated from research antibodies derived from other host species, including rat, sheep, donkey, chicken, guinea pig, and alpaca, used for specialized immunological and multiplex research applications.
Segment- Application
Revenue Capture Definition
Infectious Diseases
Revenue generated from research antibodies used in studying bacterial, viral, fungal, and parasitic infections, including pathogen detection, host-pathogen interaction studies, vaccine development, and infectious disease biomarker research.
Immunology
Revenue generated from research antibodies used in immunology research, including studies related to immune cell characterization, cytokine profiling, immune signaling pathways, autoimmune diseases, and immune response mechanisms.
Oncology
Revenue generated from research antibodies used in cancer research applications, including tumor biomarker identification, immune-oncology studies, target validation, cancer signaling pathway analysis, and therapeutic target discovery.
Stem Cells
Revenue generated from research antibodies used in stem cell research for cell identification, differentiation analysis, pluripotency assessment, and characterization of stem cell-derived products and regenerative medicine applications.
Neurobiology
Revenue generated from research antibodies used in neurobiology and neuroscience research for studying neuronal proteins, neurodegenerative diseases, synaptic signaling pathways, and central and peripheral nervous system disorders.
Others
Revenue generated from research antibodies used in other application areas, including cardiovascular research, metabolic disorders, developmental biology, reproductive biology, toxicology, and environmental research.
Segment- End Use
Revenue Capture Definition
Academic & Research Institutes
Revenue generated from the procurement and use of research antibodies by universities, government laboratories, research institutes, and non-profit organizations conducting basic, translational, and applied life science research.
Contract Research Organizations (CROs)
Revenue generated from research antibodies utilized by contract research organizations providing outsourced preclinical, analytical, biomarker, and laboratory research services to pharmaceutical, biotechnology, and academic clients.
Pharmaceutical & Biotechnology Companies
Revenue generated from research antibodies purchased and used by pharmaceutical and biotechnology companies for drug discovery, target identification, biomarker development, translational research, therapeutic development, and quality control activities.
Estimation Model
Top-Down
Parent Market
Segmentation
Validation
Forecasting
Commodity Flow Analysis
Parent Market & Penetration-Based Analysis
Country-Level Segment Share Modeling
Validation
Forecasting & CAGR Modeling
Market size was estimated by analyzing revenues generated by key research antibody manufacturers and suppliers, supported by company annual reports, investor presentations, product catalogs, distributor insights, and premium databases. Revenue contributions from private companies were assessed using industry databases and validated through primary research to derive the overall market value.
The research antibodies market was evaluated by analyzing the broader life sciences research tools, proteomics, genomics, and immunology research landscape. Research funding levels, pharmaceutical and biotechnology R&D expenditures, antibody adoption rates, and utilization trends across academic and commercial laboratories were assessed to estimate the addressable market and segment-level opportunities.
Market shares for product type, specificity, technology, source, application, and end-user segments were derived using country-specific research expenditures, biomedical research intensity, pharmaceutical R&D investments, disease research priorities, and laboratory adoption patterns. Weighted average calculations were applied to determine regional and global segment distributions.
Market estimates were validated through triangulation of secondary research, primary interviews, company-level revenue assessments, end-user procurement patterns, and demand-side analysis of life sciences research applications to ensure consistency and accuracy across all market segments and geographies.
Market forecasts were developed using historical market trends, life sciences research funding, pharmaceutical and biotechnology R&D expenditure, chronic disease prevalence, precision medicine adoption, technological advancements in recombinant antibodies, and expansion of cell and gene therapy research. Regression-based analysis and trend modeling were applied to project future market growth and CAGR.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Research Antibodies Technology & End-User Cross-Segmentation Analysis
Detailed cross-segmentation assessment across research antibody technologies and end users. Analysis includes technology adoption patterns, research workflows, antibody consumption trends, funding dynamics, and demand mapping across academic, commercial, and translational research settings.
Enables identification of high-growth technology-end-user combinations, uncovers emerging opportunities in precision medicine, immuno-oncology, and biomarker research, and supports targeted product development, commercialization, and market expansion strategies.
Competitive Landscape
Comprehensive benchmarking of leading research antibody companies based on product portfolio, recombinant antibody capabilities, antibody validation standards, custom antibody services, technology platforms, geographic presence, partnerships, innovation pipeline, and exposure to pharmaceutical, biotechnology, and academic research workflows.
Helps clients evaluate competitive positioning, identify technology gaps, benchmark best practices, assess partnership or acquisition opportunities, and develop differentiated strategies for market entry and expansion.
Regional Demand & Life Sciences Research Opportunity Analysis
Customized regional and country-level market assessment covering North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, with analysis of pharmaceutical and biotechnology R&D expenditure, government life sciences funding, chronic disease research activities, precision medicine initiatives, research infrastructure, and adoption of advanced research antibodies.
Supports prioritizing high-growth geographies, identifying investment hotspots, evaluating country-level commercialization potential, and aligning expansion strategies with evolving demand in biomedical research, drug discovery, and precision medicine.
Frequently Asked Questions About This Report
North America dominated the research antibodies market with the largest revenue share of 40.4% in 2025.
Some key players operating in the research antibodies market include Abcam Plc; Merck KGaA; Thermo Fisher Scientific, Inc.; Cell Signalling Technology, Inc.; Santa Cruz Biotechnology Inc.; PerkinElmer, Inc.; Becton, Dickinson and Company; Bio-Techne Corporation; Proteintech Group, Inc.; Jackson ImmunoResearch Inc.
The global research antibodies market size was valued at USD 1.9 billion in 2025 and is estimated at USD 2.1 billion in 2026.
The global research antibodies market is expected to grow at a compound annual growth rate of 9.2% from 2026 to 2033 to reach USD 3.9 billion by 2033.
Asia Pacific is the fastest-growing region over the forecast period.
Western blotting technology segment held the largest revenue share of over 29.7% in 2025.
The rabbit segment held the largest revenue share of over 50.3% in 2025.
The primary segment held the largest revenue share of over 74.5% in 2025, and expected to grow at fastest CAGR over the forecast period.
Key factors that are driving the research antibodies market growth include Increasing Investments in Life Science and Biomedical Research, Growing Prevalence of Chronic Diseases and Rising Focus on Precision Medicine, Advancements in Proteomics, Genomics, and Cell Biology Research
About the Author(s)
Biotechnology Research Team
Healthcare · BiotechnologyThis report was authored by the biotechnology research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the biotechnology segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


