
- Home
- »
- Next Generation Technologies
- »
-
Satellite Antenna Market Size, Share & Trends Report, 2030GVR Report cover

Satellite Antenna Market (2024 - 2030) Size, Share & Trends Analysis Report By Platform (Land, Space, Maritime, Airborne), By Frequency (L Band, S Band, C Band), By Technology, By Region, And Segment Forecasts
Market Size, 2023
$6.0BMarket Estimate, 2026
$10.0BMarket Forecast, 2030
$18.6BCAGR, 2024–2030
17.7%Satellite Antenna Market Summary
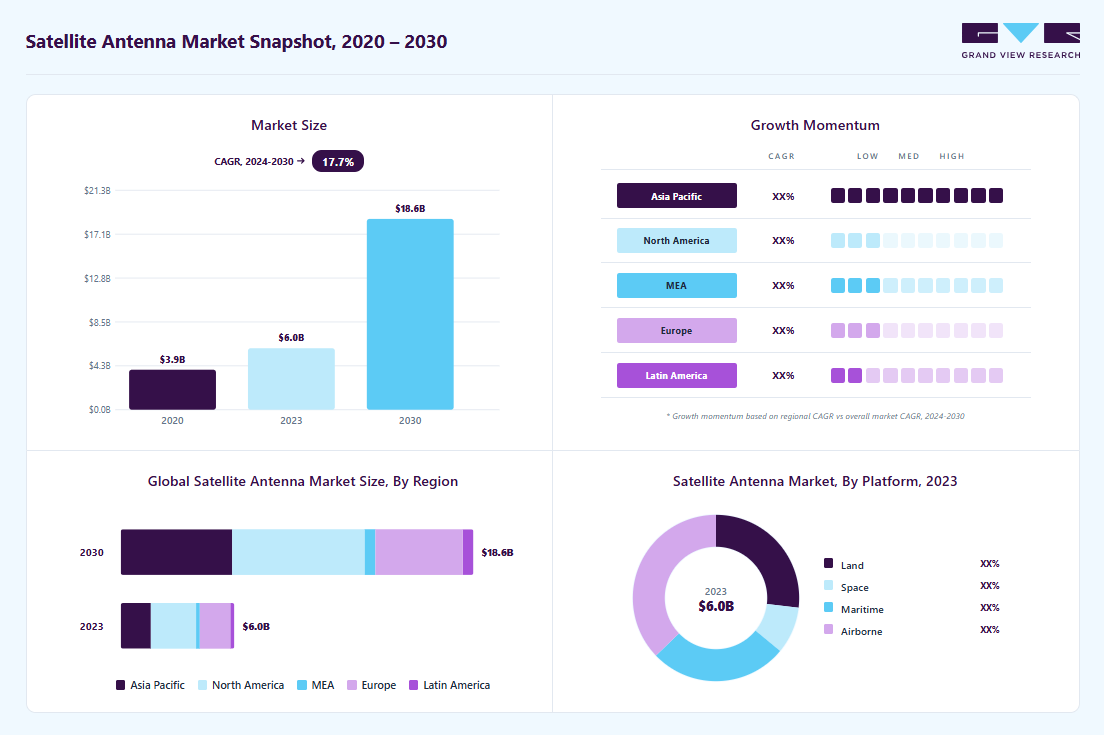
The global satellite antenna market size was estimated at USD 5.97 billion in 2023 and is projected to reach USD 18.6 billion by 2030, growing at a CAGR of 17.7% from 2024 to 2030. The increasing demand for satellite-based communication services and a growing need for reliable and high-speed connectivity across maritime, aviation, defense, telecommunications, and disaster management sectors is driving the market expansion.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- The North America region accounted for the highest revenue share of 39.93% in 2023.
- The satellite antenna market in the U.S. is projected to grow at a CAGR of 16.7% from 2024 to 2030.
- By platform, the land segment accounted for the largest market share of 26.87% in 2023.
- By frequency, the Ka-band segment is anticipated to grow fastest from 2024 to 2030.
- By technology, the SATCOM-On-the-Move (SOTM) segment registered the largest revenue share in 2023.
Market Size & Forecast
- 2023 Market Size: USD 5.97 Billion
- 2030 Projected Market Size: USD 18.6 Billion
- CAGR (2024-2030): 17.7%
- North America: Largest market in 2023
- Asia Pacific: Fastest growing market
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2024–2030 annual, 2023 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Satellite antennas are crucial in providing internet services to remote and underserved areas where traditional broadband infrastructure is lacking. As a result, the demand for advanced satellite antenna systems capable of delivering high-speed connectivity is expected to fuel market growth in the coming years. Airlines are equipping their aircraft with satellite antenna systems to provide in-flight Wi-Fi for passengers, while the maritime industry is adopting compact satellite antennas for onboard communications and operations. Sectors such as coaches, trains, emergency services, and logistics present valuable opportunities for mobile satellite antennas. These antennas enable internet access and communication solutions for users on the move, thereby accelerating the popularity and adoption of satellite antennas in these sectors.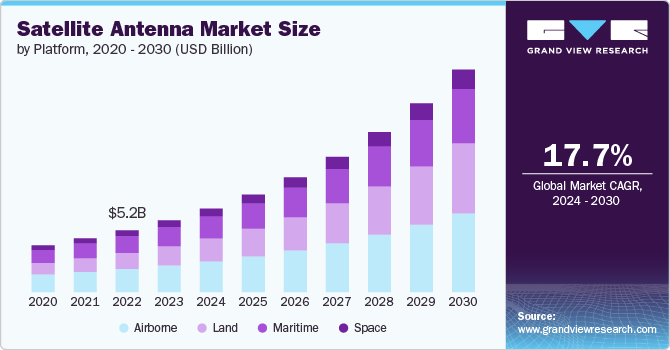 To learn more about this report, Download Free Sample Report
Furthermore, the ongoing technological advancements in satellite design and deployment are accelerating the market growth. Innovations such as high-throughput satellites (HTS), low earth orbit (LEO) constellations, and reusable launch vehicles have enhanced the efficiency and cost-effectiveness of satellite communications have led to improved data transmission rates, lower latency and increased coverage areas, driving the adoption of satellite antennas for various applications, including telecommunications, broadcasting, and defense.
Moreover, the development of ultra-compact satellite antennas designed to operate with high-throughput satellites is creating opportunities for market expansion. These antennas support advanced ground combat vehicles with high-speed data transmission capabilities, enabling beyond-line-of-sight applications for voice, video, and data communications. This trend is expected to fuel the market growth further.
Companies are employing a variety of strategies to enhance their market presence and capitalize on growth opportunities. They are securing contracts and forming partnerships. For instance, in June 2023, Airbus and Oerlikon signed a €3.8 million contract focused on the industrial additive manufacturing of satellite components, specifically antenna clusters for communication satellites.These antennas will be utilized in satellites that transmit and receive signals in the K-band frequency, which is essential for modern communication systems. Such strategies by key players are expected to boost market growth in the coming years.
Market Dynamics
The rapid deployment of low-earth-orbit satellite constellations is driving strong demand for advanced antenna systems capable of delivering continuous, high-precision signal coverage. As more satellites are launched to improve global communication infrastructure, antenna manufacturers are focusing on solutions that provide efficient tracking, stronger signal reception, and improved bandwidth performance across multiple operating environments.
The transition toward low-latency satellite communication is accelerating innovation in electronically steered antennas, phased-array systems, and compact ground terminals. Businesses and government entities increasingly require reliable connectivity across remote regions, maritime routes, and airborne platforms, thereby strengthening investment in antenna technologies that support uninterrupted communication with expanding orbital satellite networks.
High development and deployment costs remain a major challenge to market expansion, particularly for advanced antenna technologies that require precision engineering, sophisticated tracking systems, and specialized electronic components. The significant capital required for manufacturing, installation, and maintenance can restrict adoption among cost-sensitive buyers, especially when deployment involves customized infrastructure or operation in demanding environments.
Price volatility in raw materials and the increasing complexity of advanced electronic antenna systems further add financial pressure on manufacturers and end users. Extended product development cycles, certification requirements, and integration expenses can slow purchasing decisions, limiting rapid adoption despite growing demand for enhanced satellite communication capabilities across commercial and strategic applications.
The growing demand for uninterrupted connectivity across moving platforms is creating substantial opportunities for satellite antenna providers. Aviation, maritime, and land mobility applications increasingly require high-performance antennas capable of maintaining stable communication while in motion. This shift is encouraging the development of lightweight, compact, and aerodynamically optimized antenna systems tailored for continuous performance in dynamic operating conditions.
Technological advancements in flat-panel antennas and intelligent beam steering are expanding opportunities across next-generation mobility platforms. As customers prioritize seamless broadband access, navigation support, and real-time communication during transit, manufacturers have a strong potential to introduce efficient antenna solutions that improve connectivity performance while meeting space, weight, and operational efficiency requirements.
Market Concentration & Characteristics
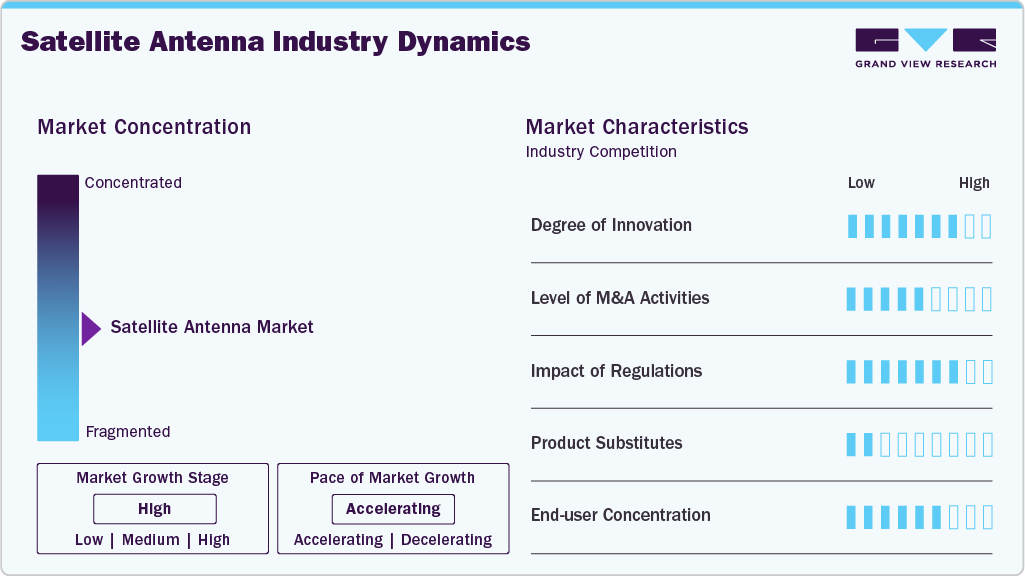
The satellite antenna market is moderately concentrated, with competition shaped by established antenna manufacturers, satellite communication equipment providers, electronically steered antenna developers, and specialized aerospace communication companies. Market participants are increasingly focused on antenna miniaturization, advances in flat-panel technology, multi-orbit compatibility, and signal efficiency enhancements to strengthen their market presence. Strategic collaborations with satellite operators, long-term contracts for communication infrastructure, and continued investment in advanced antenna engineering remain core competitive strategies supporting expansion across commercial, mobility, and defense communication platforms.
 To learn more about this report, Download Free Sample Report
The market demonstrates a high degree of innovation driven by continuous advancements in phased-array technology, beam-steering capabilities, compact antenna architecture, and improved broadband transmission performance. Regulatory impact remains high due to frequency spectrum allocation policies, communication security standards, and satellite transmission compliance requirements across international markets. Merger and acquisition activity remains moderate as companies expand technology portfolios through acquisitions involving antenna electronics and satellite communication specialists. Product substitution risk remains relatively low, as satellite antennas continue to provide critical long-range connectivity and dependable performance in remote or mobile operating environments where terrestrial network infrastructure remains limited.
Platform Insights
The land segment accounted for the largest market share of 26.87% in 2023. The increasing demand for high-speed internet in urban and rural areas and the need for resilient communication infrastructure are driving significant investment in land-based satellite antennas. Furthermore, the rise of smart cities and the expansion of IoT networks are expected to drive segmental growth.
The airborne segment is expected to witness a significant CAGR of over 16.9% from 2024 to 2030, driven by the growing demand for advanced communication systems in aviation. This includes satellite antennas for commercial airlines, military aircraft, and unmanned aerial vehicles (UAVs). Furthermore, the increasing trend of in-flight connectivity for passengers, providing internet access, and live television is driving the segmental growth.
Frequency Insights
The Ku-band registered the largest share in the market in 2023, owing to its widespread adoption, particularly for direct-to-home (DTH) television services, and its well-established infrastructure. Its frequency range of 12-18 GHz offers reliable and high-quality communication, making it a preferred choice for broadcasting, maritime, and aeronautical services.Ku-band's cost-effectiveness and operational flexibility, including its resilience to weather conditions compared to higher frequency bands, is expected to fuel segmental growth.
The Ka-band segment is anticipated to grow fastest from 2024 to 2030. Its superior bandwidth and the rising demand for high-throughput satellites (HTS) drive the segmental growth. Operating in the 26.5-40 GHz frequency range, the Ka-band supports high-data-rate applications like broadband internet and HD video streaming. Technological advancements, such as phased array and electronically steerable antennas, enhance its performance and affordability.
Technology Insights
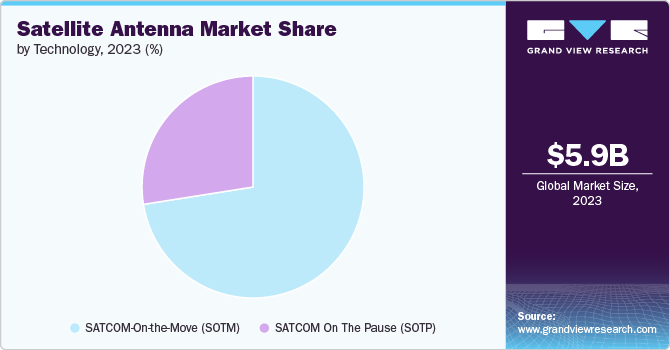
The SATCOM-On-the-Move (SOTM) segment registered the largest revenue share in 2023. This growth can be attributed to its essential role in providing continuous, high-speed communication for mobile platforms. SOTM systems are indispensable for military and defense operations, enabling real-time data transmission and communication for vehicles, aircraft, and ships. The commercial sector also benefits from SOTM, with applications in logistics, transportation, and media broadcasting, where constant connectivity is crucial.The ability to maintain seamless communication while in motion makes SOTM a critical component of modern communication infrastructure.
 To learn more about this report, Download Free Sample Report
The SATCOM On the Pause (SOTP) segment is expected to grow at a significant CAGR from 2024 to 2030, owing to its increasing applications in various fields that require reliable communication in stationary positions. SOTP systems are particularly vital for military operations, emergency response, and remote field research where temporary, high-bandwidth satellite communications are needed in locations without established infrastructure. The growing prevalence of natural disasters and humanitarian crises drives demand for portable and deployable SATCOM solutions, ensuring connectivity in critical situations.
Regional Insights
The North America region accounted for the highest revenue share of 39.93% in 2023. This dominance is driven by advancements in satellite technology, such as the development of high-throughput satellites (HTS) and phased array antennas, which enhance the performance and capabilities of satellite communication systems. Furthermore, the popularity of satellite TV services in North America contributes to the demand for satellite antennas as consumers seek access to a wide range of channels and content.
U.S. Satellite Antenna Market Trends
The satellite antenna market in the U.S. is projected to grow at a CAGR of 16.7% from 2024 to 2030. A trend towards miniaturization, making satellite antennas more compact and lightweight, is driving the market growth. This is particularly beneficial for applications in mobile communications and IoT devices.
Europe Satellite Antenna Market Trends
The satellite antenna market in Europe is anticipated to grow at a CAGR of 16.3% from 2024 to 2030.This growth is driven by the strong aerospace industry's demand for reliable satellite communication solutions for aircraft connectivity and navigation systems. Satellite antennas play a vital role in ensuring seamless data transmission for aviation applications within the region, driving market growth.
The UK satellite antenna market is anticipated to grow at the fastest CAGR from 2024 to 2030 in the European market. The UK is experiencing a growing demand for high-speed internet services, especially in rural areas where traditional broadband infrastructure may be lacking. Satellite antennas are crucial in providing reliable internet connectivity to these underserved regions.
The satellite antenna market in Germany is expected to grow lucratively from 2024 to 2030. Germany’s push towards expanding 5G networks requires robust infrastructure, including satellite antennas, to ensure widespread coverage and high-speed connectivity. This trend is fueling the demand for advanced satellite antenna solutions.
The France satellite antenna market is projected to grow at a significant CAGR from 2024 to 2030. France’s active participation in space exploration programs necessitates advanced satellite communication capabilities, including sophisticated antenna systems. The country’s focus on space research drives investments in cutting-edge satellite antenna technologies.
Asia Pacific Satellite Antenna Market Trends
The satellite antenna market in the Asia Pacific region is expected to grow at the fastest CAGR of over 20% from 2024 to 2030. Rapid urbanization and increasing demand for high-speed internet connectivity in both urban and rural areas are driving the market growth in the region. Satellite antennas are needed to bridge the digital divide and provide reliable communication services.
China satellite antenna market is projected to grow at a significant CAGR from 2024 to 2030.China has been investing heavily in space technology and satellite communication infrastructure, and the Chinese government’s support for the development of satellite technology is a significant driver of this growth.
The satellite antenna market in Japan is expected to grow lucratively CAGR from 2024 to 2030.Japan’s advanced telecommunications infrastructure and high-speed connectivity requirements drive the adoption of cutting-edge satellite antenna solutions to meet the growing demand for data-intensive applications.
India satellite antenna market is expected to grow at an impressive CAGR from 2024 to 2030. Satellite antennas play a crucial role in providing connectivity to remote and underserved areas in India. The focus on improving rural connectivity through satellite technology is fueling the market growth in India.
Middle East & Africa Satellite Antenna Market Trends
The satellite antenna market in the Middle East and Africa is expected to grow at a CAGR of over 16% from 2024 to 2030, driven by increasing demand for satellite communication services, technological advancements, government investments, expansion of 5G networks, IoT/M2M proliferation, market liberalization, and rising demand for mobility solutions.
Saudi Arabia satellite antenna market is anticipated to grow significantly from 2024 to 2030. Saudi Arabia's defense sector relies heavily on satellite communication for secure and reliable data transmission. Satellite antennas are integral to military operations, surveillance activities, and national security initiatives, driving the country's demand for advanced antenna solutions.
Key Satellite Antenna Company Insights
Some of the key players operating in the market include Honeywell International, Inc. and Siemens AG.
-
L3Harris Technologies is a leading global aerospace and defense technology company that provides various solutions, including tactical communications, geospatial systems, air traffic management, avionics, and electronic warfare.The company also provides advanced satellite communication systems supporting military and commercial applications. Its SATCOM solutions include terminals, modems, and antennas that enable secure and reliable communication for various platforms, including ground stations, aircraft, and maritime vessels.
-
Honeywell International, Inc. provides advanced SATCOM systems for aircraft, offering connectivity solutions that enhance flight operations and passenger experience. Honeywell's antennas are integral to its JetWave system, which delivers high-speed, global in-flight Wi-Fi connectivity. These antennas support various applications, including cockpit communications, passenger internet, and operational data exchanges, underscoring Honeywell's commitment to innovation in airborne satellite communication technologies.
Thales Group and Visat Inc. are some of the emerging market participants in the market.
-
Thales Groupis a global technology leader in the aerospace, defense, transportation, and security markets. The company offers a range of high-performance SATCOM solutions. Thales's antennas are designed for various applications, including aviation, maritime, and ground-based communications. The company's products are renowned for their reliability, advanced technology, and capability to support critical communication needs in defense and commercial sectors.
-
Visat, Inc. is a global communications company that provides high-speed satellite broadband services and secure networking systems covering military and commercial markets. The company's satellite antennas are integral to its residential, business, and in-flight connectivity services, delivering reliable and fast internet access to remote and underserved areas. Viasat's innovations in satellite technology, including its high-capacity ViaSat-3 satellite constellation, are driving advancements in the market
Key Satellite Antenna Companies:
The following are the leading companies in the satellite antenna market. These companies collectively hold the largest market share and dictate industry trends.
- L3Harris Technologies
- Honeywell International Inc.
- Thales Group
- Viasat, Inc.
- Hughes Network Systems
- Kymeta Corporation
- Cobham
- Airbus
- ALL.SPACE Networks Limited
- C-COM Satellite Systems Inc.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: L3Harris Technologies, Honeywell International Inc., Thales Group
- Mature players focus on expanding multi-orbit antenna portfolios through satellite operator partnerships globally.
- Invest heavily in R&D to advance phased array antenna performance.
- Strong global presence supports large-scale commercial, aviation, maritime, and defense contracts.
- Advanced engineering expertise enables reliable, high-performance antennas.
- Dependence on complex manufacturing processes can extend production timelines significantly.
- Large organizational structures may reduce flexibility against faster-moving antenna innovators.
Emerging Players: Kymeta Corporation, ALL.SPACE Networks Limited
- Emerging players focus on advancing flat-panel antennas for mobility-focused satellite communication applications.
- Invest in product innovation through partnerships with satellite connectivity providers.
- Agile innovation capabilities support faster development of advanced electronically steered antennas.
- Specialized product offerings strengthen positioning across mobility-focused satellite communication deployments.
- Limited global distribution networks can restrict expansion across high-demand regions.
- Smaller operational scale may reduce pricing competitiveness against established manufacturers.
Recent Developments
-
In July 2024, Cobham SATCOM unveiled its new flagship Sea Tel TVRO antenna, designed to provide enhanced connectivity for maritime vessels. The antenna features advanced technology and aims to improve communication capabilities for ships at sea. This innovation represents a significant advancement in maritime satellite communication systems.
-
In May 2024, Airbus successfully delivered the first active antenna for the SpainSat NG I satellite. This milestone marks a significant step in developing the SpainSat NG I program, which aims to enhance secure satellite communications for Spanish defense and security forces. The active antenna is a crucial component that will enable advanced communication capabilities for the satellite, ensuring reliable and secure connectivity.
-
In February 2024, L3Harris Technologies, Inc. demonstrated a digital phased array antenna system designed to enhance satellite communication capabilities. The system was showcased during a live demonstration at the company’s Palm Bay, Florida facility. This technology aims to improve the efficiency and flexibility of satellite communications by enabling high-speed data transfer and enhanced connectivity.
Satellite Antenna Market Report Scope
Report Attribute
Details
Market size value in 2024
USD 6.96 billion
Revenue forecast in 2030
USD 18.6 billion
Growth rate
CAGR of 17.7% from 2024 to 2030
Actual data
2018 - 2023
Forecast period
2024 - 2030
Quantitative units
Revenue in USD million/billion and CAGR from 2024 to 2030
Report Deployment
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Platform,technology, frequency, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; Australia; Japan; India; South Korea; Brazil; South Africa; Saudi Arabia; UAE
Key companies profiled
L3Harris Technologies, Inc.; Honeywell International Inc.; Thales Group; Viasat, Inc.; Hughes Network Systems; Kymeta Corporation; Cobham; Airbus; ALL.SPACE Networks Limited; C-COM Satellite Systems Inc.
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Satellite Antenna Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global satellite antenna market report based on platform, technology, frequency, and region:
-
Platform Outlook (Revenue, USD Million, 2018 - 2030)
-
Land
-
Space
-
Maritime
-
Airborne
-
-
Technology Outlook (Revenue, USD Million, 2018 - 2030)
-
SATCOM-On-the-Move (SOTM)
-
SATCOM On the Pause (SOTP)
-
-
Frequency Outlook (Revenue, USD Million, 2018 - 2030)
-
L Band
-
S-band
-
C-band
-
X-band
-
Ku-band
-
Ka-band
-
Q band
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2018 - 2030)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Australia
-
Japan
-
India
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Objective
Custom Research Modules Delivered
Strategic Value / Business Impact
Product Positioning & Competitive Intelligence
- Product benchmarking and feature comparison
- Pricing and value proposition analysis
- Brand perception and customer preference study
- Competitor strategy evaluation
- Improved product differentiation strategy
- Supported pricing optimization
- Identified unmet customer needs
- Enhanced competitive positioning
Technology & Innovation Assessment
- Emerging technology trend analysis
- Innovation pipeline and patent review
- Technology adoption readiness assessment
- Ecosystem and partnership mapping
- Identified future growth areas
- Supported innovation roadmap planning
- Evaluated commercialization potential
- Strengthened strategic partnership decisions
Frequently Asked Questions About This Report
The global satellite antenna market size was estimated at USD 5.97 billion in 2023 and is expected to reach USD 6.96 billion in 2024.
The global satellite antenna market is expected to grow at a compound annual growth rate of 17.7% from 2024 to 2030 to reach USD 18.6 billion by 2030.
The satellite antenna market in North America accounted for a significant revenue share of over 39.33% in 2023. This dominance is driven by the advancements in satellite technology, such as the development of high-throughput satellites (HTS) and phased array antennas, enhancing the performance and capabilities of satellite communication systems.
Some key players operating in the satellite antenna market include L3Harris Technologies, Honeywell International Inc., Thales Group, Viasat, Inc., Hughes Network Systems, Kymeta Corporation, Cobham, Airbus, ALL.SPACE Networks Limited, C-COM Satellite Systems Inc.
Key factors that are driving satellite antenna market growth include increasing demand for satellite-based communication services, growing need for reliable and high-speed connectivity across sectors and the ongoing technological advancements in satellite design and deployment.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


