
- Home
- »
- Advanced Interior Materials
- »
-
Semiconductor Dry Etch Systems Market Size Report, 2033GVR Report cover

Semiconductor Dry Etch Systems Market (2026 - 2033)
Size, Share & Trends Analysis Report By Etching Technique, By Application (Logic and Memory, Power Devices), By End Use (Consumer Electronics, Automotive), By Region And Segment Forecasts
Market Size, 2025
$16.8BMarket Estimate, 2026
$17.7BMarket Forecast, 2033
$25.5BCAGR, 2026–2033
5.4%Semiconductor Dry Etch Systems Market Summary
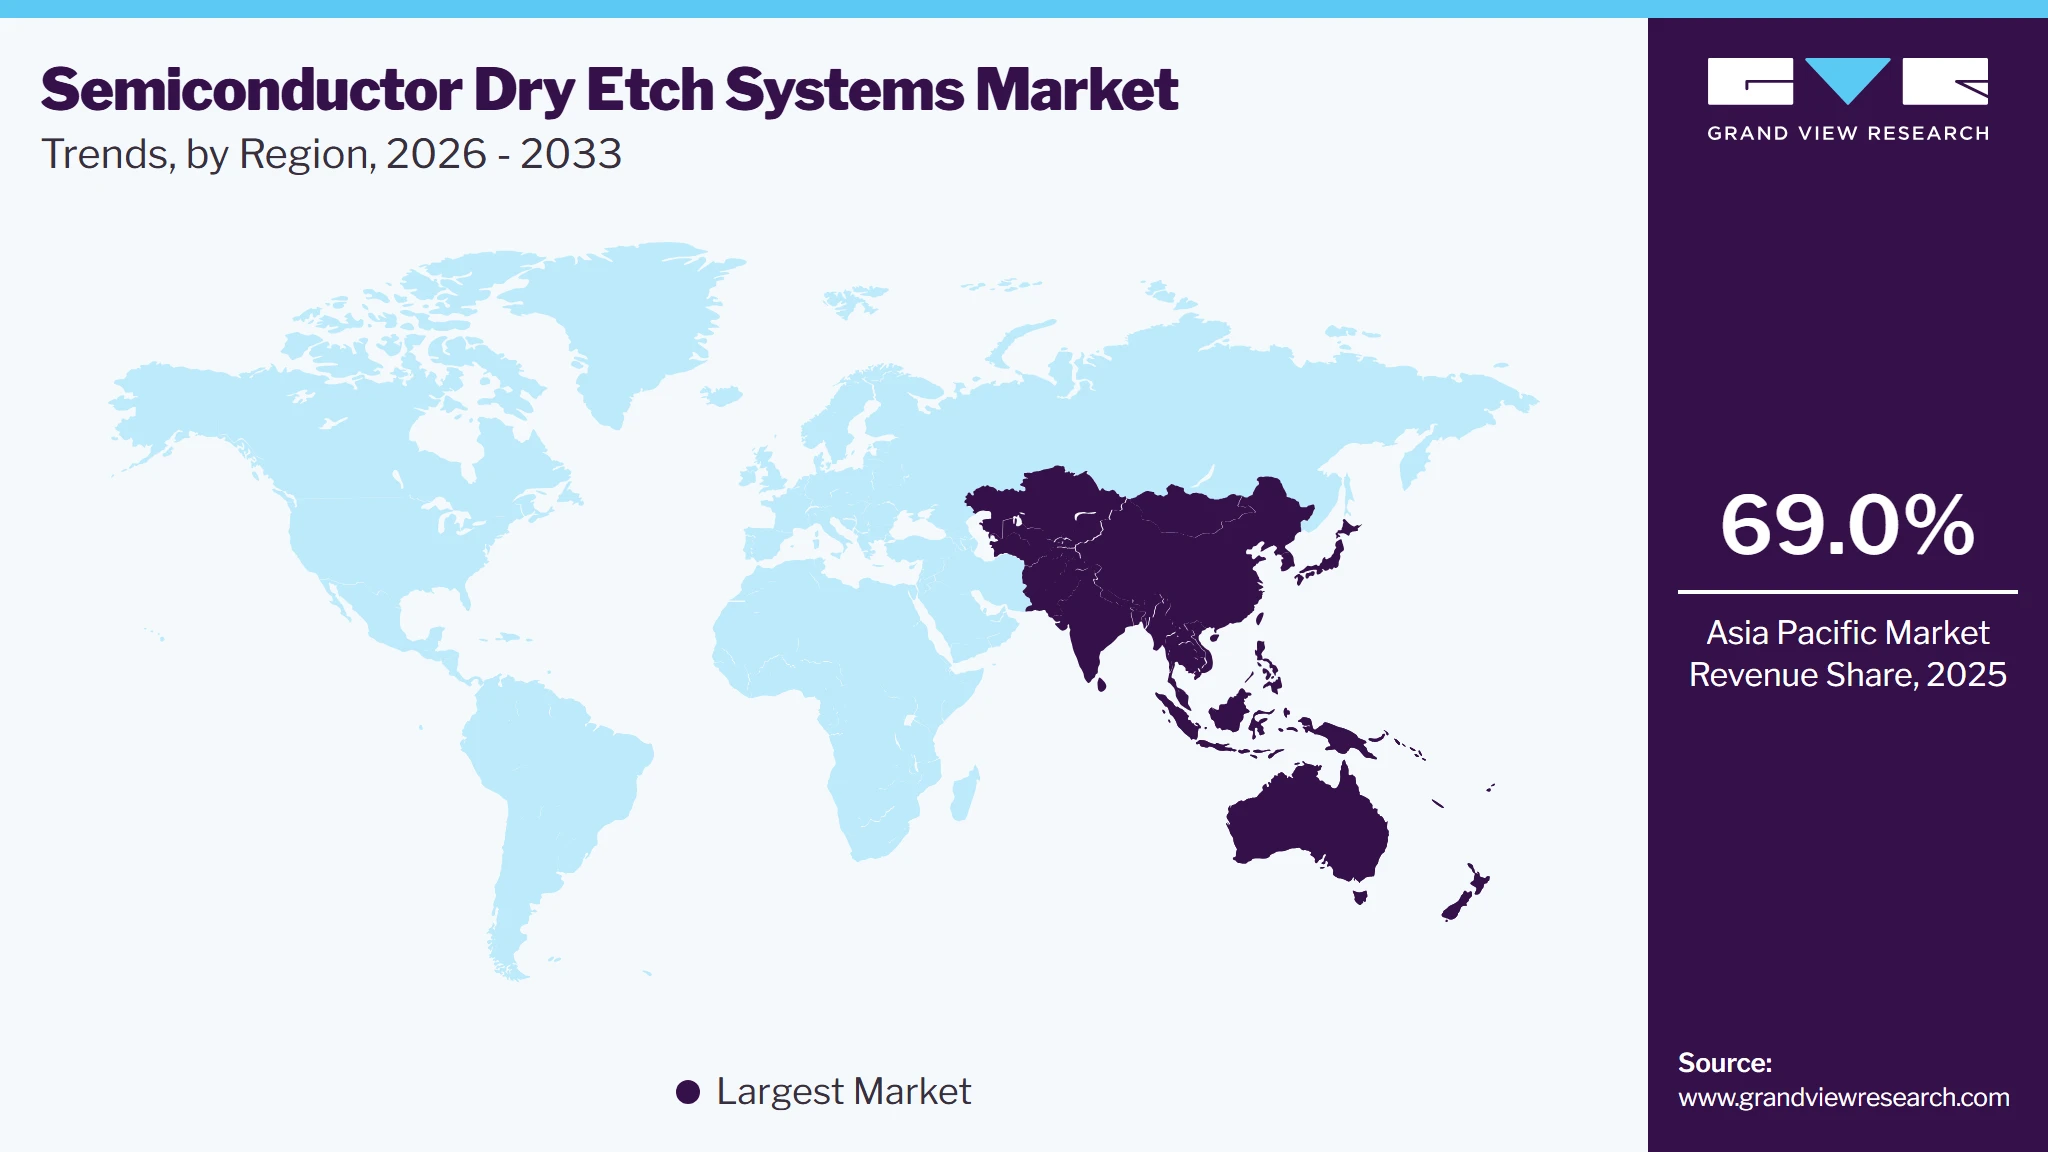
The global semiconductor dry etch systems market size was valued at USD 16.8 billion in 2025 and is projected to grow from USD 17.7 billion in 2026 to USD 25.5 billion by 2033, at a CAGR of 5.4% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 69.0% in 2025. The market is experiencing significant growth, driven by the escalating demand for consumer electronics, advancements in IoT, and the burgeoning automotive electronics sector.
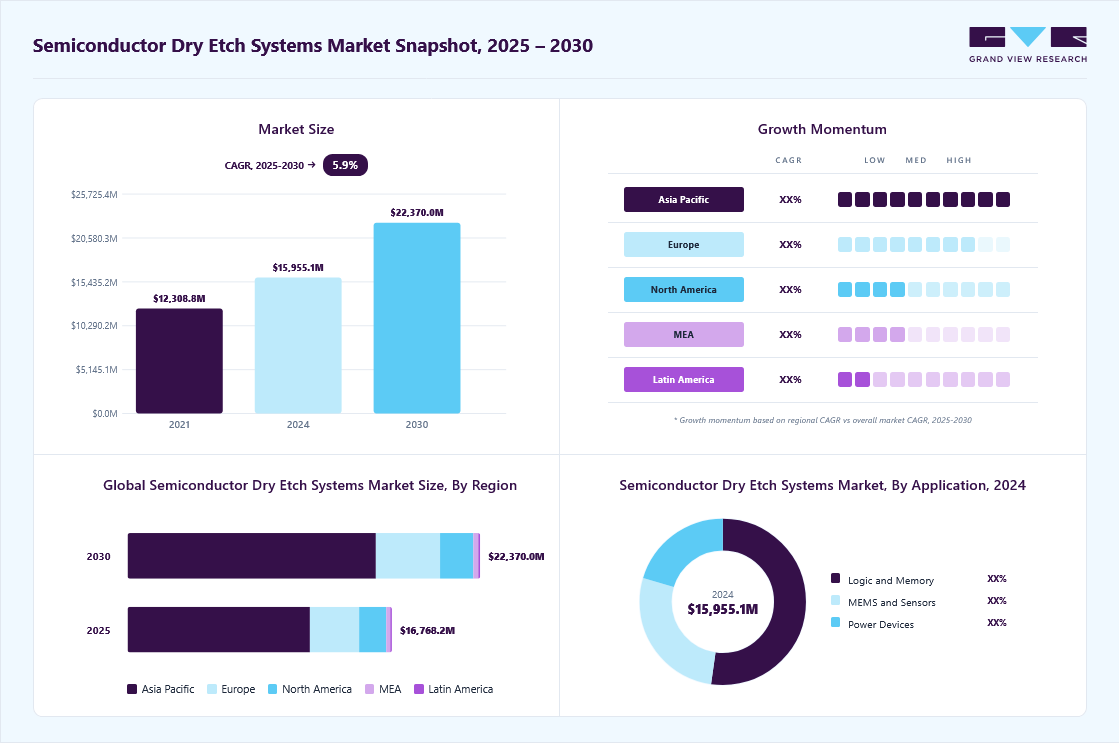 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
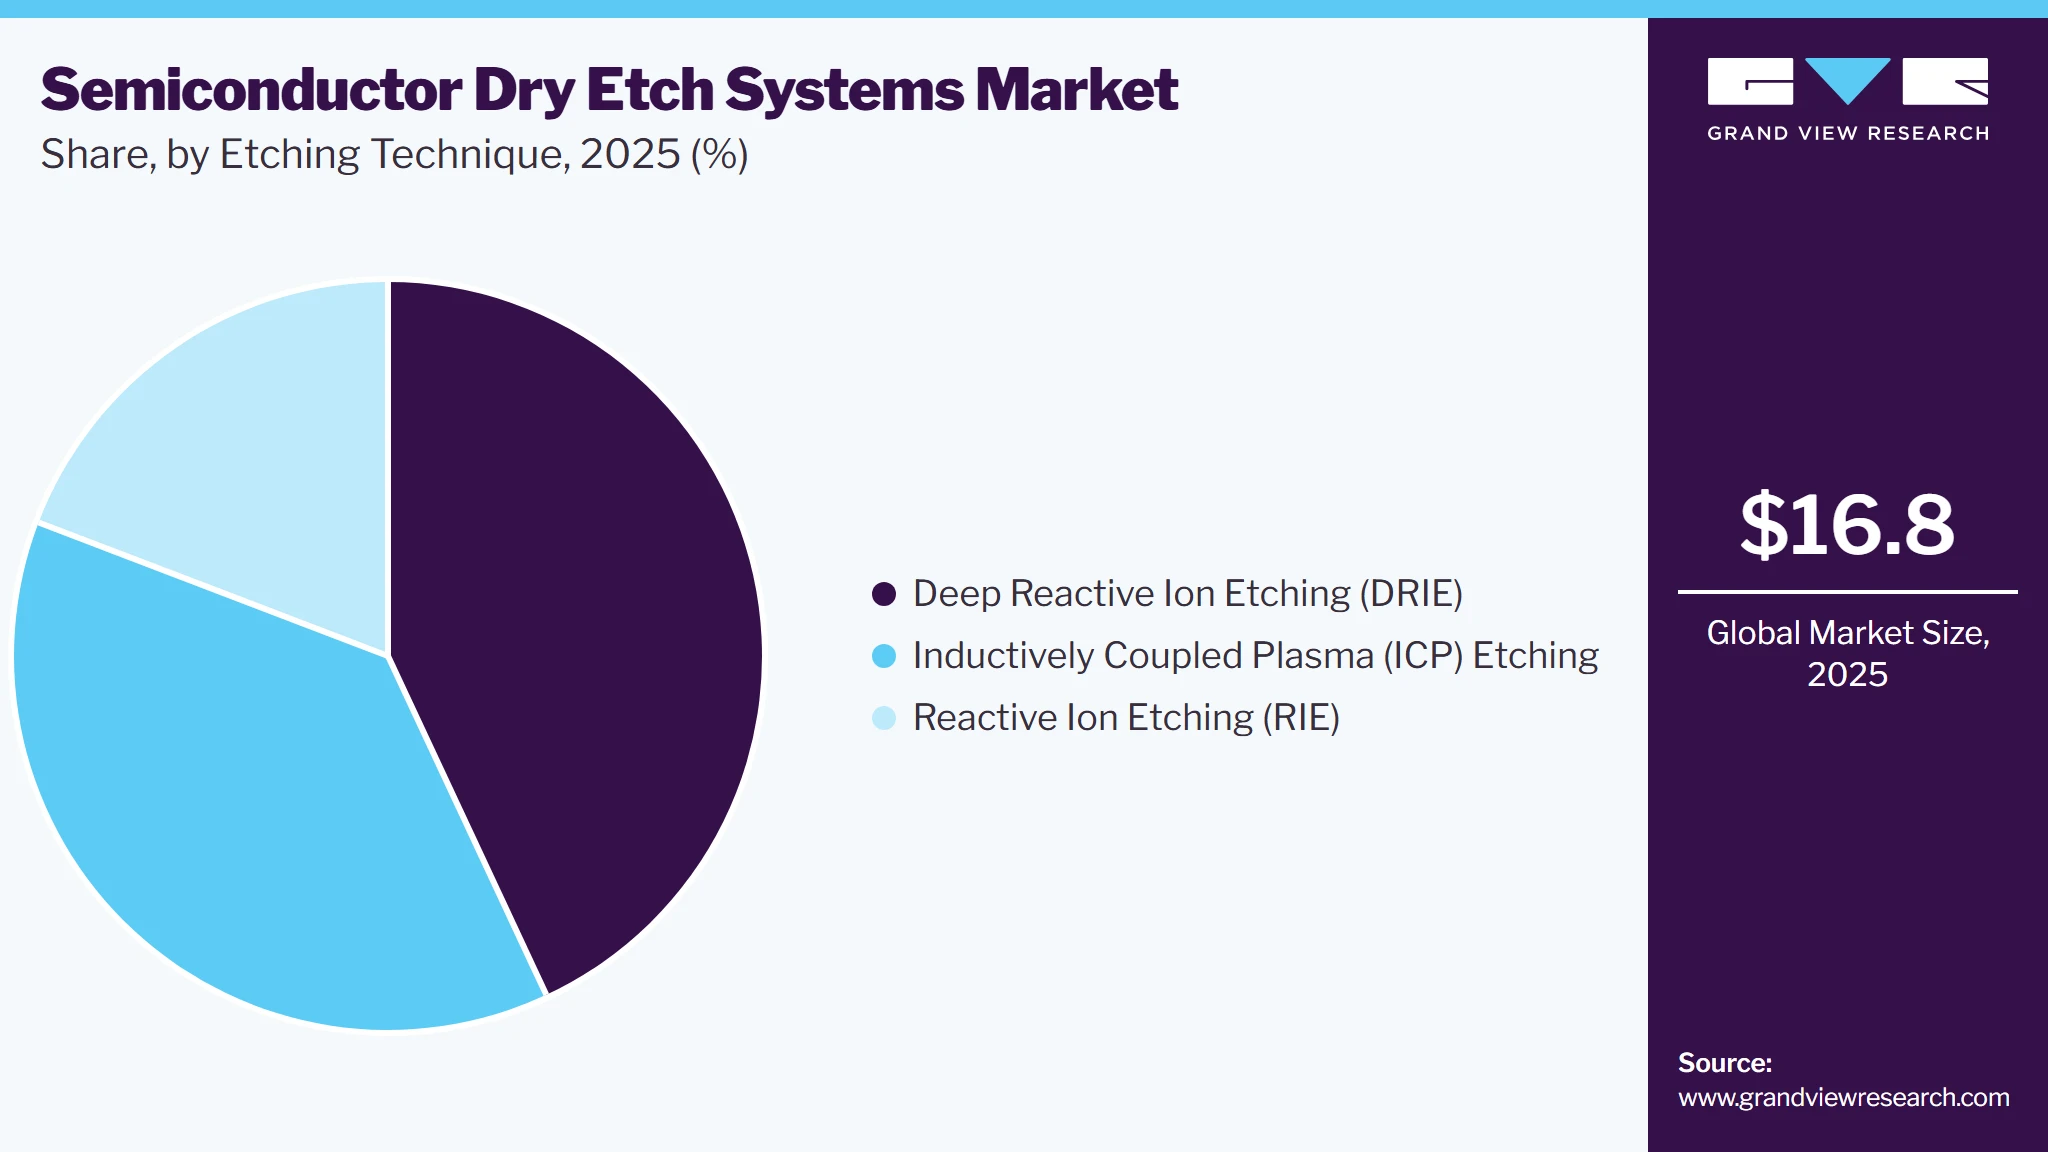
- By etching technique: Deep reactive ion etching (DRIE) segment held the largest market share of 43.0% in 2025.
- By application: Logic and memory segment held the largest market share of 52.1% in 2025.
- By end use: Consumer electronics segment held the largest market share of 46.5% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (69.0% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 16.8 Billion
- Estimated market size in 2026: USD 17.7 Billion
- Projected market size by 2033: USD 25.5 Billion
- CAGR (2026-2033): 5.4%
Prism AI by Grand View Research Free to tryAsk a question about the semiconductor dry etch systems marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Manufacturers are focusing on developing innovative etching technologies such as deep reactive-ion etching (DRIE) and plasma etching, to cater to the complex fabrication needs of modern semiconductor devices. For instance, companies such as Applied Materials and Lam Research are leading the charge with their advanced etch systems that offer greater precision and control, enabling the production of smaller, more efficient semiconductor components. This trend towards miniaturization and enhanced performance is crucial for the proliferation of 5G technology and the expansion of cloud computing, further propelling the market forward. The market is driven by growing demand for semiconductors across a variety of applications, including consumer electronics, automotive, and industrial sectors. Dry etching plays a critical role in the semiconductor manufacturing process, allowing for the precise and controlled removal of material from the semiconductor wafer. This is essential for the creation of micro- and nano-scale features on semiconductors, which are integral for the functionality of modern electronic devices.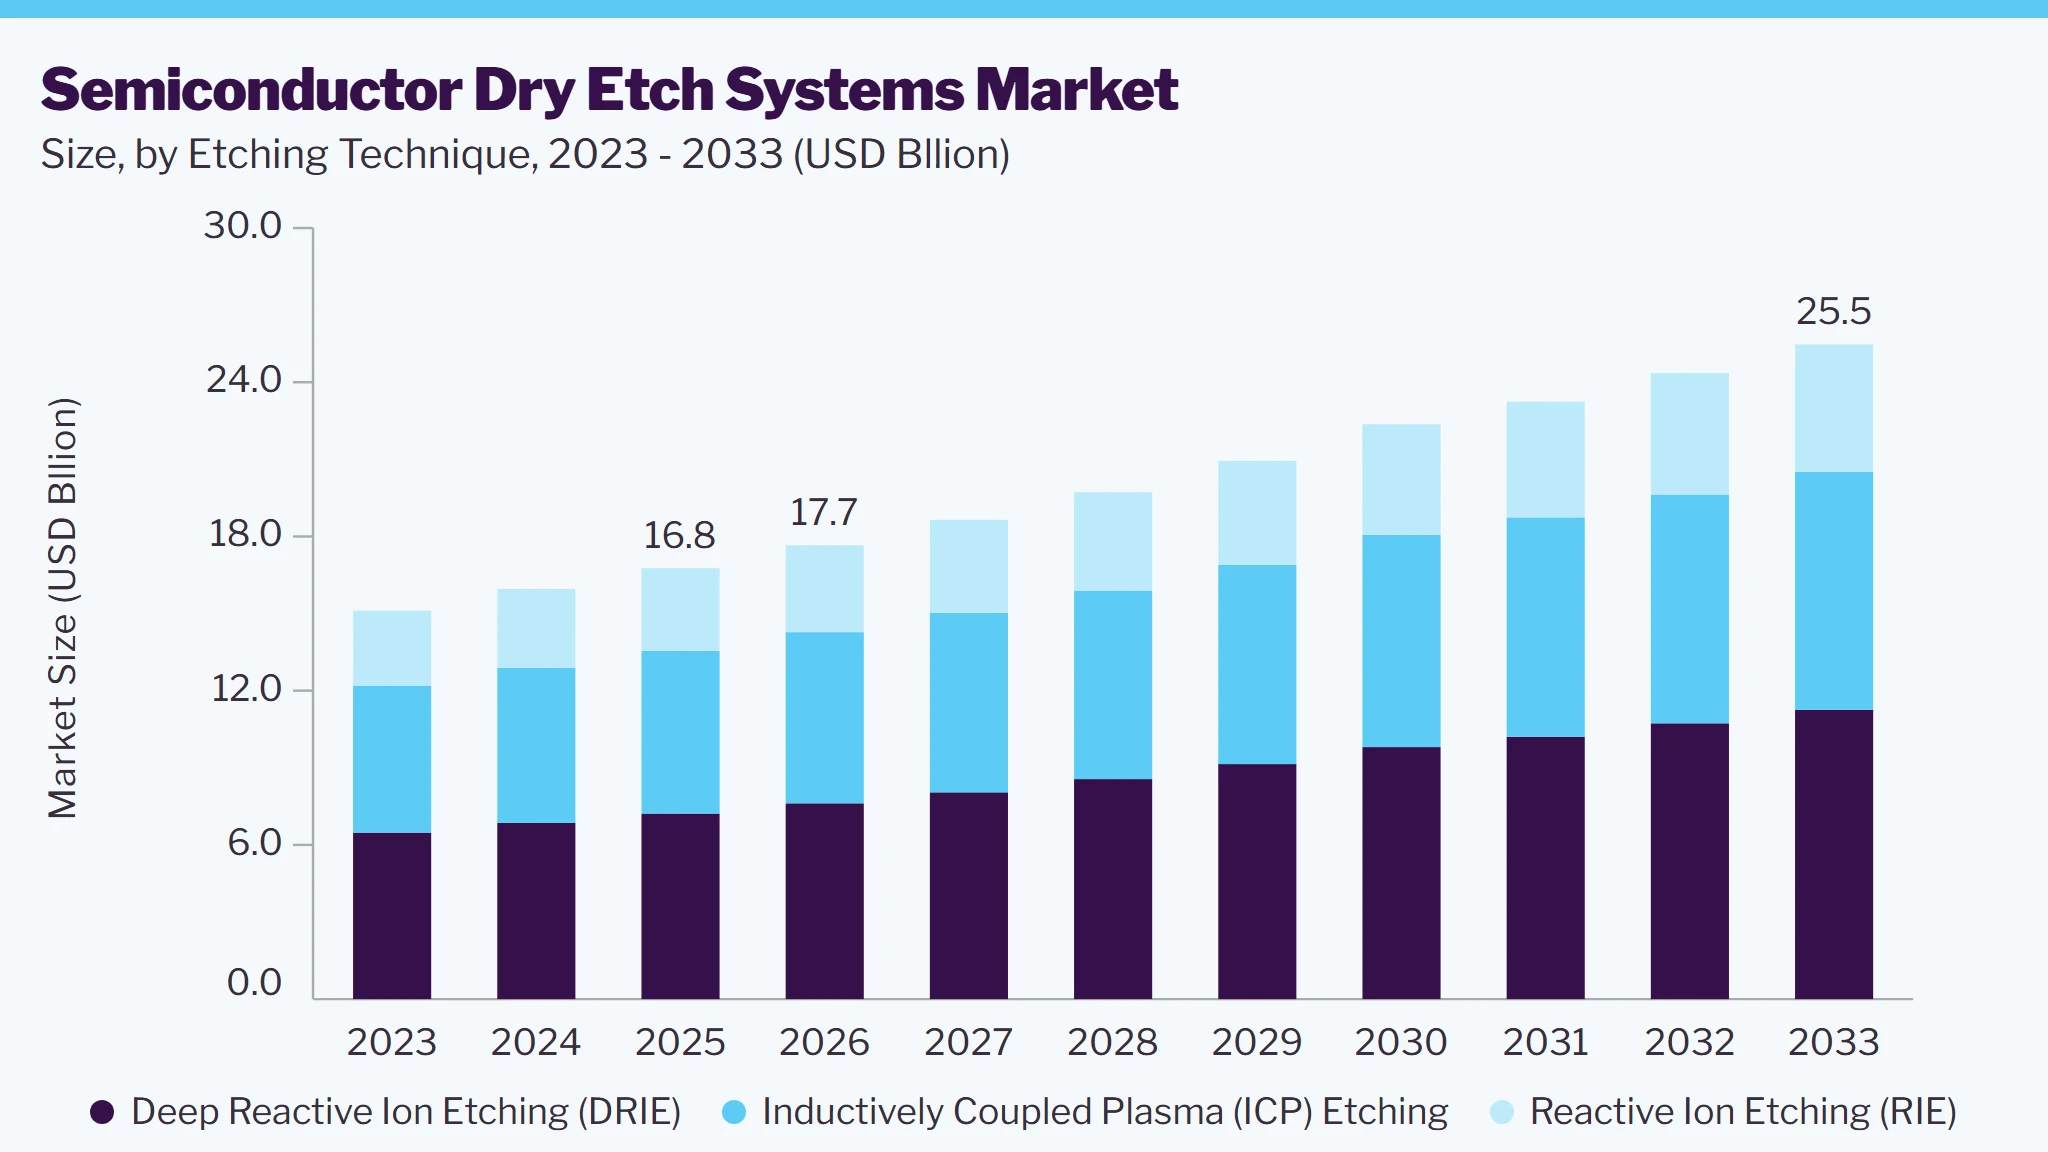 To learn more about this report, Download Free Sample Report
As devices become more integrated and compact, the requirement for more precise and efficient etching methods grows. Dry etch systems offer several advantages over traditional wet etching, such as higher selectivity, the ability to etch deep structures with vertical sidewalls, and the capacity to process complex patterns. These systems use plasma to remove material, enabling the etching to be more precisely controlled at the microscopic level, which is crucial for the production of advanced semiconductor devices.
Moreover, the transition towards smaller node sizes in semiconductor fabrication, such as the 7nm, 5nm, and even 3nm technology nodes, necessitates the use of advanced dry etching systems that can handle the intricate patterns and structures required at these scales. This miniaturization trend is pushing the boundaries of what's achievable with dry etching technology, driving continuous innovation in the field.
In addition, the development of new materials used in semiconductor devices, such as high-k dielectrics and metal gate materials, requires the development of new etching chemistries and processes. Dry etch systems must be adaptable and versatile to accommodate these materials, further driving the advancement of dry etch technology.
Market Dynamics
The semiconductor dry etch systems market is driven by increasing semiconductor fabrication, growing adoption of advanced process nodes, and rising demand for high-performance chips used in artificial intelligence, automotive electronics, 5G, data centers, and consumer devices. Manufacturers are investing in advanced plasma etching technologies to achieve precise pattern transfer and support complex device architectures. However, high equipment costs and process complexity remain challenges. Expanding investments in semiconductor manufacturing facilities and the transition toward advanced packaging technologies continue to create significant growth opportunities.
The increasing production of advanced semiconductor devices is a major driver for the semiconductor dry etch systems market. Shrinking chip geometries and the adoption of technologies such as FinFET, Gate-All-Around (GAA), and 3D NAND require highly precise plasma etching processes. Growing demand for processors, memory chips, sensors, and power semiconductors across artificial intelligence, electric vehicles, consumer electronics, and telecommunications is encouraging semiconductor manufacturers to expand fabrication capacity, thereby increasing demand for advanced dry etch systems.
Semiconductor dry etch systems require significant capital investment due to their advanced plasma generation, vacuum systems, precision controls, and contamination management technologies. In addition to high acquisition costs, manufacturers incur substantial expenses for maintenance, process optimization, skilled personnel, and cleanroom infrastructure. These factors increase the total cost of ownership, making it difficult for smaller semiconductor manufacturers and emerging fabrication facilities to adopt advanced dry etch equipment, particularly during periods of uncertain semiconductor demand.
Governments and semiconductor companies are investing heavily in new wafer fabrication facilities to strengthen domestic chip production and supply chain resilience. These investments are increasing demand for advanced semiconductor manufacturing equipment, including dry etch systems. New fabs designed for advanced logic, memory, compound semiconductors, and power electronics require high-precision etching technologies to support next-generation chip architectures. As fabrication capacity expands across regions, equipment suppliers have significant opportunities to provide innovative dry etch solutions with improved productivity and process performance.
Analyst Perspective
The semiconductor dry etch systems market is expected to witness growth, driven by increasing investments in advanced semiconductor fabrication and rising demand for high-performance chips across artificial intelligence, automotive electronics, 5G, data centers, and consumer electronics. The transition to smaller process nodes, 3D device architectures, and advanced packaging technologies is increasing the need for highly precise plasma etching solutions. Continuous innovations in etch process control, automation, and productivity are further supporting market expansion. Companies focusing on next-generation etching technologies, strategic collaborations with semiconductor manufacturers, and expansion of global service capabilities are likely to strengthen their competitive position over the forecast period.
Drivers, Opportunities & Restraints
In the domain of semiconductor fabrication, dry etch systems play a crucial role in shaping and defining the microscopic structures that constitute a semiconductor device. The demand for semiconductor dry etch systems is majorly driven by the relentless pursuit of miniaturization in the electronics industry, the growing complexity of semiconductor device architectures, and the pervasive demand for higher performance and lower power consumption in electronic devices. These factors necessitate the use of advanced etching technologies that can precisely sculpt semiconductor materials at the nanometer scale, fostering innovations in dry etch systems.
However, the sector faces certain restraints, including the high cost of equipment and the complex technical requirements for integrating advanced dry etch systems into existing production lines. The sophisticated nature of these systems demands significant capital investment and a highly skilled workforce to operate and maintain them. In addition, the stringent environmental and safety regulations related to the handling and disposal of the hazardous materials used in etching processes pose challenges to the industry, necessitating continuous advancements in cleaner and safer etching technologies.
Despite these constraints, opportunities abound in the market. The exponential growth in the Internet of Things (IoT), artificial intelligence (AI), and 5G technologies is driving the need for more advanced semiconductors, subsequently fueling the demand for sophisticated dry etch systems capable of manufacturing these components. Moreover, the push towards electric vehicles and renewable energy sources is opening new avenues for specialized semiconductor applications, offering lucrative prospects for the development and deployment of innovative dry etching technologies that can meet these emerging needs.
Etching Technique Insights
“The demand for Deep Reactive Ion Etching (DRIE) etching technique segment is expected to grow at a significant CAGR of 5.7% from 2026 to 2033 in terms of revenue”
Based on etching technique, the deep reactive ion etching (DRIE) segment led the market with the largest revenue share of 43.0% in 2025. Deep Reactive Ion Etching (DRIE) is a highly anisotropic etch process used in microfabrication to create deep, steep-sided holes and trenches in wafers or substrates, often with high aspect ratios. It's a variant of reactive ion etching (RIE) that utilizes cycles of etching and passivation to achieve depths that can be several hundred microns, with precision and uniformity. The demand for DRIE has surged with the advancement of microelectromechanical systems (MEMS), semiconductor manufacturing, and microfluidics, where precise deep etching is critical for the functionality of devices such as accelerometers, microfluidic devices, and intricate 3D structures in silicon.
 To learn more about this report, Download Free Sample Report
Reactive Ion Etching (RIE) is a versatile and widely used etching technique in the semiconductor industry that employs chemically reactive plasma to remove targeted material from the surface of substrates. RIE is known for its ability to provide anisotropic etch profiles, which are essential for creating well-defined patterns with high resolution. The demand for RIE technology comes from its critical role in the fabrication of electronic components, including integrated circuits (ICs) and microelectronic devices, where precise pattern transfer and material shaping are fundamental. Its ability to etch a variety of materials with control over the etch rate and profile makes it indispensable in the production of semiconductors and nanotechnology devices.
Application Insights
“The demand for power devices application segment is expected to grow at a significant CAGR of 6.1% from 2026 to 2033 in terms of revenue”
Based on application, the logic and memory segment led the market with the largest revenue share of 52.1% in 2025. The semiconductor dry etch systems are indispensable for the production of advanced logic chips, which form the brains of computers, smartphones, and countless other digital devices. The etching process enables the creation of intricate patterns on silicon wafers, defining the microscopic transistors and circuits that process information. As the demand for faster, more efficient computing grows, the precision and capabilities of dry etch technologies continue to advance, allowing for the scaling down of chip features and the enhancement of performance and functionality.
Power devices play a crucial role in managing and converting electrical energy in various applications, from automotive to renewable energy systems. The semiconductor dry etch process is essential in the fabrication of these devices, allowing for the precise shaping and patterning of materials to achieve optimal performance. Through etching techniques, manufacturers can create components that withstand high voltages and currents, significantly improving energy efficiency and reliability in power systems.
End-use Insights
“The demand for telecommunications end use segment is expected to grow at a significant CAGR of 6.2% from 2026 to 2033 in terms of revenue”
Based on end use, the consumer electronics segment led the market with the largest revenue share of 46.5% in 2025. The consumer electronics sector significantly drives the demand for semiconductor dry etch systems, primarily due to the relentless pursuit of more compact, efficient, and powerful devices. As consumers increasingly demand smartphones, laptops, wearables, and other smart devices with enhanced functionalities and performance, manufacturers are pushed to innovate and scale down components without compromising on capability. This miniaturization trend necessitates the use of advanced semiconductor dry etch systems that can precisely shape and create the complex and intricate structures needed for the latest generation of microchips and electronic components. The push for higher density chips, more memory, and faster processing speeds directly translates to a growing need for sophisticated etching systems that can meet these exacting standards with high throughput and efficiency.
In the broader electronics industry, the demand for semiconductor dry etch systems is fueled by the expansion of applications beyond traditional consumer electronics, into areas such as automotive, healthcare, and industrial automation. As these sectors increasingly incorporate electronic components and Internet of Things (IoT) connectivity into their products, the requirement for semiconductors that can operate reliably under various conditions intensifies. This diversification of applications broadens the market for semiconductor dry etch systems, as they are critical in manufacturing sensors, controllers, and other semiconductor devices that these new applications demand. The versatility and precision offered by dry etch systems are indispensable for producing the wide range of semiconductor components needed to support the electrification and digitalization of virtually every industry, thereby driving sustained demand in the semiconductor dry etch systems market.
Regional Insights
North America, particularly the United States, continues to be a significant market for semiconductor dry etch systems, driven by its strong research and development ecosystem and the presence of major semiconductor companies. The region's focus on cutting-edge technologies, such as artificial intelligence (AI), 5G, and quantum computing, necessitates the use of advanced semiconductor manufacturing processes, including dry etching. Furthermore, initiatives to bolster domestic semiconductor manufacturing capacity and reduce dependence on foreign supply chains have led to increased investments in semiconductor production facilities, further amplifying the demand for high-precision dry etch systems.
 To learn more about this report, Download Free Sample Report
Asia Pacific Semiconductor Dry Etch Systems Market
“China to witness fastest market growth at 7.0% CAGR”
Asia Pacific dominated the semiconductor dry etch systems market with the largest revenue share of 69.0% in 2025. Within the region, excluding China, countries like South Korea, Taiwan, and Japan are significant contributors to the demand for semiconductor dry etch systems. This region is home to some of the world's largest semiconductor manufacturers, who are continually expanding their production capabilities and investing in the latest manufacturing technologies to maintain a competitive edge in the global market. The push towards smaller, more efficient semiconductor devices, along with the expansion of semiconductor applications in automotive and industrial sectors, drives the demand for sophisticated dry etch systems in these countries.
The semiconductor dry etch systems market in the China held the largest share in the Asia Pacific region in 2025, The demand for semiconductor dry etch system primarily driven by the country's ambitious plans to boost its domestic semiconductor industry and reduction reliance on foreign technology. With significant investments from both the government and private sector into new fabrication plants and research and development, there is a heightened need for advanced semiconductor manufacturing equipment, including dry etch systems. This demand is further fueled by the growing consumption of consumer electronics within the country, making China a key market for semiconductor equipment suppliers.
Europe Semiconductor Dry Etch Systems Market Trends
In Europe, the demand for semiconductor dry etch systems is growing steadily, supported by the region's focus on automotive, industrial, and power electronics. European semiconductor manufacturers are investing in advanced manufacturing technologies to meet the increasing requirements for power efficiency, miniaturization, and high performance in these applications. The European Union's commitment to digitalization and sustainability also plays a role in driving the semiconductor industry's growth, thereby increasing the need for state-of-the-art dry etch systems to support the production of innovative semiconductor devices.
Key Semiconductor Dry Etch Systems Company Insights
Some key players operating in the market include Nitto Denko Corporation, and Applied Materials Inc., among others.
-
Meyer Industries, Inc. is a premier name in the manufacturing of bulk material handling and food processing equipment. Meyer Industries, known for its innovative solutions, specializes in a wide range of products from vibratory conveyors and bucket elevators to mix-blend systems and more. The company prides itself on delivering high-quality, custom-engineered systems that cater to the specific needs of its clients across various industries, including food processing, pharmaceuticals, and chemicals. Meyer Industries combines state-of-the-art technology with practical design to provide systems that enhance efficiency and productivity for its customers.
-
Syntron Material Handling stands out as a global leader in material handling solutions and manufacturing of conveying and vibratory equipment. The company's rich history and extensive experience have established it as a trusted provider of high-quality feeders, screens, and conveyors. Syntron Material Handling is dedicated to improving the productivity and efficiency of its customers’ operations through innovative designs and technology. The company serves a diverse range of industries, including mining, aggregates, and food processing, offering solutions that are tailored to meet the unique requirements of each sector.
Ted Pella, Inc., and H-Square Corporation are some emerging market participants in the systems market.
-
Ted Pella, Inc. is a family-owned American company specializing in the supply of tools, materials, and equipment for microscopy and related fields. Since its establishment in 1968, the company has grown to be a trusted name among scientists, researchers, and professionals in material science, electronics, and life sciences. Offering a comprehensive range of products, including electron microscopy supplies, precision instruments, and sample preparation tools, Ted Pella, Inc. is dedicated to supporting the scientific community with high-quality solutions that facilitate advanced research and discovery. Their commitment to customer service and technical support underscores their role as a key resource for innovative and reliable scientific tools and materials.
-
H-Square Corporation is a leading provider of semiconductor handling solutions, renowned for designing and manufacturing ergonomic tools and equipment that enhance efficiency and safety in the semiconductor fabrication process. Established in the 1970s, H-Square has built a reputation for excellence by offering a wide range of products, including wafer handling tools, vacuum wands, and custom equipment designed to meet specific customer needs. Their commitment to innovation, quality, and customer satisfaction has made H-Square a preferred partner for semiconductor manufacturers worldwide, helping to streamline operations and protect valuable semiconductor wafers during production and inspection processes. With a focus on addressing the unique challenges of the semiconductor industry, H-Square continues to contribute to the advancement of semiconductor manufacturing technology.
Key Semiconductor Dry Etch Systems Companies
The following key companies have been profiled for this study on the semiconductor dry etch systems market.
-
Shin-Etsu Chemical Co., Ltd.
-
Nitto Denko Corporation
-
H-Square Corporation
-
Ted Pella, Inc.
-
AMAC Technologies
-
SIPEL ELECTRONIC SA
-
Hefei TREC Precision Equipment Co., Ltd.
-
Applied Materials Inc.
-
Tokyo Electron Limited
-
Lam Research Corporation
-
KLA Corporation
Market Participant Categorization
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g. Applied Materials Inc.; Tokyo Electron Limited; Lam Research Corporation; KLA Corporation; Shin-Etsu Chemical Co., Ltd.; Nitto Denko Corporation)
- Focused on expanding advanced dry etch platforms for leading-edge logic, memory, power semiconductor, and advanced packaging applications.
- Invested heavily in plasma process innovation, AI-enabled process control, automation, and high-throughput manufacturing solutions.
- Strengthened collaborations with semiconductor foundries, integrated device manufacturers (IDMs), and research institutes while expanding global service and support capabilities.
- Strong technological expertise and extensive intellectual property in semiconductor process equipment.
- Broad global customer base among leading semiconductor manufacturers.
- Advanced R&D capabilities supporting next-generation process nodes and high-precision plasma etching.
- Comprehensive after-sales service, process optimization, and application support.
- High dependence on semiconductor capital expenditure cycles.
- Significant R&D and manufacturing costs associated with continuous technology advancement.
- Exposure to geopolitical trade restrictions and semiconductor supply chain disruptions.
- Long product qualification and customer approval cycles.
Emerging & Regional Players (e.g H-Square Corporation; Ted Pella, Inc.; AMAC Technologies; SIPEL ELECTRONIC SA; Hefei TREC Precision Equipment Co., Ltd.)
- Focused on specialized dry etch solutions, semiconductor consumables, and customized process equipment for regional semiconductor manufacturers and research institutions.
- Expanded offerings for MEMS, sensors, compound semiconductors, and laboratory-scale semiconductor fabrication.
- Emphasized cost-effective solutions, localized technical support, and application-specific product development.
- Strong flexibility in addressing customer-specific process requirements.
- Competitive pricing and faster response to regional market demand.
- Ability to develop customized solutions for niche semiconductor manufacturing applications.
- Lower global market presence and limited access to large semiconductor manufacturers.
- Smaller R&D budgets compared to multinational equipment suppliers.
- Limited manufacturing scale and international distribution capabilities.
Recent Developments
-
In March 2021, Tokyo Electron (TEL) introduced its newest plasma etch systems, the Impressio 1800 PICP Pro and Betelex 1800 PICP Pro. These systems are equipped with the innovative PICP Pro chamber, designed for high-resolution processing of 6th generation (G6: 1,500 mm x 1,850 mm) glass substrates.
Semiconductor Dry Etch Systems Market Report Scope
Report Attribute
Details
Market size in 2025
USD 16.8 billion
Estimated market size in 2026
USD 17.7 billion
Projected market size by 2033
USD 25.5 billion
Growth rate
CAGR of 5.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Etching technique, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; Italy; UK; Spain; China; Japan; India; South Korea; Taiwan; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Shin-Etsu Chemical Co., Ltd.; Nitto Denko Corporation; H-Square Corporation; Ted Pella, Inc.; AMAC Technologies; SIPEL ELECTRONIC SA; Hefei TREC Precision Equipment Co., Ltd.; Applied Materials Inc.; Tokyo Electron Limited; Lam Research Corporation; KLA Corporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Semiconductor Dry Etch Systems Market Report Segmentation
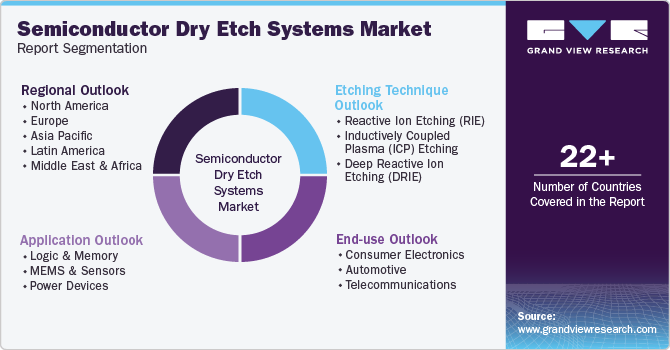
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global semiconductor dry etch systems based on the etching technique, application, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Etching Technique Outlook (Revenue, USD Billion, 2021 - 2033)
-
Reactive Ion Etching (RIE)
-
Inductively Coupled Plasma (ICP) Etching
-
Deep Reactive Ion Etching (DRIE)
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Logic and Memory
-
MEMS and Sensors
-
Power Devices
-
-
End-use Outlook (Revenue, USD Billion; 2021 - 2033)
-
Consumer Electronics
-
Automotive
-
Telecommunications
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Taiwan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The semiconductor dry etch systems market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each semiconductor dry etch systems segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Etching Technique
Revenue Capture Definition
Reactive Ion Etching (RIE)
Revenue is generated from the sale of reactive ion etching systems used for precision plasma etching in semiconductor manufacturing.
Inductively Coupled Plasma (ICP) Etching
Revenue is generated from the sale of inductively coupled plasma etching systems used for high-density and high-precision semiconductor etching.
Deep Reactive Ion Etching (DRIE)
Revenue is generated from the sale of deep reactive ion etching systems used for high-aspect-ratio silicon etching applications.
Application
Revenue Capture Definition
Logic and Memory
Revenue is generated from the sale of semiconductor dry etch systems used in the fabrication of logic and memory chips.
MEMS and Sensors
Revenue is generated from the sale of semiconductor dry etch systems used in the manufacturing of MEMS devices and semiconductor sensors.
Power Devices
Revenue is generated from the sale of semiconductor dry etch systems used in the production of power semiconductor devices.
End Use
Revenue Capture Definition
Consumer Electronics
Revenue is generated from the sale of semiconductor dry etch systems used to manufacture chips for consumer electronic devices.
Automotive
Revenue is generated from the sale of semiconductor dry etch systems used to manufacture automotive semiconductor components.
Telecommunications
Revenue is generated from the sale of semiconductor dry etch systems used to manufacture semiconductor devices for telecommunications applications.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Semiconductor Fabrication Demand Layer
Which sectors generate demand for semiconductor dry etch systems?
The estimation begins by evaluating demand across logic and memory, foundries, integrated device manufacturers (IDMs), MEMS and sensors, power semiconductor manufacturing, and advanced packaging facilities. Market demand is influenced by wafer fabrication capacity, semiconductor production volumes, technology node migration, and investments in new fabrication plants.
02
Etching Technology Layer
Which etching technologies drive market demand?
This layer refines demand by assessing the adoption of Reactive Ion Etching (RIE), Inductively Coupled Plasma (ICP) Etching, and Deep Reactive Ion Etching (DRIE). Demand is influenced by etch precision, process uniformity, aspect ratio requirements, throughput, compatibility with advanced device architectures, and manufacturing efficiency.
03
Application and End-user Adoption Layer
What determines semiconductor dry etch systems demand?
Market demand is estimated by evaluating deployment across logic and memory, MEMS and sensors, and power device manufacturing serving consumer electronics, automotive, telecommunications, industrial electronics, and other semiconductor applications. Growth in chip demand, semiconductor fabrication investments, advanced packaging adoption, and equipment replacement cycles determine product adoption.
04
Revenue Layer
How is total market revenue calculated?
Revenue is estimated by aggregating sales of semiconductor dry etch systems across etching technologies, applications, end-use industries, and regional markets. Equipment pricing, wafer fabrication capacity additions, semiconductor capital expenditure, manufacturer revenues, distributor sales, equipment replacement demand, and regional semiconductor production are incorporated to validate the overall market size.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Delivered detailed market sizing, forecast analysis, and demand assessment for the semiconductor dry etch systems market across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Country-level analysis was further conducted across logic & memory, MEMS & sensors, power devices, consumer electronics, automotive, and telecommunications applications.
Helped identify high-growth semiconductor manufacturing hubs and future investment opportunities across regional fabrication ecosystems.
Opportunity Assessment
Identified and analyzed emerging growth opportunities driven by increasing semiconductor fab investments, adoption of advanced process nodes, expansion of AI and high-performance computing, growing electric vehicle semiconductor demand, and rising advanced packaging requirements.
Helped stakeholders prioritize high-growth investment opportunities and strategic expansion areas within the semiconductor equipment industry.
Competitive benchmarking
Delivered comprehensive market share analysis for leading semiconductor dry etch system manufacturers, covering revenue contribution, technology leadership, regional presence, product portfolio, and competitive intensity within the market.
Assisted in evaluating market concentration, competitive positioning, and technology leadership among key industry participants.
Frequently Asked Questions About This Report
The global semiconductor dry etch systems market size was valued at USD 16.8 billion in 2025 and is estimated at USD 17.7 billion for 2026.
The global semiconductor dry etch systems market is expected to grow at a CAGR of 5.4% from 2026 to 2033, reaching USD 25.5 billion by 2033.
Based on application, the logic and memory segment led the market with the largest revenue share of 52.1% in 2025.
Based on end use, the consumer electronics segment led the market with the largest revenue share of 46.5% in 2025.
Asia Pacific dominated the semiconductor dry etch systems market with the largest revenue share of 69 .0% in 2025.
The semiconductor dry etch systems market in the China held the largest share in the Asia Pacific region in 2025.
Based on etching technique, the Deep Reactive Ion Etching (DRIE) segment led the market with the largest revenue share of 43.0% in 2025.
Key players include Shin-Etsu Chemical Co., Ltd.; Nitto Denko Corporation; H-Square Corporation; Ted Pella, Inc.; AMAC Technologies; SIPEL ELECTRONIC SA; Hefei TREC Precision Equipment Co., Ltd.; Applied Materials Inc.; Tokyo Electron Limited; Lam Research Corporation; KLA Corporation
The semiconductor dry etch systems market is experiencing significant growth, driven by the escalating demand for consumer electronics, advancements in IoT, and the burgeoning automotive electronics sector.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


