
- Home
- »
- Consumer F&B
- »
-
U.S. Protein Supplements Market Size Report, 2026-2033GVR Report cover

U.S. Protein Supplements Market (2026 - 2033)
Size, Share & Trends Analysis Report By Source (Animal-based Protein Supplements, Plant-based Protein Supplements), By Product (Protein Powder, RTD), By Application (Sports Nutrition), By Distribution Channel, And Segment Forecasts
Market Size, 2025
$10.2BMarket Estimate, 2026
$10.8BMarket Forecast, 2033
$20.4BCAGR, 2026–2033
9.4%U.S. Protein Supplements Market Summary
The U.S. protein supplements market size was valued at USD 10.2 billion in 2025 and is expected to grow from USD 10.8 billion in 2026 to USD 20.4 billion by 2033, at a CAGR of 9.4% from 2026 to 2033. The growth is driven by the rising consumer focus on protein intake, fitness, and active lifestyles. Customers are seeking ingredients with clean labels, high efficacy, and minimal side effects.
Key Market Trends & Insights
- By source: Animal-based protein supplements held the largest share of 58.6% in 2025.
- By product: Protein powder held the largest share of 48.7% in 2025.
- By application: Sports nutrition is expected to grow at the highest CAGR of 9.7% from 2026 to 2033.
- By distribution channel: Online stores held the largest share of 40.8% in 2025.
Market Size & Forecast
- Market Size in 2025: USD 10.2 Billion
- Estimated Market Size in 2026: USD 10.8 Billion
- Projected Market Size by 2033: USD 20.4 Billion
- CAGR (2026-2033): 9.4%
GVR research-powered AIAsk Prism AI about the U.S. protein supplements marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗
As a result, protein supplement manufacturers in the U.S. are developing blends of natural and synthetic ingredients that cater to the nutritional requirements of consumers across the country. Protein supplements within the sports nutrition category benefit from their association with performance, recovery, and muscle maintenance. Active consumers, fitness enthusiasts, and competitive athletes rely on protein powders, RTD shakes, and bars for efficient delivery of high-quality protein with minimal preparation time. The busy lifestyles of consumers further enhance the appeal of these convenient formats. At the same time, functional foods have emerged as a preferred protein source for the general population. Products such as Greek yogurt, high-protein snacks, fortified beverages, and protein-infused coffee allow individuals to increase protein intake across multiple eating occasions. These products address broader wellness goals, including appetite control, sustained energy, and healthier snacking, while maintaining familiar taste profiles.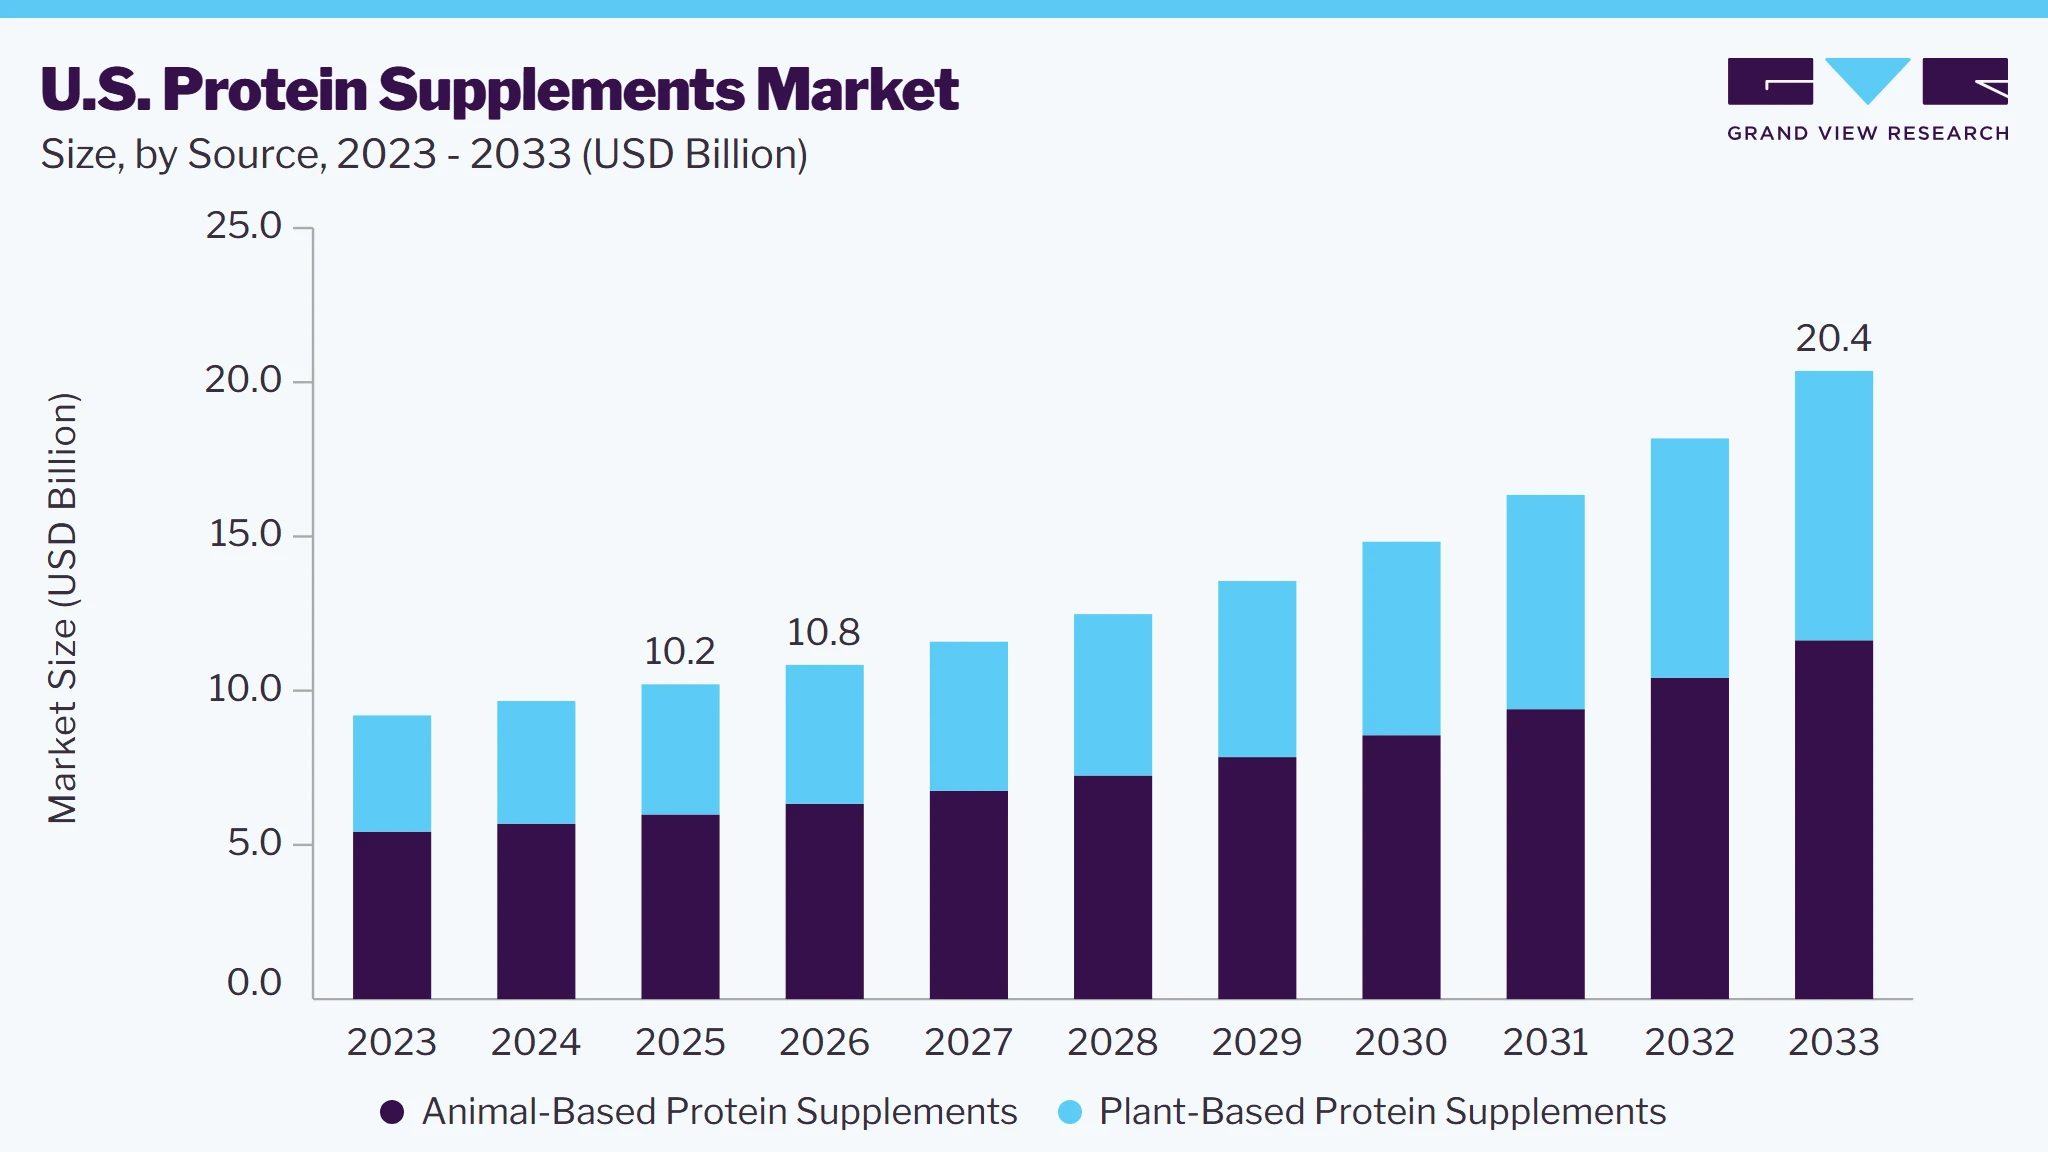 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Manufacturers in the U.S. protein supplements industry are increasingly focused on delivering higher-quality, cleaner, and more appealing products to meet evolving consumer expectations. Efforts are centered on improving ingredient transparency and product purity through the use of grass-fed whey, organic and non-GMO plant proteins, and third-party testing certifications. At the same time, companies are investing heavily in enhancing product texture and mouthfeel by improving solubility and reducing chalkiness, long-standing consumer concerns in protein powders and RTD beverages. For instance, in October 2025, PepsiCo expanded its “better-for-you” beverage portfolio by launching and reformulating three protein-focused drinks across its Propel, Muscle Milk, and Starbucks ready-to-drink coffee lines. New Propel Clear Protein powder with electrolytes and fiber targets functional hydration and GLP‑1 users. Muscle Milk is being reformulated into a smoother, shake-like drink without artificial sweeteners or colors, and Starbucks RTD coffee will get added protein, fiber, vitamins, and minerals to support all-day, health-oriented consumption occasions.
Packaging innovations also support growing demand for convenience and sustainability, with brands adopting single-serve sachets, portable RTD formats, and recyclable materials. Clear front-of-pack protein claims and functional benefits help simplify purchase decisions. Additionally, flavor innovation has become a major focus, expanding beyond traditional options into dessert-inspired, nostalgic, and globally influenced flavors to maintain consumer interest and reduce flavor fatigue.
Market Dynamics
Growing awareness of protein’s role in muscle health, energy, healthy aging, and overall wellness is encouraging more U.S. consumers to prioritize protein in their diets. According to the 2025 International Food Information Council (IFIC) Food & Health Survey, 70% of Americans reported trying to consume protein, making it the nutrient consumers were most actively trying to consume for the fifth consecutive year. In addition, 35% of consumers reported increasing their protein intake in the previous year, while more than 80% said they prioritize protein at least once a day. This broader interest in protein is supporting demand for convenient sources such as protein powders, shakes, bars, and other protein-enriched products.
Uncertainty regarding appropriate protein intake and how to assess protein quality can create challenges for consumers when selecting supplements. The 2025 IFIC protein survey found that 79% of Americans were either unaware or unsure of how much protein they should consume each day. Among consumers who believed they knew their daily requirement, 54% thought they should consume 50 grams or less per day. In addition, consumers do not always interpret “protein quality” according to scientific measures, with 40% associating high-quality protein with good taste, 29% with being free from additives, and 28% with being natural. This knowledge gap can make it difficult for consumers to compare protein sources, understand product claims, and select suitable supplements.
The growing focus on protein across everyday eating occasions is creating opportunities for manufacturers to develop convenient and functional protein supplements. Consumers are increasingly looking for products that fit easily into daily routines, while protein is being associated with benefits such as muscle health and strength, energy, endurance, and overall well-being. The 2025 IFIC survey found that 51% of Americans associated protein with muscle health/strength, and endurance; 45% with energy or reduced fatigue; and 35% with overall well-being. This creates opportunities for manufacturers to offer differentiated protein powders, RTD beverages, bars, and other convenient formats, while improving taste, texture, ingredient transparency, and nutritional information to address consumer expectations.
Analyst Perspective
The U.S. protein supplements market remains competitive, with established companies leveraging broad product portfolios, established distribution networks, and extensive nutrition expertise, while specialized players focus on targeted formulations, product innovation, and direct consumer engagement. Competition is increasingly shaped by demand for convenient formats, diverse protein sources, clean-label formulations, improved taste and texture, and products aligned with specific fitness and wellness goals. In the future, differentiation through formulation quality, product convenience, transparent labeling, flavor innovation, and wider omnichannel availability is expected to remain important for companies seeking to strengthen their position in the market.
Consumer Insights
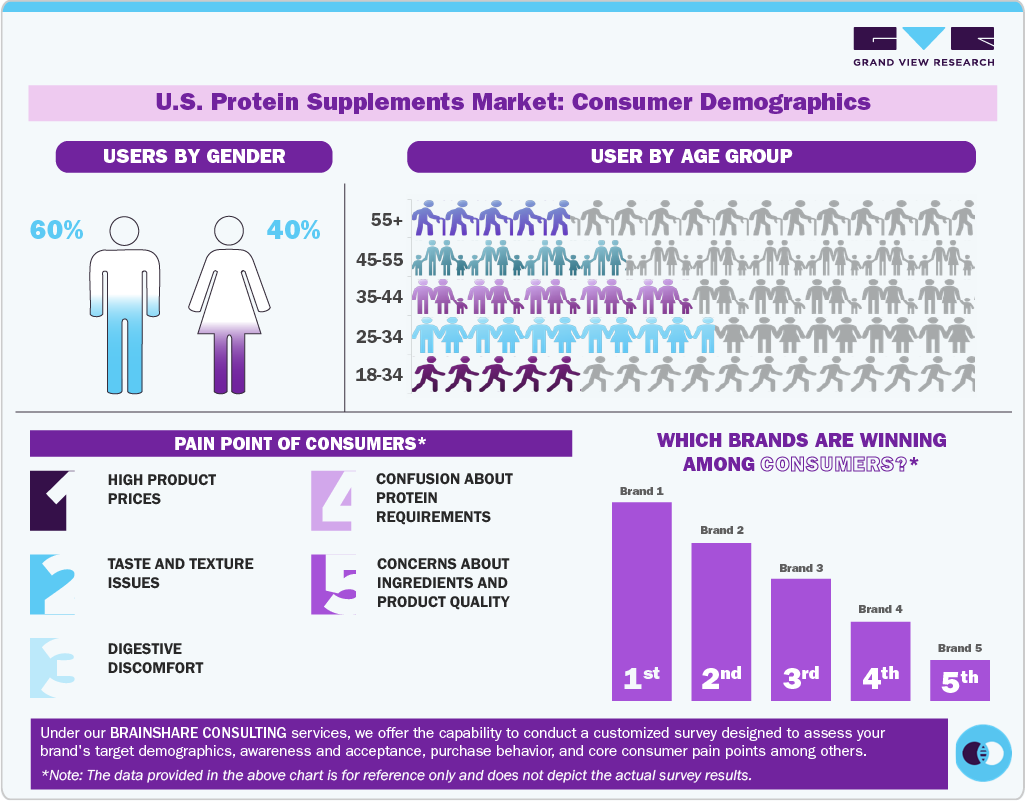
Consumer interest in protein supplementation in the U.S. has expanded significantly beyond traditional sports nutrition users. Growing awareness of the role of protein in satiety, weight management, metabolic health, muscle maintenance, and healthy aging has driven broader adoption across mainstream consumers. According to recent national surveys, a majority of Americans are consciously increasing their protein intake, reflecting a shift toward high-protein dietary patterns for everyday wellness rather than solely for athletic performance. The preference for convenient, nutrient-dense foods has accelerated the demand for protein powders, ready-to-drink (RTD) beverages, bars, and fortified snacks.
 To learn more about this report, Download Free Sample Report
Another key driver is the shift toward functional, protein-enriched foods that seamlessly integrate into daily eating routines. High-protein yogurts, cheese snacks, cereals, and coffee beverages are becoming preferred alternatives to traditional supplements, enabling consumers to meet protein goals without altering their lifestyle. The adoption of weight-management medications, such as GLP-1 agonists, has also increased protein demand, as users seek to maintain lean mass despite reduced caloric intake. The convergence of performance nutrition, wellness trends, and functional snacking has positioned protein as a core component of modern dietary behavior in the U.S.
 To learn more about this report, Download Free Sample Report
Source Insights
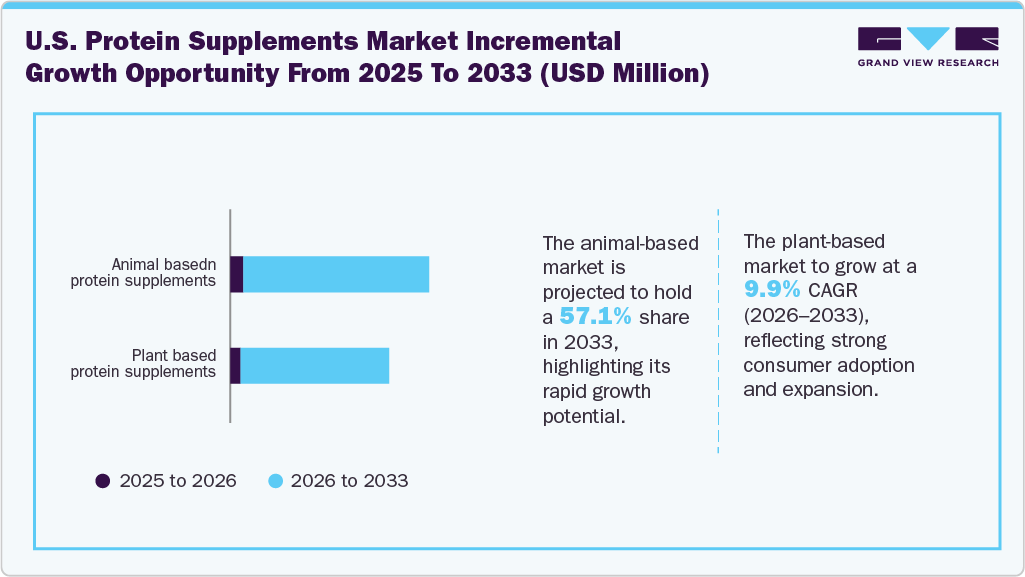
Animal-based protein supplements led the U.S. protein supplements industry, accounting for 58.6% of the market in 2025, owing to rising consumer focus on high-quality, complete protein sources that support muscle recovery, weight management, and overall wellness. Products derived from whey, casein, collagen, and egg protein offer superior amino acid profiles, particularly rich in essential and branched-chain amino acids, which are highly valued by fitness enthusiasts, aging adults, and individuals seeking effective nutritional support. According to the U.S. Dairy Export Council and USDA, per capita protein intake from dairy-derived products has steadily increased as consumers associate animal proteins with better digestibility, faster absorption, and clinically supported performance outcomes.
 To learn more about this report, Download Free Sample Report
Plant-based protein supplements are anticipated to grow at a CAGR of 9.9% from 2026 to 2033. A growing share of Americans is shifting toward plant-forward diets driven by concerns over digestive comfort, lactose intolerance, and the perceived health benefits of plant proteins compared with animal-derived alternatives. Industry surveys from organizations such as the Plant Based Foods Association indicate that consumers view plant proteins as gentler on the stomach, lower in saturated fat, and better aligned with wellness and weight-management goals. Environmental awareness also plays a significant role, as younger consumers in particular associate plant-based products with reduced carbon footprints and more ethical food systems.
Product Insights
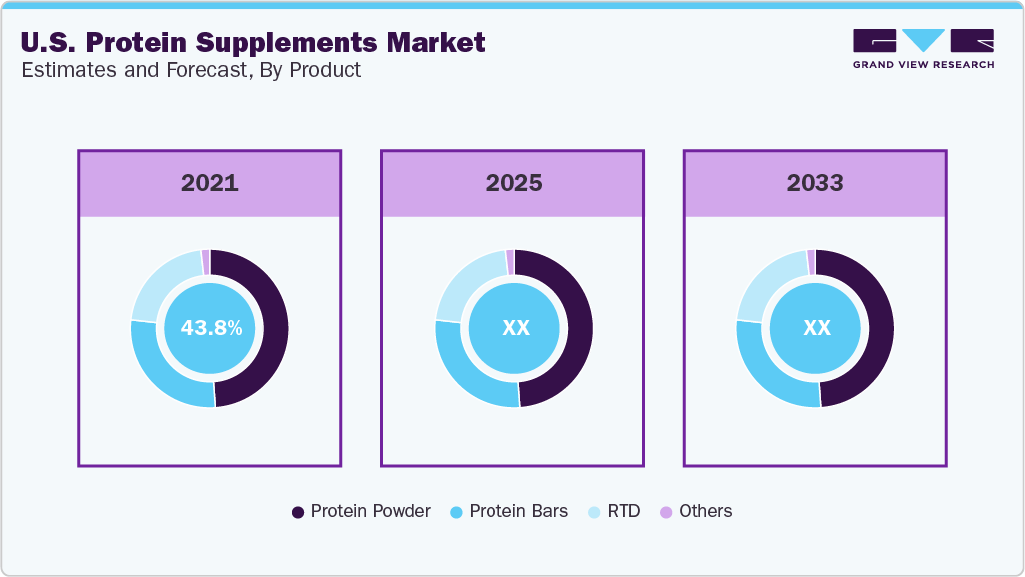
Protein powder dominated the U.S. protein supplements market, accounting for a revenue share of 48.7% in 2025. Protein powder demand in the U.S. is rising due to a combination of evolving health priorities, lifestyle changes, and broader consumer awareness around nutrition. Americans are increasingly focused on muscle maintenance, weight management, and overall wellness, driven by a growing fitness culture and the mainstream adoption of high-protein diets. According to industry associations such as the International Food Information Council (IFIC), a rising share of U.S. consumers reports actively increasing their protein intake, particularly from convenient sources. Protein powders offer an accessible, versatile, and cost-effective way to meet daily protein goals, appealing to a wide range of users, from athletes and gym-goers to older adults seeking to maintain muscle mass.
 To learn more about this report, Download Free Sample Report
RTD protein supplements are anticipated to grow at a CAGR of 10.5% from 2026 to 2033. Busy lifestyles and the shift toward on-the-go consumption have made RTD formats more appealing than traditional powders, which require preparation. Growing interest in fitness, weight management, and muscle recovery, driven by younger consumers, gym-goers, and health-conscious adults, has further strengthened demand. Additionally, advancements in formulation have improved taste, texture, and shelf stability, while brands now offer low-sugar, plant-based, and functional variants enriched with vitamins, probiotics, or energy-boosting ingredients. These innovations, coupled with broader adoption of protein-rich diets, have positioned RTD protein drinks as a convenient and accessible source of daily nutrition, fueling their continued growth in the U.S. market.
Application Insights
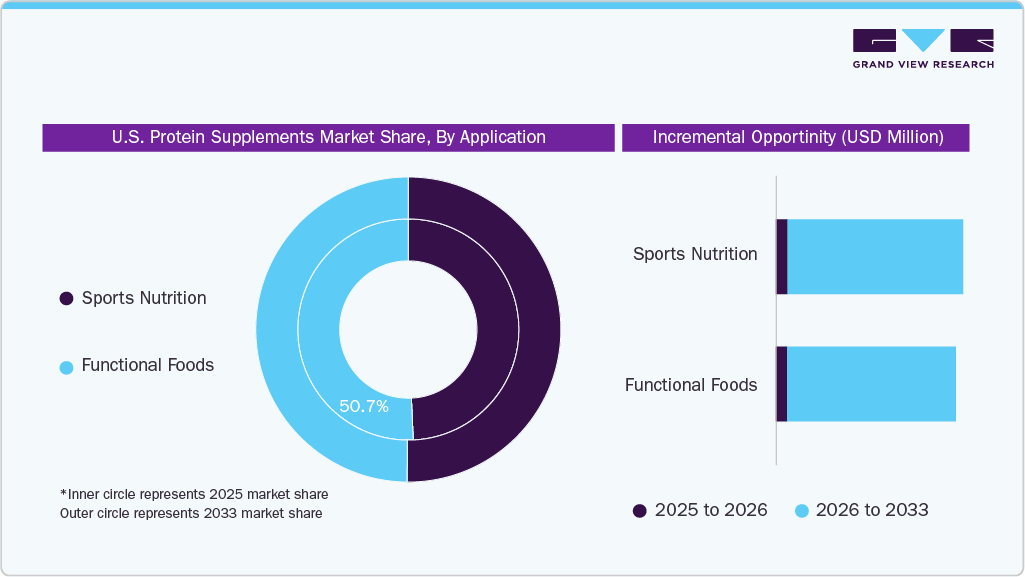
Protein supplements used for functional foods dominated the U.S. protein supplements industry, holding a revenue share of 50.7% in 2025, driven by increased awareness of the role of protein in muscle maintenance, weight management, and metabolic health. Consumers, especially millennials and older adults, are increasingly integrating protein-fortified products into daily diets beyond traditional shakes, including bars, snacks, cereals, and ready-to-eat meals. Growing participation in fitness activities and preventative health behaviors has heightened expectations for functional foods that deliver targeted benefits, such as enhanced satiety, improved recovery, and metabolic support. Additionally, innovations in formulation, taste, and texture have reduced barriers to adoption, enabling manufacturers to incorporate whey, plant-based, and specialty proteins into a broader range of mainstream products.
 To learn more about this report, Download Free Sample Report
Protein supplements used in sports nutrition are expected to grow at a CAGR of 9.7% from 2026 to 2033. Consumers today are more informed about the role of protein in supporting muscle synthesis, aiding post-exercise recovery, and enhancing overall physical performance, leading many athletes, recreational exercisers, and older adults to incorporate supplements into their diets. Additionally, the expansion of the functional foods and dietary supplements market, driven by product innovation, convenient formats (e.g., powders, bars, ready-to-drink shakes), and targeted formulations for specific goals such as weight management or strength training, has made protein supplementation more accessible and appealing.
Distribution Channel Insights
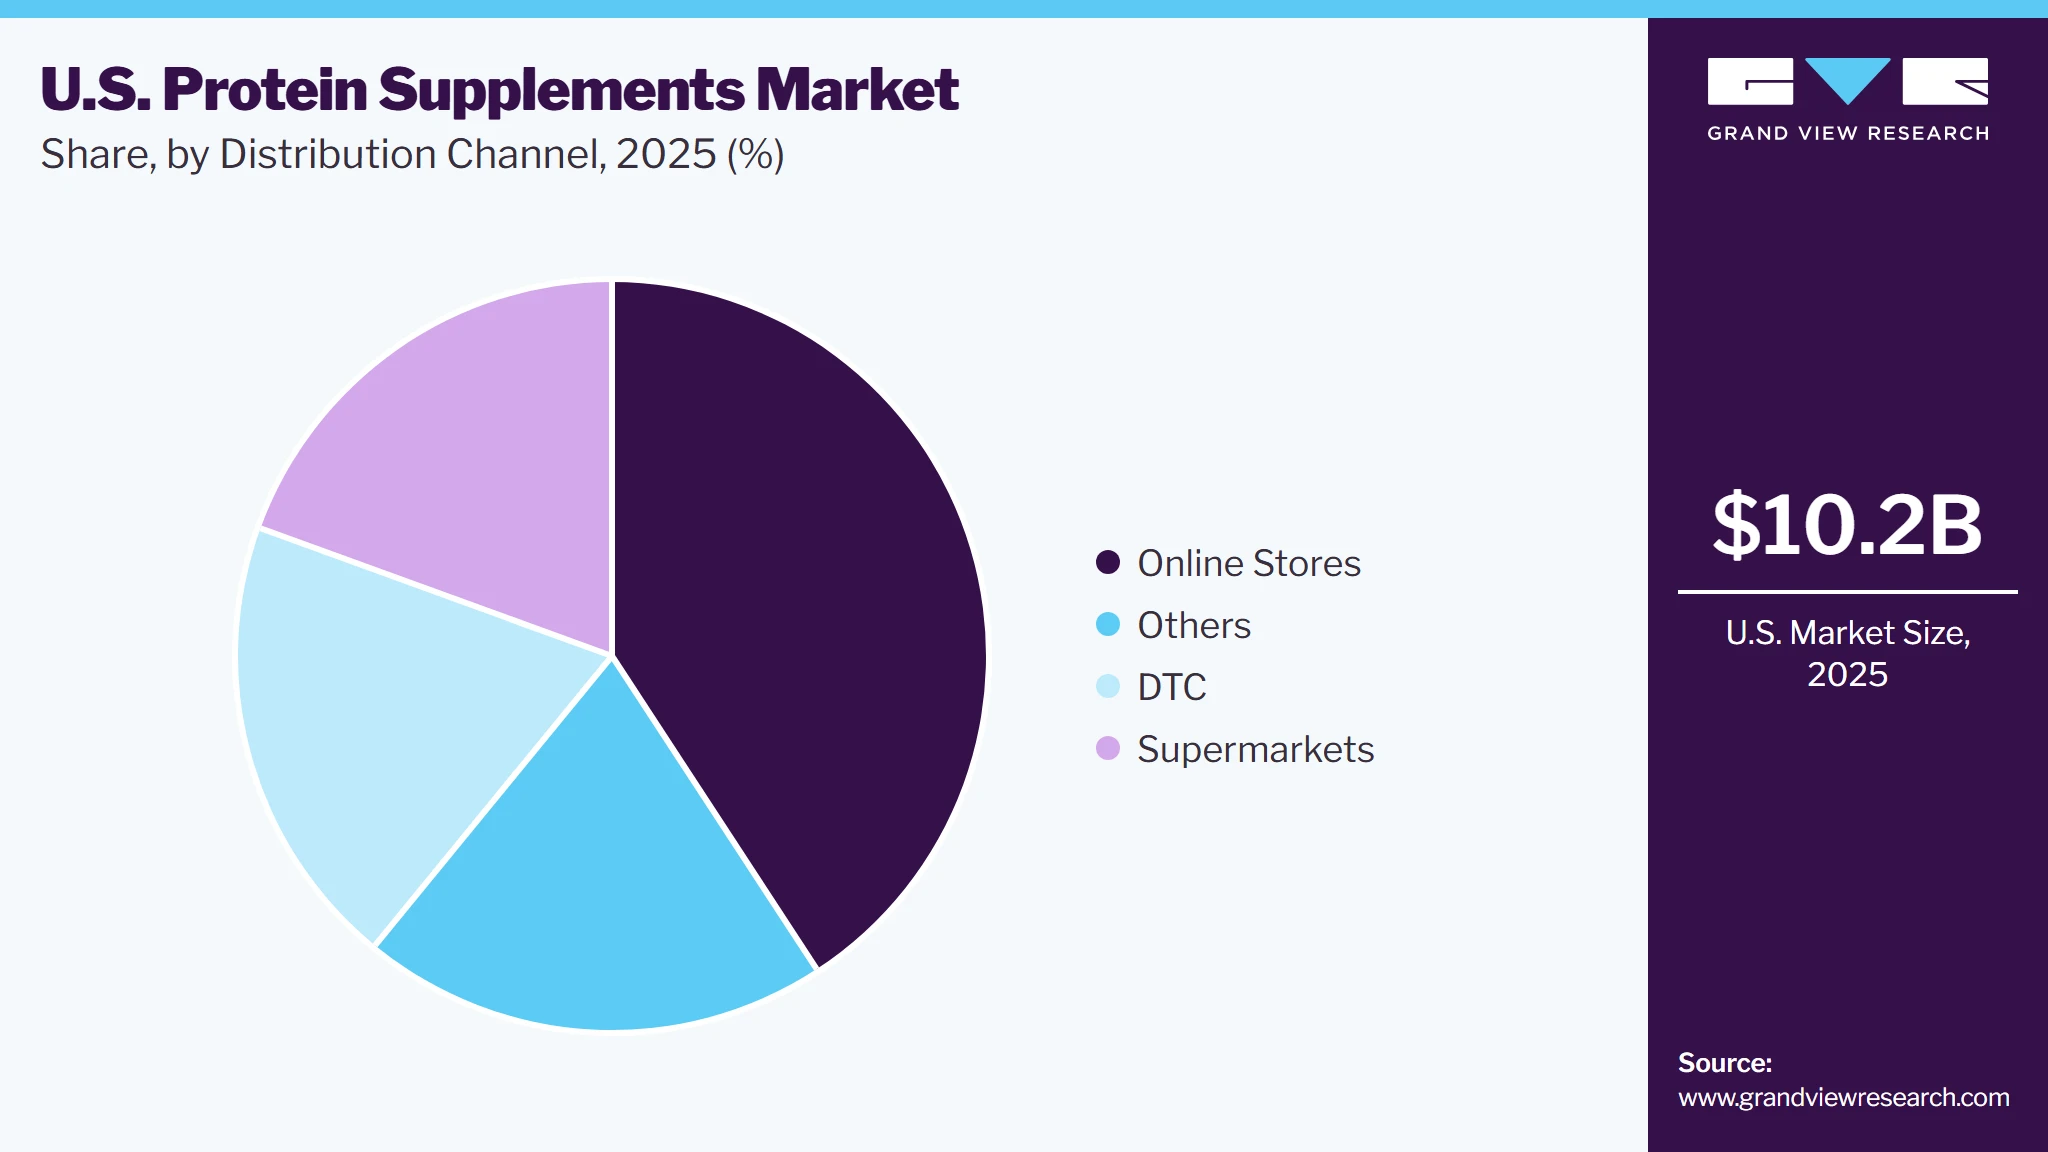
Sales of U.S. protein supplements through online stores held the largest revenue share of 40.8% in 2025. Consumers increasingly prioritize convenience, personalization, and seamless purchase experiences, factors that online platforms are uniquely positioned to deliver through extensive product assortments, subscription options, and targeted recommendations. The proliferation of fitness influencers and educational content across social media has also amplified awareness of protein supplementation benefits, driving demand among younger and health-oriented demographics. Additionally, improvements in e-commerce logistics, such as faster delivery and easy returns, have reduced barriers to trial and repeat purchases, making online channels a preferred avenue for both novice and experienced supplement users.
 To learn more about this report, Download Free Sample Report
The sale of protein supplements through supermarkets is projected to grow significantly at the fastest CAGR of 10.8% from 2026 to 2033. Supermarkets and hypermarkets conduct detailed consumer sentiment analyses to understand customer preferences for products and brands. This allows them to offer products most likely to sell well and charge premium prices if customers are willing to pay.
Supermarkets are easily accessible and provide a convenient shopping experience for customers. They offer a variety of protein supplement options under one roof, making it easier for customers to compare and choose the products that best meet their needs. Customers tend to trust established brands, and supermarkets and hypermarkets offer a wide selection of reputable brands in the protein supplements market. This builds customer confidence in the products being sold and can lead to repeat purchases.
Key U.S. Protein Supplements Company Insights
The U.S. protein supplements industry remains highly competitive, with leading manufacturers expanding their distribution networks across both online and offline retail channels to enhance consumer accessibility. Companies are increasingly investing in product innovation, including flavor varieties, taste, texture, sugar-free options, and sustainable packaging, to meet the evolving demands of consumers.
 To learn more about this report, Download Free Sample Report
Key U.S. Protein Supplements Companies
-
Glanbia Plc
-
MusclePharm
-
Abbott
-
CytoSport Inc.
-
QuestNutrition LLC
-
BPI Sports
-
The Bountiful Company
-
AMCO Proteins
-
Now Foods
-
Transparent Labs
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Glanbia Plc, Abbott, The Bountiful Company, NOW Foods)
- Broaden protein and sports-nutrition portfolios, introduce new formulations and convenient formats, invest in product quality and formulation capabilities, and strengthen retail, specialty-store, and online distribution.
- Established brand recognition, diversified nutrition portfolios, broad distribution networks, extensive formulation capabilities, and access to large consumer bases.
- Large organizational structures, higher operating complexity, broad product portfolios, and potentially slower adaptation to niche consumer preferences.
Emerging / Specialized Players (MusclePharm, CytoSport Inc., Quest Nutrition LLC, BPI Sports, AMCO Proteins, Transparent Labs)
- Focus on performance-oriented and targeted protein products, develop differentiated formulations and flavors, introduce convenient formats, strengthen digital and specialty retail channels, and target specific fitness and wellness needs.
- Focused product positioning, specialized sports-nutrition expertise, targeted consumer engagement, product innovation, and flexible marketing approaches.
- Narrower product portfolios, comparatively limited distribution reach, lower brand recognition in some consumer groups, and greater dependence on specific product categories or consumer segments.
Recent Developments
-
In September 2025, Nutriex, a not‑for‑profit supplement company focused on preventive health, launched Proteins+, a comprehensive protein formula co‑developed with world‑renowned rock climber Chris Sharma. The product combines grass‑fed whey, grass‑fed collagen, creatine, beet extract, multiple fiber sources, and digestive enzymes to support muscle, joint, cognitive, and cardiovascular health, particularly for athletes and adults over 50 who struggle to meet protein needs. Offered in chocolate and vanilla with no added sugar, Proteins+ is positioned as an all‑in‑one, evidence‑based recovery and longevity supplement and is manufactured in FDA‑registered facilities under rigorous quality standards.
-
In October 2025, Power Play Fuel, a U.S.-based sports nutrition brand, was named the Official Supplements and Official Protein Partner of USA Weightlifting, supplying sport-certified, third‑party tested products that are free from sugar and artificial additives to support Team USA athletes. The partnership emphasizes shared values of quality, purity, safety, and integrity, includes a member discount code (USAW25) and free shipping offers, and aligns the brand with elite and everyday lifters who want clean, tested performance nutrition.
-
In July 2025, Myprotein expanded its U.S. retail presence through a new launch at Walmart stores nationwide. The rollout included Clear Whey, Protein Wafers, and creatine products, marking the brand’s first direct placement in Walmart’s physical stores after previously selling through Walmart.com. The development strengthens Myprotein’s offline distribution and increases consumer access to convenient sports-nutrition products.
U.S. Protein Supplements Market Report Scope
Report Attribute
Details
Market size in 2025
USD 10.2 billion
Estimated market size in 2026
USD 10.8 billion
Projected market size by 2033
USD 20.4 billion
Growth rate
CAGR of 9.4% from 2026 to 2033
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2025 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Source, product, distribution channel, and application
Country scope
U.S.
Key companies profiled
Glanbia Plc; MusclePharm; Abbott; CytoSport Inc.; QuestNutrition LLC; BPI Sports; The Bountiful Company; AMCO Proteins; Now Foods; Transparent Labs
Customization scope
Free report customization (equivalent to up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Protein Supplements Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest trends and opportunities in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the U.S. protein supplements market report based on source, product, application, and distribution channel:
-
Source Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Animal-based
-
Whey
-
Casein
-
Egg
-
Fish
-
Others
-
-
Plant-based
-
Soy
-
Spirulina
-
Pumpkin Seed
-
Wheat
-
Hemp
-
Rice
-
Pea
-
Others
-
-
-
Product Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Protein Powder
-
Protein Bars
-
RTD
-
Others
-
-
Application Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Sports Nutrition
-
Functional Foods
-
-
Distribution Channel Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Supermarkets
-
Online Stores
-
DTC
-
Others
-
Research Methodology
The U.S. protein supplements market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. protein supplements segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Source
Revenue capture definition
Animal-based
This segment includes the sales of protein supplements derived from animal-based sources, including milk, whey, casein, eggs, and other animal-derived protein ingredients.
Plant-based
This segment includes the sales of protein supplements derived from plant sources, including soy, pea, rice, hemp, and other plant-based protein ingredients.
Segment - Product
Revenue capture definition
Protein Powder
This segment includes the sales of powdered protein supplements made from sources such as whey, casein, soy, pea, rice, and other proteins, typically mixed with water, milk, or other beverages before consumption.
Protein Bars
This segment includes the sales of protein-rich snack bars formulated with protein sources such as whey, milk, soy, pea, or other ingredients, commonly consumed as convenient snacks or for post-workout nutrition.
RTD
This segment includes the sales of ready-to-drink protein beverages that are pre-mixed and packaged for immediate consumption, including protein shakes, milk-based drinks, and clear protein beverages.
Others
This segment includes the sales of protein supplements offered in other formats, such as capsules, tablets, protein cookies, gels, and other specialized protein products.
Estimation Model
Layer Name
Key Question
Description
Potential Consumer Base
Who could potentially use protein supplements?
Identify the relevant U.S. population with potential demand for protein supplements based on age, lifestyle, physical activity, nutritional goals, and interest in maintaining or increasing daily protein intake. The assessment excludes consumers outside the defined market scope.
Protein Need & Purchase Intent Layer
Who has a need or interest in protein supplementation?
Narrow the potential consumer pool by considering consumers seeking additional protein for muscle maintenance, fitness, weight management, healthy aging, nutritional support, or convenience.
Consumer Conversion Layer
Who converts interest into actual users?
Apply consideration, trial, purchase, and repeat-use rates to determine the share of interested consumers who purchase and use protein supplements. The assessment considers purchasing frequency, preferred product formats, price sensitivity, product accessibility, and usage patterns.
Revenue Realization Layer
How much revenue is generated?
Estimate revenue by combining the converted consumer base with purchase frequency, units consumed, average selling price, and product mix. The calculation incorporates differences in product formulation, protein source, dosage form, pricing, and purchasing channels to determine the overall revenue opportunity.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
U.S. Protein Supplements Market Product Structure Assessment
Analyzed the market based on different protein sources and product characteristics, considering variations in formulation, nutritional composition, and product applications.
Provides a clear understanding of the product landscape and helps identify relevant formulation and product development opportunities.
U.S. Protein Supplements Market Competitive Landscape Assessment
Evaluated key market participants based on market positioning, product portfolios, formulation approaches, distribution presence, innovation activities, and strategic direction, without disclosing individual company names.
Enables comparison of established and emerging participants and highlights differences in positioning, innovation, product offerings, and competitive capabilities.
U.S. Protein Suppléments Market Consumer & Distribution Assessment
Evaluated consumer groups based on purchasing behavior, usage patterns, product preferences, accessibility, and purchasing routes across physical and digital retail channels.
Helps identify consumer-oriented opportunities, understand purchasing behavior, and support route-to-market and channel planning.
Frequently Asked Questions About This Report
The U.S. protein supplements market size was valued at USD 10.2 billion in 2025 and is expected to reach USD 10.8 billion in 2026.
Key players include Glanbia Plc; MusclePharm; Abbott; CytoSport Inc.; QuestNutrition LLC; BPI Sports; The Bountiful Company; AMCO Proteins; Now Foods; and Transparent Labs
The protein powder supplements led with a 48.7% revenue share in 2025, while RTD supplements are the fastest-growing segment.
Functional Foods held the largest revenue share in 2025, while sports nutrition is the fastest-growing segment.
Online stores held the largest share in 2025, while supermarkets is the fastest-growing segment.
The U.S. protein supplements market is expected to grow at a CAGR of 9.4% from 2026 to 2033, reaching USD 20.4 billion by 2033.
The animal-based protein supplements led with a 58.6% revenue share in 2025, while plant-based protein supplements are the fastest-growing segment.
Key factors include growing consumer focus on protein intake, rising fitness and muscle-health awareness, increasing interest in weight management and healthy aging, demand for convenient nutrition, and expanding adoption of protein products beyond traditional sports and bodybuilding users.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


