
- Home
- »
- Plastics, Polymers & Resins
- »
-
Barrier Films For Pharmaceutical Packaging Market Report 2026-2033GVR Report cover

Barrier Films For Pharmaceutical Packaging Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Polyethylene (PE), Polyethylene Terephthalate (PET)), By Product Type (Single-layer Films, Multilayer Films, Coated Films), By Application, By Region, And Segment Forecasts
Market Size, 2025
$9.2BMarket Estimate, 2026
$9.7BMarket Forecast, 2033
$12.7BCAGR, 2026–2033
4.0%Barrier Films For Pharmaceutical Packaging Market Summary
The global barrier films for pharmaceutical packaging market size was valued at USD 9.2 billion in 2025 and is projected to grow from USD 9.7 billion in 2026 to USD 12.7 billion by 2033, at a CAGR of 4.0% from 2026 to 2033. Asia Pacific dominated the market with the largest revenue share of 40.1% in 2025. The barrier films for the pharmaceutical packaging market is driven by increasing demand for extended shelf life and protection against moisture, oxygen, and light.
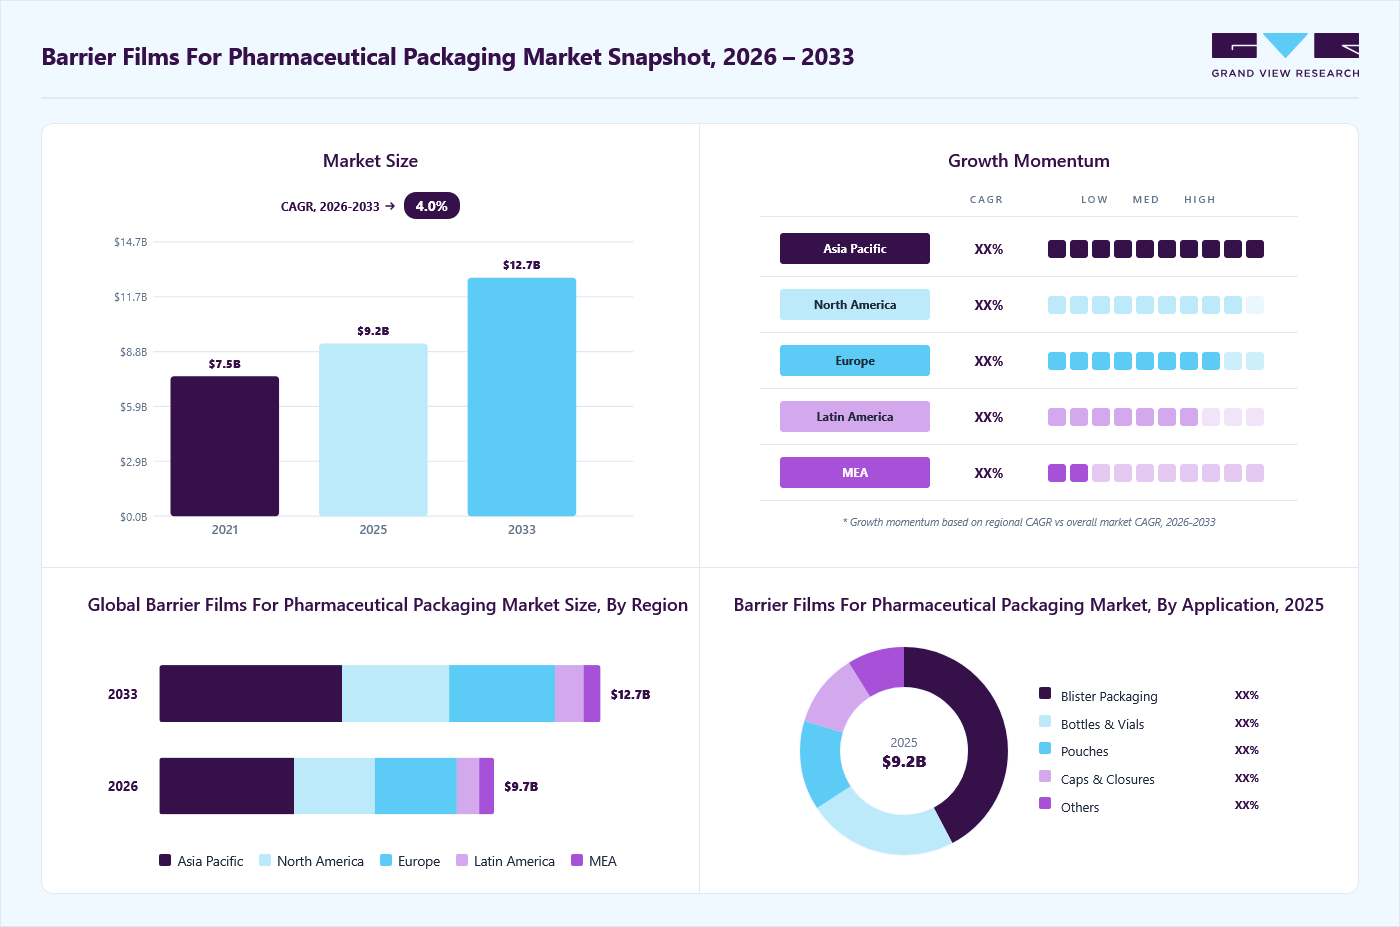 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: Polyethylene (PE) segment led the market with the largest revenue share of 32.9% in 2025.
- By product type: Multilayer films segment led the market with the largest revenue share of 46.5% in 2025.
- By application: Blister packaging segment led the market with the largest revenue share of 42.3% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (40.1% revenue share, 2025)
- By country: The China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 9.2 Billion
- Estimated market size in 2026: USD 9.7 Billion
- Projected market size by 2033: USD 12.7 Billion
- CAGR (2026-2033): 4.0%
Prism AI by Grand View Research Free to tryAsk a question about the barrier films for pharmaceutical packaging marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Additionally, the rising prevalence of chronic diseases and growing regulatory emphasis on product safety boost market growth. The barrier films for pharmaceutical packaging market are primarily driven by increased demand for drug safety and extended shelf life. For example, drugs such as effervescent tablets, biologics, and antibiotics are highly sensitive to moisture and require packaging materials with superior barrier properties to ensure their potency and efficacy over time. The growing focus on patient safety and compliance with stringent quality standards has pushed pharmaceutical companies to adopt advanced packaging solutions like high-barrier films.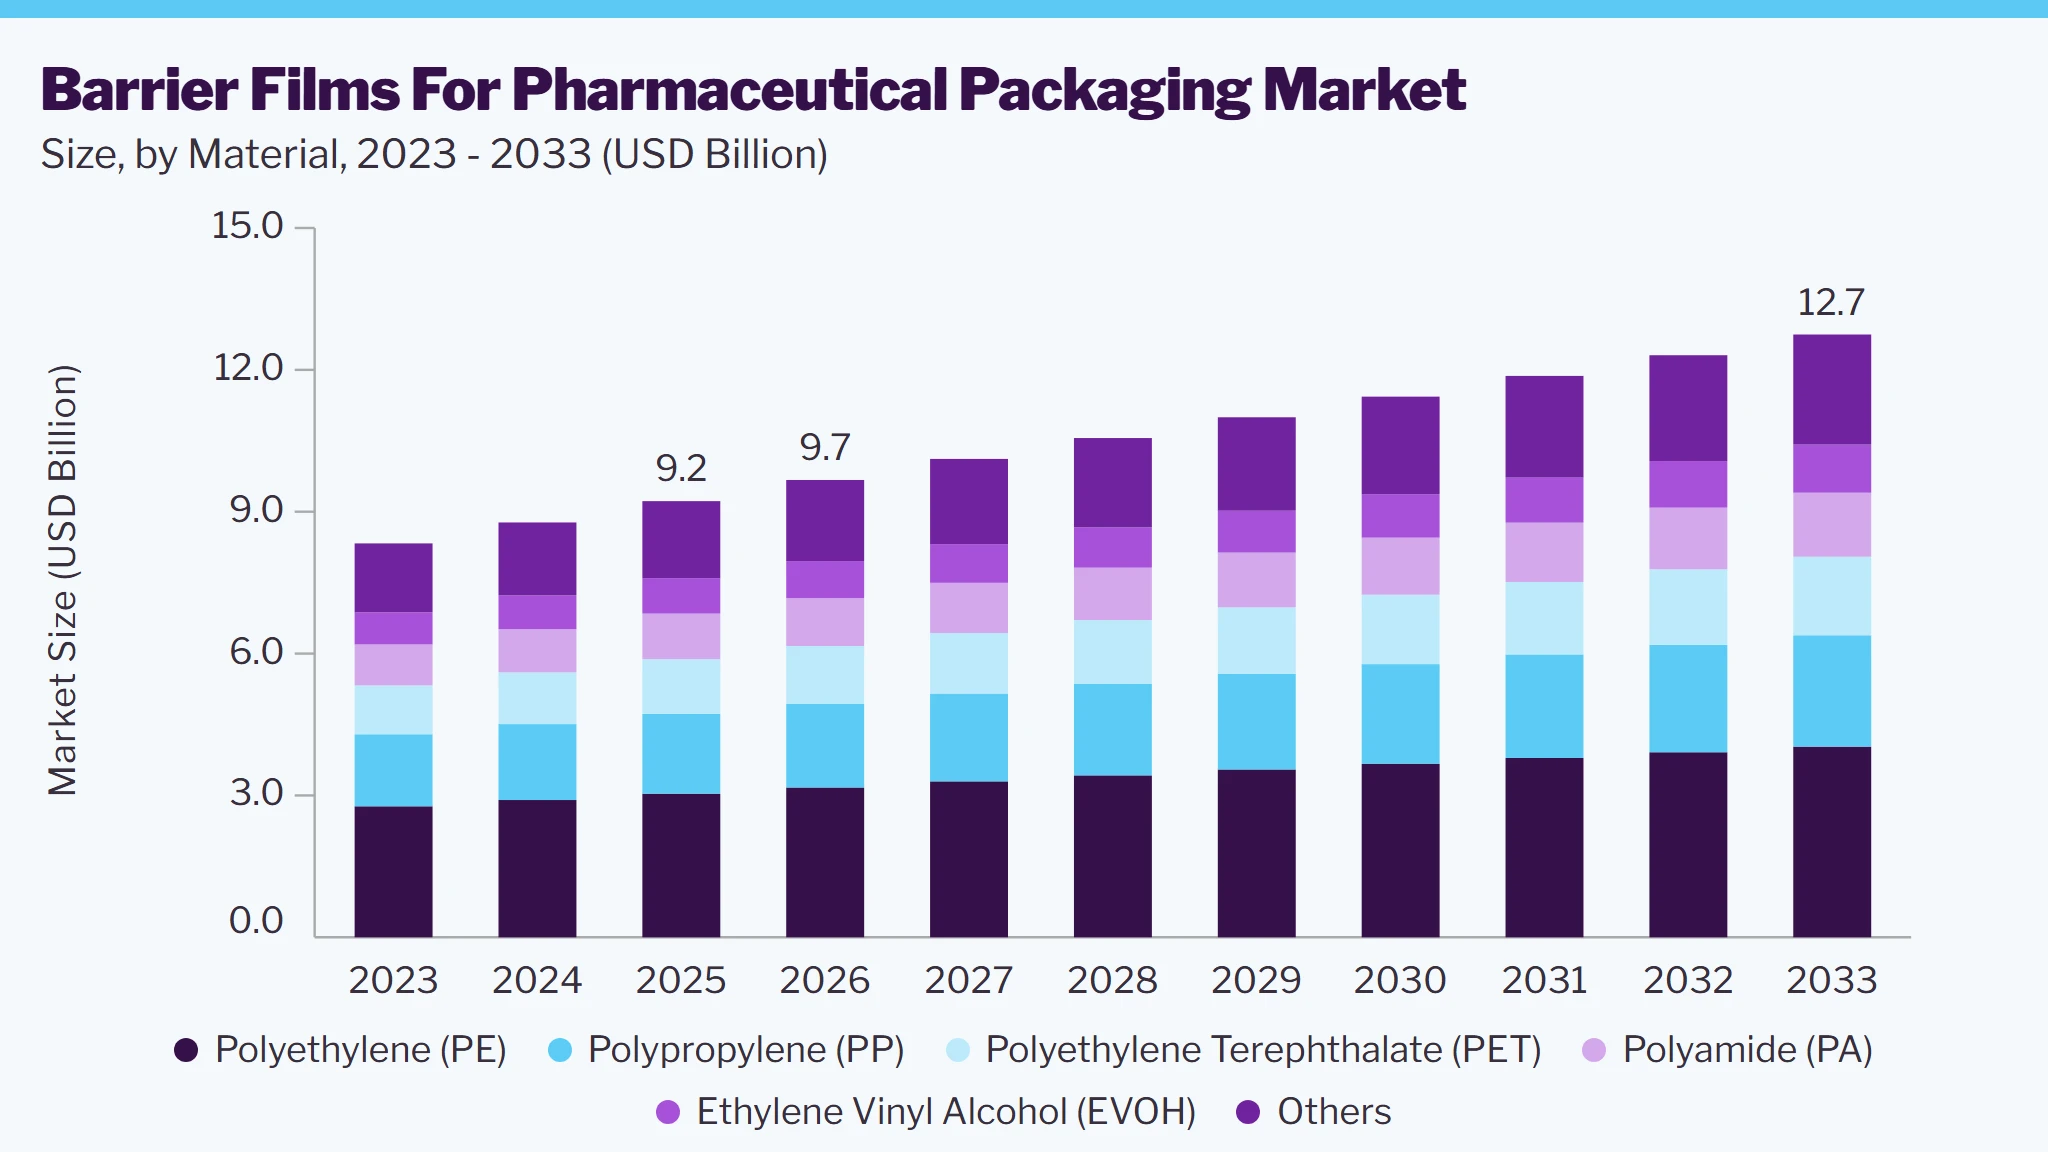 To learn more about this report, Download Free Sample Report
The growth in biologics and specialty pharmaceuticals is also contributing to market growth. It requires enhanced protection due to their complex compositions. These products are more sensitive to environmental conditions compared to traditional small-molecule drugs. As a result, pharmaceutical companies are increasingly using high-performance barrier films such as polyvinylidene chloride (PVDC), cyclic olefin polymers (COP), and aluminum foil laminates. For example, barrier films used in blister packaging for biologics help maintain drug stability and reduce the risk of contamination, ensuring that the medication remains safe and effective until it reaches the patient.
 To learn more about this report, Download Free Sample Report
Regulatory compliance and sustainability trends are also shaping the market. Regulatory bodies such as the U.S. FDA and EMA mandate strict guidelines for pharmaceutical packaging, including barrier performance, material safety, and compatibility with the drug product. At the same time, there is a growing push toward eco-friendly and recyclable materials. This has led to innovation in developing multi-layer barrier films that balance high protection with recyclability.
Moreover, the global rise in pharmaceutical manufacturing and contract packaging services is amplifying demand for barrier films. The COVID-19 pandemic accelerated investments in pharmaceutical production and cold chain logistics, especially for vaccines and temperature-sensitive drugs. This has led to increased usage of barrier films in secondary and tertiary packaging formats such as pouches, sachets, and overwraps. Moreover, with the outsourcing of packaging operations to contract manufacturing organizations (CMOs), there is a greater emphasis on standardized, high-performance packaging materials that can be used across diverse drug portfolios and regional regulatory requirements.
Market Dynamics
Barrier films for pharmaceutical packaging are shaped by the need to protect moisture-sensitive, oxygen-sensitive, and light-sensitive drug formats across blister packs, pouches, bottles, and unit-dose systems. Demand is concentrated in regulated pharmaceutical manufacturing hubs where pack integrity, shelf-life extension, and line efficiency carry high commercial value. The market is also defined by a relatively rigid supplier structure, with converters, compounders, and pharmaceutical packagers operating through qualification-led purchasing and long-term supply relationships. Growth is increasingly linked to high-barrier multilayer platforms, recyclable structures, and materials that can balance protection with manufacturing throughput.
The strongest driver in the barrier films market is the continued shift toward packaging formats that can preserve drug stability without compromising manufacturing speed. Oral solids, combination therapies, and sensitive formulations increasingly require films with low oxygen transmission, low moisture vapor transmission, and reliable seal performance. This is raising the value of advanced structures that reduce product degradation, extend shelf life, and support compliance with stringent pharmaceutical packaging standards. As drug makers focus on pack-level protection rather than basic containment, barrier films are being specified earlier in the product development cycle.
In addition, pharmaceutical packaging teams are placing greater emphasis on line compatibility and reduced waste, which favors film systems that deliver consistent thermoforming, printability, and sealing behavior. High-volume blister operations, especially for generics and over-the-counter medicines, continue to anchor demand because they require stable film performance at scale. Specialty drug producers are also favoring differentiated barrier formats that support product positioning, serialization, and tamper resistance. This is turning barrier films from a commodity input into a performance-critical packaging layer.
A major restraint in the barrier films market is the commercial complexity of multilayer and coated structures, which are often difficult to recycle and expensive to qualify for pharmaceutical use. Many high-barrier formats depend on mixed-material constructions that deliver strong protection but create sustainability challenges and limit compatibility with emerging mono-material packaging strategies. At the same time, pharmaceutical customers require long validation cycles, detailed regulatory documentation, and stable supply assurance before changing film specifications. These requirements increase switching costs and slow adoption of new materials, particularly when a film reformulation could affect sealing, machinability, or drug stability.
A clear opportunity lies in the development of recyclable barrier films that retain strong protection performance while reducing material complexity. Pharmaceutical brands are under growing pressure to improve packaging sustainability without compromising shelf life or regulatory compliance. Films that combine barrier coatings, downgauged structures, and mono-material design logic can create value in both regulated and consumer-facing drug categories. This opens room for suppliers that can deliver technical performance, documentation support, and scale-ready supply in one platform.
Analyst Perspective
The barrier films market is expected to move from a largely performance-led packaging category toward a more balanced structure in which protection, sustainability, and supply reliability must coexist. Over the next 5 to 10 years, demand will remain anchored in blister packaging, pouches, and other primary pharmaceutical formats, but value creation will increasingly depend on recyclable mono-material platforms, advanced coatings, and structures that simplify qualification without weakening barrier performance. Regulatory scrutiny on packaging consistency, product safety, and environmental performance will continue to influence material selection, while supply chain resilience and resin volatility will remain important margin variables. Market leaders are likely to differentiate through application-specific technical service, regulatory documentation, manufacturing integration, and global customer support. Firms that can combine high-barrier performance with scalability, sustainability, and packaging-line compatibility will be better positioned as customers move away from conventional film choices toward more specialized and compliant solutions.
Material Insights
Based on the material, the polyethylene (PE) segment led the market with the largest revenue share of 32.9% in 2025. PE is widely used in pharmaceutical packaging due to its excellent moisture barrier properties, flexibility, and low cost. It is typically used as a sealant layer in multi-layer barrier films. PE, especially low-density polyethylene (LDPE), is valued for its transparency, softness, and heat-sealing capabilities, which make it suitable for packaging tablets, capsules, and medical devices.
Polyethylene terephthalate (PET) is expected to grow at the fastest CAGR of 5.1% during the forecast period. PET is used in pharmaceutical packaging for its excellent strength, clarity, and barrier to gases and moisture. It is often used as a laminate layer over aluminum foils or other barrier materials in blister packs and sachets. The increasing demand for transparent, tamper-evident, and aesthetically appealing pharmaceutical packaging is fueling the use of PET.
Product Type Insights
Based on product type, the multilayer films segment led the market with the largest revenue share of 46.5% in 2025. Multilayer films consist of multiple polymer layers bonded together, each contributing a specific property such as moisture resistance, oxygen barrier, or mechanical strength. These films are widely used in pharmaceutical packaging to protect sensitive drugs from environmental degradation. Multilayer films are driven by the rising demand for high-barrier packaging in the pharmaceutical industry, especially for biologics and moisture-sensitive drugs.
Laminated films segment is primarily driven by the increasing demand for flexible, durable, and aesthetically appealing packaging solutions in the pharmaceutical industry. Laminated films are formed by bonding two or more film layers using adhesives or heat, offering combined benefits of the individual layers. These films are known for their excellent mechanical strength, printability, and high barrier capabilities, and are commonly used for sachets, pouches, and blister packs.
Application Insights
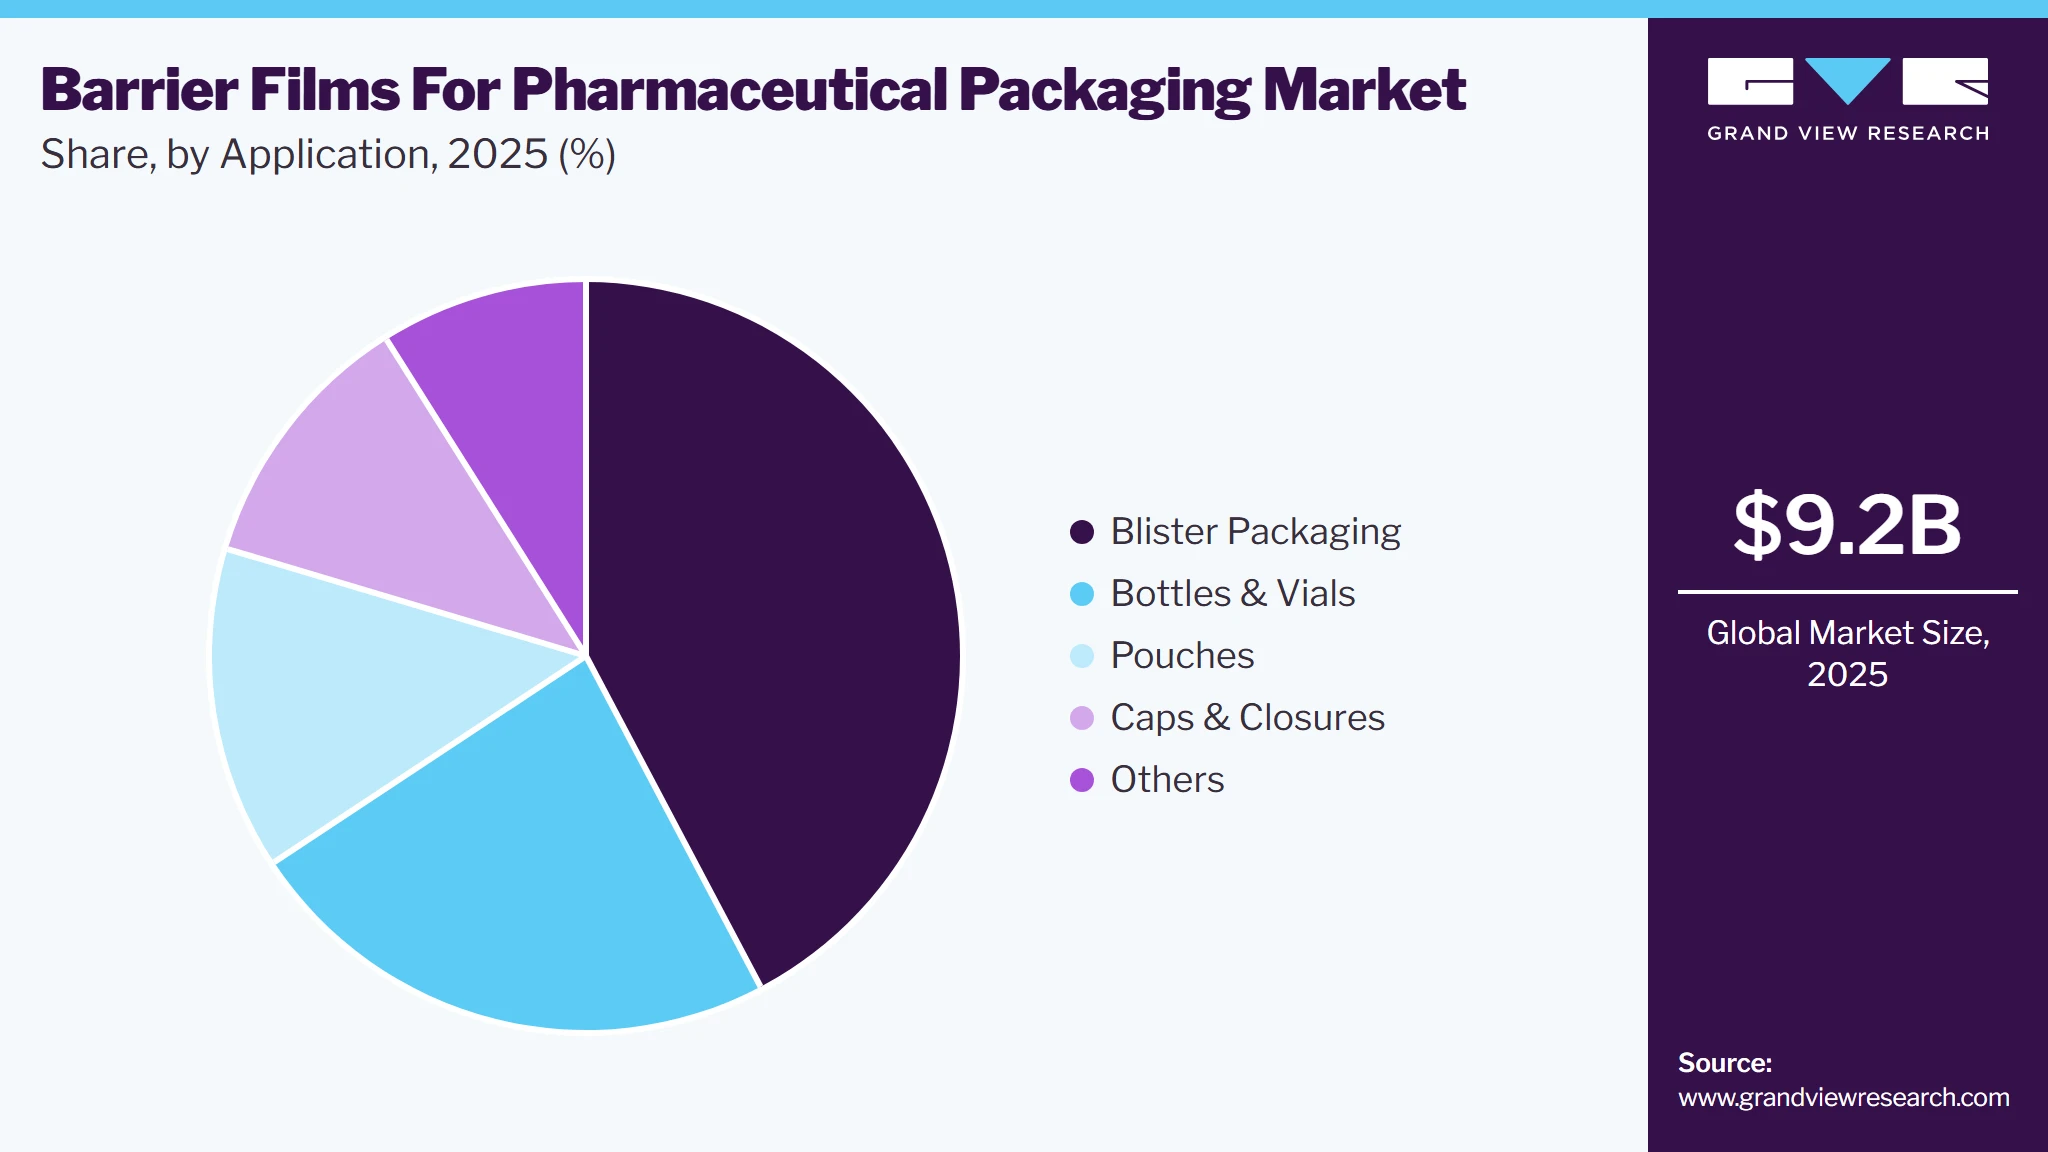
Based on application, the blister packaging segment led the market with the largest revenue share of 42.3% in 2025. The demand for blister packaging is primarily driven by its ability to offer unit-dose protection, reduce contamination risks, and improve patient compliance. Additionally, the increasing trend toward self-medication and over-the-counter (OTC) drug sales, especially in developing regions, fuels growth. The rising geriatric population and the need for tamper-evident and child-resistant packaging also bolster demand for barrier films in this segment.
 To learn more about this report, Download Free Sample Report
Pouches made from multi-layer barrier films are used for packaging powders, granules, or transdermal patches. They are flexible, lightweight, and offer excellent protection against oxygen, moisture, and light, making them suitable for pharmaceutical and medical device applications. The increasing demand for convenient, portable, and single-use packaging drives the adoption of barrier films in pouch applications.
Bottles and vials serve as primary containers for liquid, powder, and injectable drugs. Barrier films are used either as linings or secondary seals to enhance the container’s resistance to moisture, gas, and microbial contamination. These films ensure the stability of sensitive pharmaceutical formulations during storage and transportation. Growth in this segment is driven by the expanding biologics and injectable drugs market, which requires high-barrier packaging to maintain drug efficacy.
Region Insights
North America’s growth in the barrier films for pharmaceutical packaging market is due to its robust pharmaceutical industry infrastructure and stringent regulatory framework. The FDA's strict packaging requirements for drug stability, shelf life, and protection against moisture, oxygen, and contaminants have driven pharmaceutical companies to adopt high-performance barrier films. Major companies such as Johnson & Johnson, Pfizer, and Merck have established extensive manufacturing facilities across the region, creating consistent demand for advanced packaging solutions.
U.S. Barrier Films for Pharmaceutical Packaging Market Trends
The barrier films for pharmaceutical packaging market in the U.S. are primarily driven by the rapid growth of biologics, injectables, and personalized medicine in the country. In addition, the U.S. pharmaceutical supply chain's growing complexity, driven by cold chain logistics, online pharmacies, and decentralized clinical trials, has escalated the demand for high-performance packaging. Moreover, government support for domestic pharmaceutical manufacturing, such as initiatives under the Biomedical Advanced Research and Development Authority (BARDA) and the FDA’s Drug Supply Chain Security Act (DSCSA), continues to stimulate investment in packaging innovations.
Europe Barrier Films for Pharmaceutical Packaging Market Trends
Europe barrier films for pharmaceuticals packaging market has one of the largest and most well-established pharmaceutical markets globally, with countries such as Germany, Switzerland, and France being home to some of the world’s largest pharmaceutical companies. These companies require advanced packaging solutions to protect their products during transportation and storage, thus driving the market growth in the country.
Barrier films for pharmaceutical packaging market in Germany are primarily driven by its combination of pharmaceutical manufacturing expertise, stringent regulatory framework, robust innovation ecosystem, and export-oriented economy. The country consists of major global pharmaceutical companies, including Bayer, Boehringer Ingelheim, and Merck KGaA, all of which demand high-quality, protective packaging materials to ensure drug safety and compliance with regulatory standards.
Asia Pacific Barrier Films for Pharmaceutical Packaging Market Trends
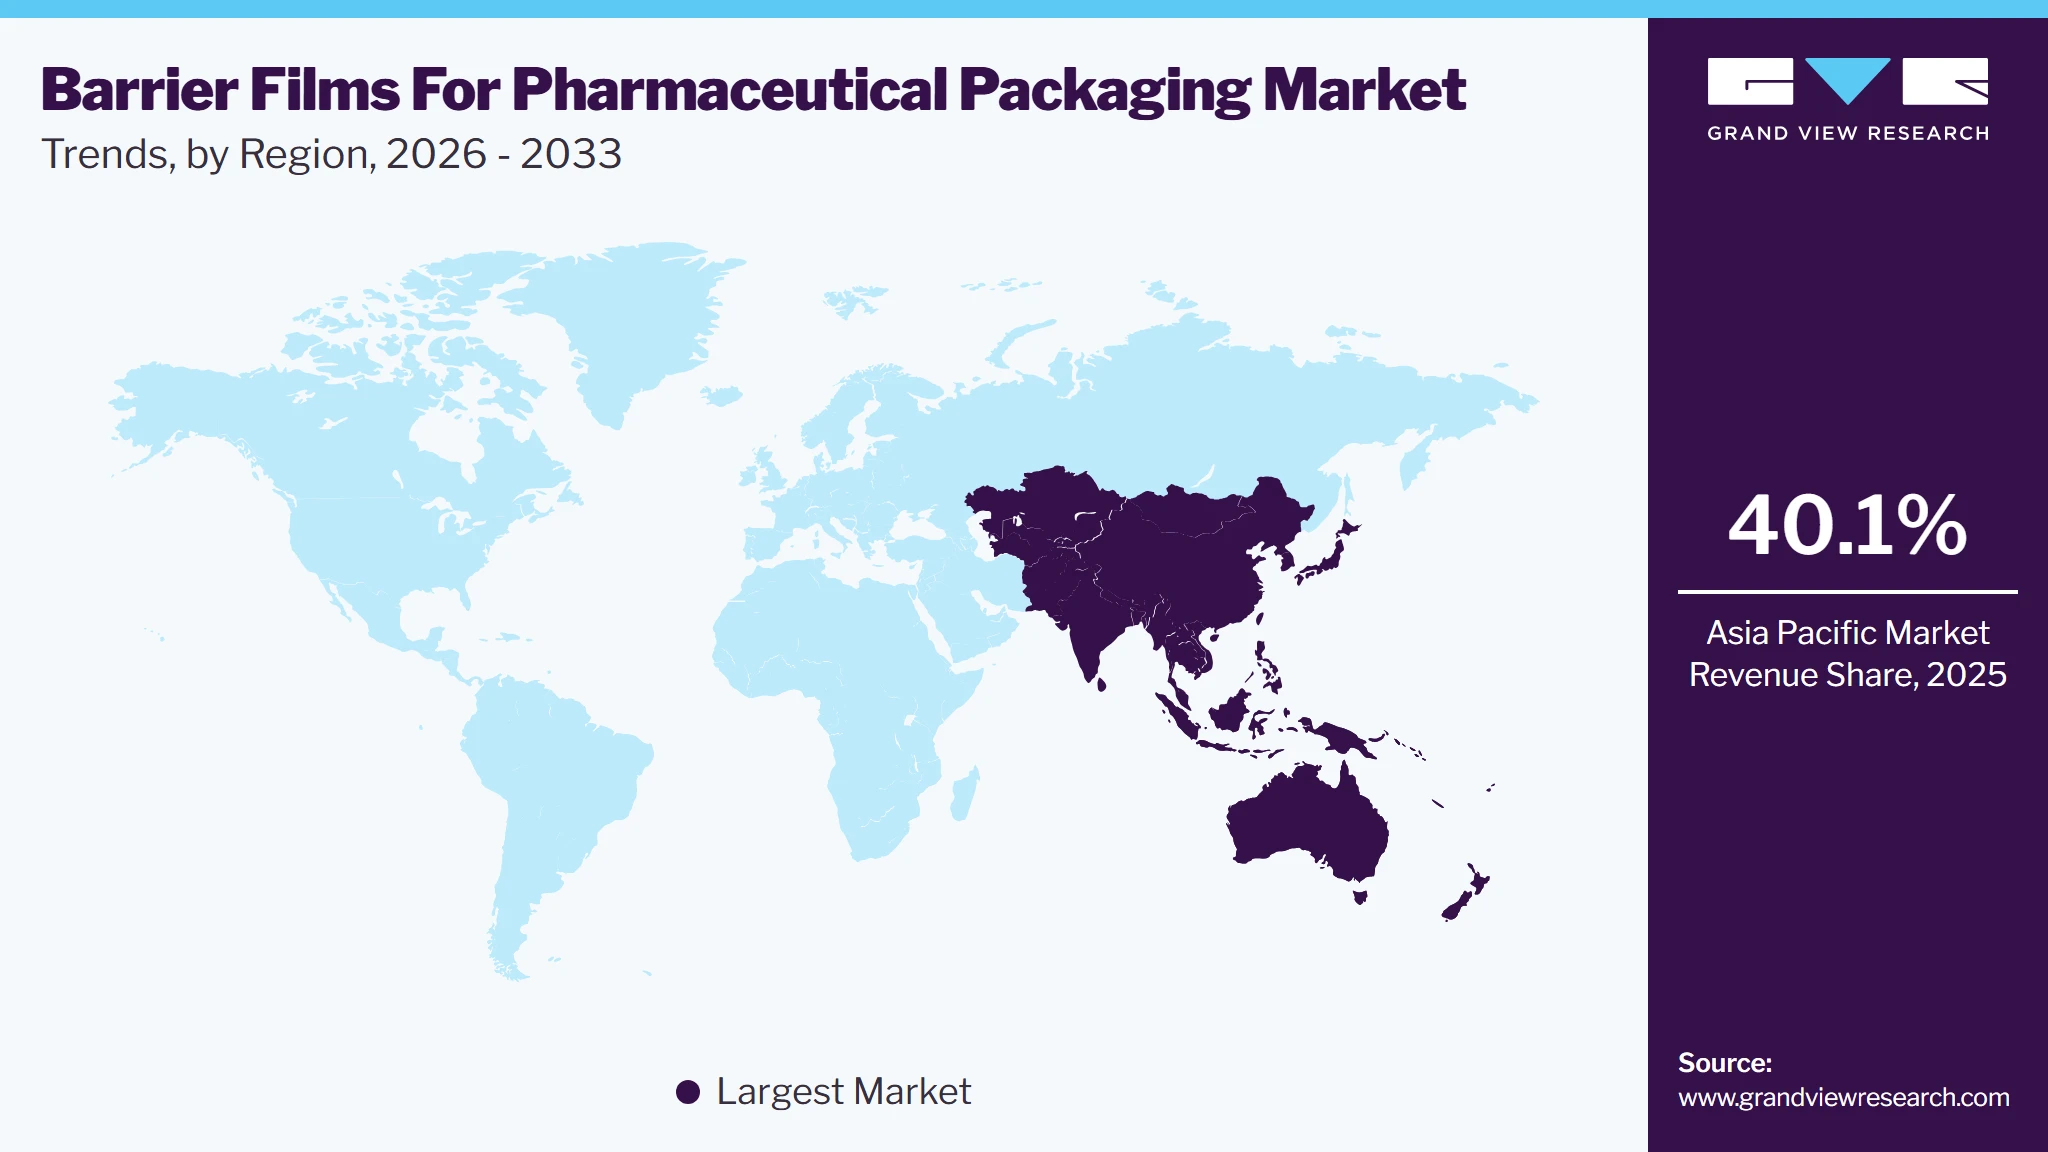
Asia Pacific dominated the barrier films for pharmaceutical packaging market with the largest revenue share of 40.1% in 2025. The region hosts rapidly expanding pharmaceutical manufacturing hubs in countries such as India, China, and Singapore, which collectively produce a significant portion of the world's generic medications and active pharmaceutical ingredients. This manufacturing concentration naturally drives demand for high-quality packaging solutions, including specialized barrier films that protect sensitive medications from moisture, oxygen, and light degradation.
 To learn more about this report, Download Free Sample Report
The barrier films for pharmaceutical packaging market in China held the largest share in the Asia Pacific region in 2025. The barrier films for pharmaceutical packaging market in China are primarily driven by its massive pharmaceutical manufacturing base has expanded dramatically in recent years, with domestic companies scaling up production while multinational corporations establish regional manufacturing hubs to serve Asian markets. The Chinese government's "Healthy China 2030" initiative has prioritized pharmaceutical innovation and quality improvements across the supply chain, directly benefiting packaging materials.
Key Barrier Films For Pharmaceutical Packaging Company Insights
The competitive environment of the barrier films for pharmaceutical packaging industry is characterized by intense rivalry among global and regional players striving to enhance product performance, regulatory compliance, and sustainability. Major companies dominate the market through continuous innovation in multilayer film technology, advanced materials such as PVDC and EVOH, and eco-friendly alternatives. The industry is highly influenced by stringent pharmaceutical packaging regulations, driving companies to invest in R&D and strategic partnerships to meet safety, shelf-life, and barrier property requirements. Additionally, emerging players are gaining traction by focusing on cost-effective solutions and sustainable materials, adding further competition to an already dynamic market.
-
In May 2024, TOPPAN Holdings Inc. and India-based TOPPAN Speciality Films (TSF) plan to launch Indian production of GL-SP, a BOPP-based barrier film designed for sustainable packaging. The film offers barrier performance comparable to vapor-deposited PET, providing excellent protection against oxygen and water vapor, making it ideal for packaging applications in sectors such as food, medical/pharmaceutical, and industrial materials.
-
In October 2023, Solvay launched Diofan Ultra736, a new ultra-high barrier polyvinylidene chloride (PVDC) coating solution designed for pharmaceutical blister films that offers superior water vapor barrier properties while enabling thinner coating structures, which significantly reduces the carbon footprint of the packaging. This aqueous, fluorine-free dispersion meets regulatory requirements for direct pharmaceutical contact and maintains excellent oxygen barrier, chemical resistance, transparency, and thermoformability, allowing for smaller pack sizes with higher pill density.
Key Barrier Films For Pharmaceutical Packaging Companies:
The following key companies have been profiled for this study on the barrier films for pharmaceutical packaging market.
-
Klöckner Pentaplast
-
Sealed Air
-
Cosmo Films
-
UFlex Limited
-
Honeywell International Inc.
-
TOPPAN Inc.
-
ACG
-
West Pharmaceutical Services, Inc.
-
Tekni-Plex, Inc.
-
Neelam Global Pvt. Ltd.
-
Perlen Packaging
-
WEIFU Films
-
Dai Nippon Printing Co., Ltd.
-
ALMA Packaging AG
-
Vishakha Polyfab Pvt Ltd
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Klöckner Pentaplast, Sealed Air, Honeywell International Inc., TOPPAN Inc., ACG, West Pharmaceutical Services, Inc., Tekni-Plex, Inc., Dai Nippon Printing Co., Ltd., Perlen Packaging)
- Focus on high-barrier multilayer and specialty pharmaceutical packaging solutions for regulated drug applications.
- Maintain long-term supply agreements with pharmaceutical manufacturers through validated and compliant packaging platforms.
- Invest in advanced coating technologies, sustainability initiatives, and global manufacturing expansion.
- Strong regulatory compliance capabilities and established qualification history with pharmaceutical customers.
- Broad product portfolios covering blister films, laminates, closures, and high-performance barrier structures.
- Extensive global production footprint and integrated supply chain capabilities.
- Higher operating and compliance costs due to stringent pharmaceutical standards.
- Longer product development and commercialization timelines for new film structures.
- Greater exposure to raw material price fluctuations across multiple manufacturing locations.
Emerging Players (Cosmo Films, UFlex Limited, Neelam Global Pvt. Ltd., WEIFU Films, ALMA Packaging AG, Vishakha Polyfab Pvt Ltd)
- Expand presence through cost-competitive barrier film offerings and customized packaging solutions.
- Target regional pharmaceutical packaging converters and mid-sized drug manufacturers.
- Focus on capacity expansion and specialty film development to strengthen market penetration.
- Greater manufacturing flexibility and faster response to customer-specific requirements.
- Competitive pricing supported by regional production advantages.
- Ability to develop niche and application-specific barrier film solutions.
- Limited global reach compared to established multinational suppliers.
- Lower brand recognition in highly regulated pharmaceutical packaging markets.
- Dependence on selected regional markets and narrower product portfolios.
Barrier Films For Pharmaceutical Packaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 9.2 billion
Estimated market size in 2026
USD 9.7 billion
Projected market size by 2033
USD 12.7 billion
Growth rate
CAGR of 4.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, product type, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Russia; Denmark; Sweden; Norway; China; India; Japan; South Korea; Indonesia; Vietnam; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Klöckner Pentaplast; Sealed Air; Cosmo Films; UFlex Limited; Honeywell International Inc.; TOPPAN Inc.; ACG; West Pharmaceutical Services, Inc.; Tekni-Plex, Inc.; Neelam Global Pvt. Ltd.; Perlen Packaging; WEIFU Films; Dai Nippon Printing Co., Ltd.; ALMA Packaging AG; Vishakha Polyfab Pvt Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Barrier Films For Pharmaceuticals Packaging Market Report Segmentation
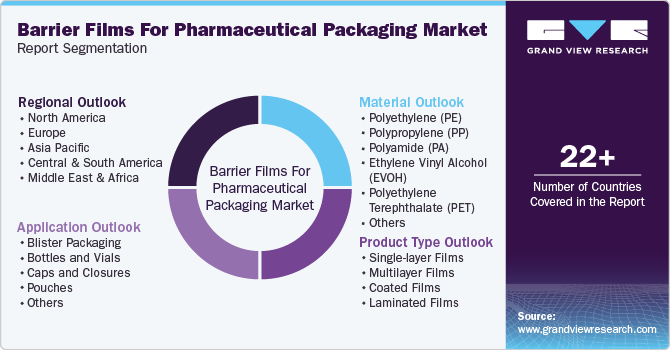
This report forecasts revenue growth at a global, regional, and country level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global barrier films for pharmaceutical packaging market report based on material, product type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Material Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Polyethylene (PE)
-
Polypropylene (PP)
-
Polyamide (PA)
-
Ethylene Vinyl Alcohol (EVOH)
-
Polyethylene Terephthalate (PET)
-
Others
-
-
Product Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Single-layer Films
-
Multilayer Films
-
Coated Films
-
Laminated Films
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Blister Packaging
-
Bottles and Vials
-
Caps and Closures
-
Pouches
-
Others
-
-
Region Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
Russia
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
Indonesia
-
Vietnam
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
Segment Definition
Segment - Material
Revenue capture definition
Polyethylene (PE)
Revenue is captured through sealant webs, moisture-resistant inner layers, and flexible packaging structures where cost efficiency and seal integrity are the primary purchase criteria.
Polypropylene (PP)
Revenue is generated from thermoformable and printable packaging layers used in blister and pouch systems where heat resistance, clarity, and process stability matter.
Polyamide (PA)
Revenue is earned from puncture-resistant barrier layers in composite films used for demanding pharmaceutical packs that require strength, durability, and product protection.
Ethylene Vinyl Alcohol (EVOH)
Revenue is captured through high-barrier core layers in multilayer films designed for oxygen-sensitive drugs and other formulations with strict stability requirements.
Polyethylene Terephthalate (PET)
Revenue is generated from dimensionally stable base webs and premium outer layers that support print quality, structural rigidity, and packaging aesthetics.
Others
This segment captures revenue from PVDC, aluminum oxide, silicon oxide, specialty adhesives, and other niche barrier chemistries used in advanced pharma packaging.
Segment - Product Type
Revenue capture definition
Single-layer Films
Revenue is captured from economical film formats used in lower-complexity packaging applications where basic protection, sealing, and formability are sufficient.
Multilayer Films
Revenue is generated from high-value constructions that combine multiple polymers or barrier layers to deliver superior moisture, oxygen, and puncture resistance.
Coated Films
Revenue is captured through films with functional barrier coatings that improve protection performance while supporting downgauging and sustainability-oriented packaging designs.
Laminated Films
Revenue is generated from bonded structures that combine distinct material properties, typically used when the pack requires added barrier, strength, or print performance.
Segment - Application
Revenue capture definition
Blister Packaging
Revenue is captured through films supplied to high-volume blister lines for tablets and capsules, where barrier performance, machinability, and sealing consistency are critical.
Bottles and Vials
Revenue is generated from barrier liners, overwraps, and specialty films that help protect liquid and solid pharmaceutical products during storage and transit.
Caps and Closures
Revenue is captured from barrier-related sealing components and film-based liners that support closure integrity, contamination control, and product shelf stability.
Pouches
Revenue is generated from flexible barrier films used in unit-dose, sample, and specialty pharmaceutical pouches requiring lightweight protection and ease of handling.
Others
This segment includes revenue from sachets, overwraps, transdermal formats, and niche pharmaceutical packs that require customized barrier performance.
Estimation Model
Layer Name
Key Question
Description
End-use Layer
Where is film consumed?
This layer anchors the model on pharmaceutical consumption intensity, translating pack volumes from tablets, capsules, injectables, and specialty drugs into baseline film demand.
Format Layer
Which packs drive demand?
This layer allocates revenue by packaging type because barrier requirements, material thickness, and conversion economics vary materially across blisters, pouches, bottles, and closures.
Regional Layer
Where is demand concentrated?
This layer captures procurement concentration in regulated manufacturing regions, where pharmaceutical production density, compliance standards, and supply chain depth shape film purchasing patterns.
Commercial Layer
How is value captured?
This layer validates the estimate through supplier pricing, qualification intensity, and mix shifts across premium barrier structures, ensuring revenue capture reflects real transaction economics.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Additional regional split
Added a deeper regional view across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, with demand concentration and procurement behavior aligned to pharmaceutical manufacturing footprints.
Helps identify high-priority sales regions and channel focus.
Material-level deep dive
Expanded the material outlook to include PE, PP, PA, EVOH, PET, and specialty inputs, with commercial logic tied to barrier performance and film conversion economics.
Improves product positioning and portfolio planning.
End-use application split
Refined the application view across blister packaging, bottles and vials, caps and closures, pouches, and other pharmaceutical formats with revenue capture logic.
Supports sharper customer targeting and segment prioritization.
Frequently Asked Questions About This Report
The global barrier films for pharmaceutical packaging market was valued at USD 9.2 billion in 2025 and is estimated at USD 9.7 billion in 2026.
The global barrier films for pharmaceutical packaging market is expected to grow at a CAGR of 4.0% from 2026 to 2033 to reaching USD 12.7 billion by 2033.
The key players in the barrier films for pharmaceutical packaging market include Klöckner Pentaplast; Sealed Air; Cosmo Films; UFlex Limited; Honeywell International Inc.; TOPPAN Inc.; ACG; West Pharmaceutical Services, Inc.; Tekni-Plex, Inc.; Neelam Global Pvt. Ltd.; Perlen Packaging; WEIFU Films; Dai Nippon Printing Co., Ltd.; ALMA Packaging AG; Vishakha Polyfab Pvt Ltd.
Rising demand for extended shelf-life and protection against moisture, oxygen, and light is driving the growth of barrier films in pharmaceutical packaging. Additionally, increasing regulatory emphasis on safe and contamination-free drug delivery supports market expansion.
Based on the material, the polyethylene (PE) segment led the market with the largest revenue share of 32.9% in 2025.
Based on product type, the multilayer films segment led the market with the largest revenue share of 46.5% in 2025.
Asia Pacific dominated dominated with a revenue share of 40.1% in 2025.
Blister packaging segment led the market with the largest revenue share of 42.3% in 2025.The demand for blister packaging is primarily driven by its ability to offer unit-dose protection, reduce contamination risks, and improve patient compliance.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


