
- Home
- »
- IT Services & Applications
- »
-
Data Center Chip Market Size & Share Report, 2026-2033GVR Report cover

Data Center Chip Market (2026 - 2033)
Size, Share, & Trends Analysis By Chip Type (Processors, Memory, Networking), By Data Center Type (Small And Medium-Sized Data Centers, Large Data Centers), By Application (Cloud Computing), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$23.7BMarket Estimate, 2026
$26.6BMarket Forecast, 2033
$58.6BCAGR, 2026–2033
12.0%Data Center Chip Market Summary
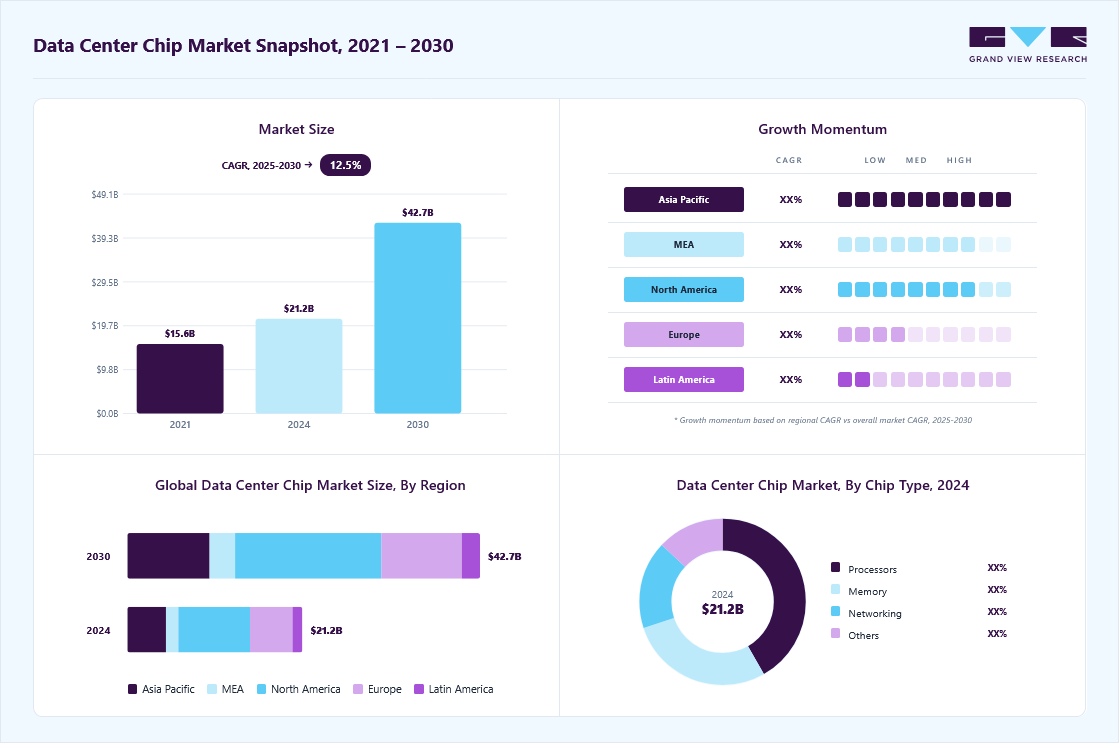
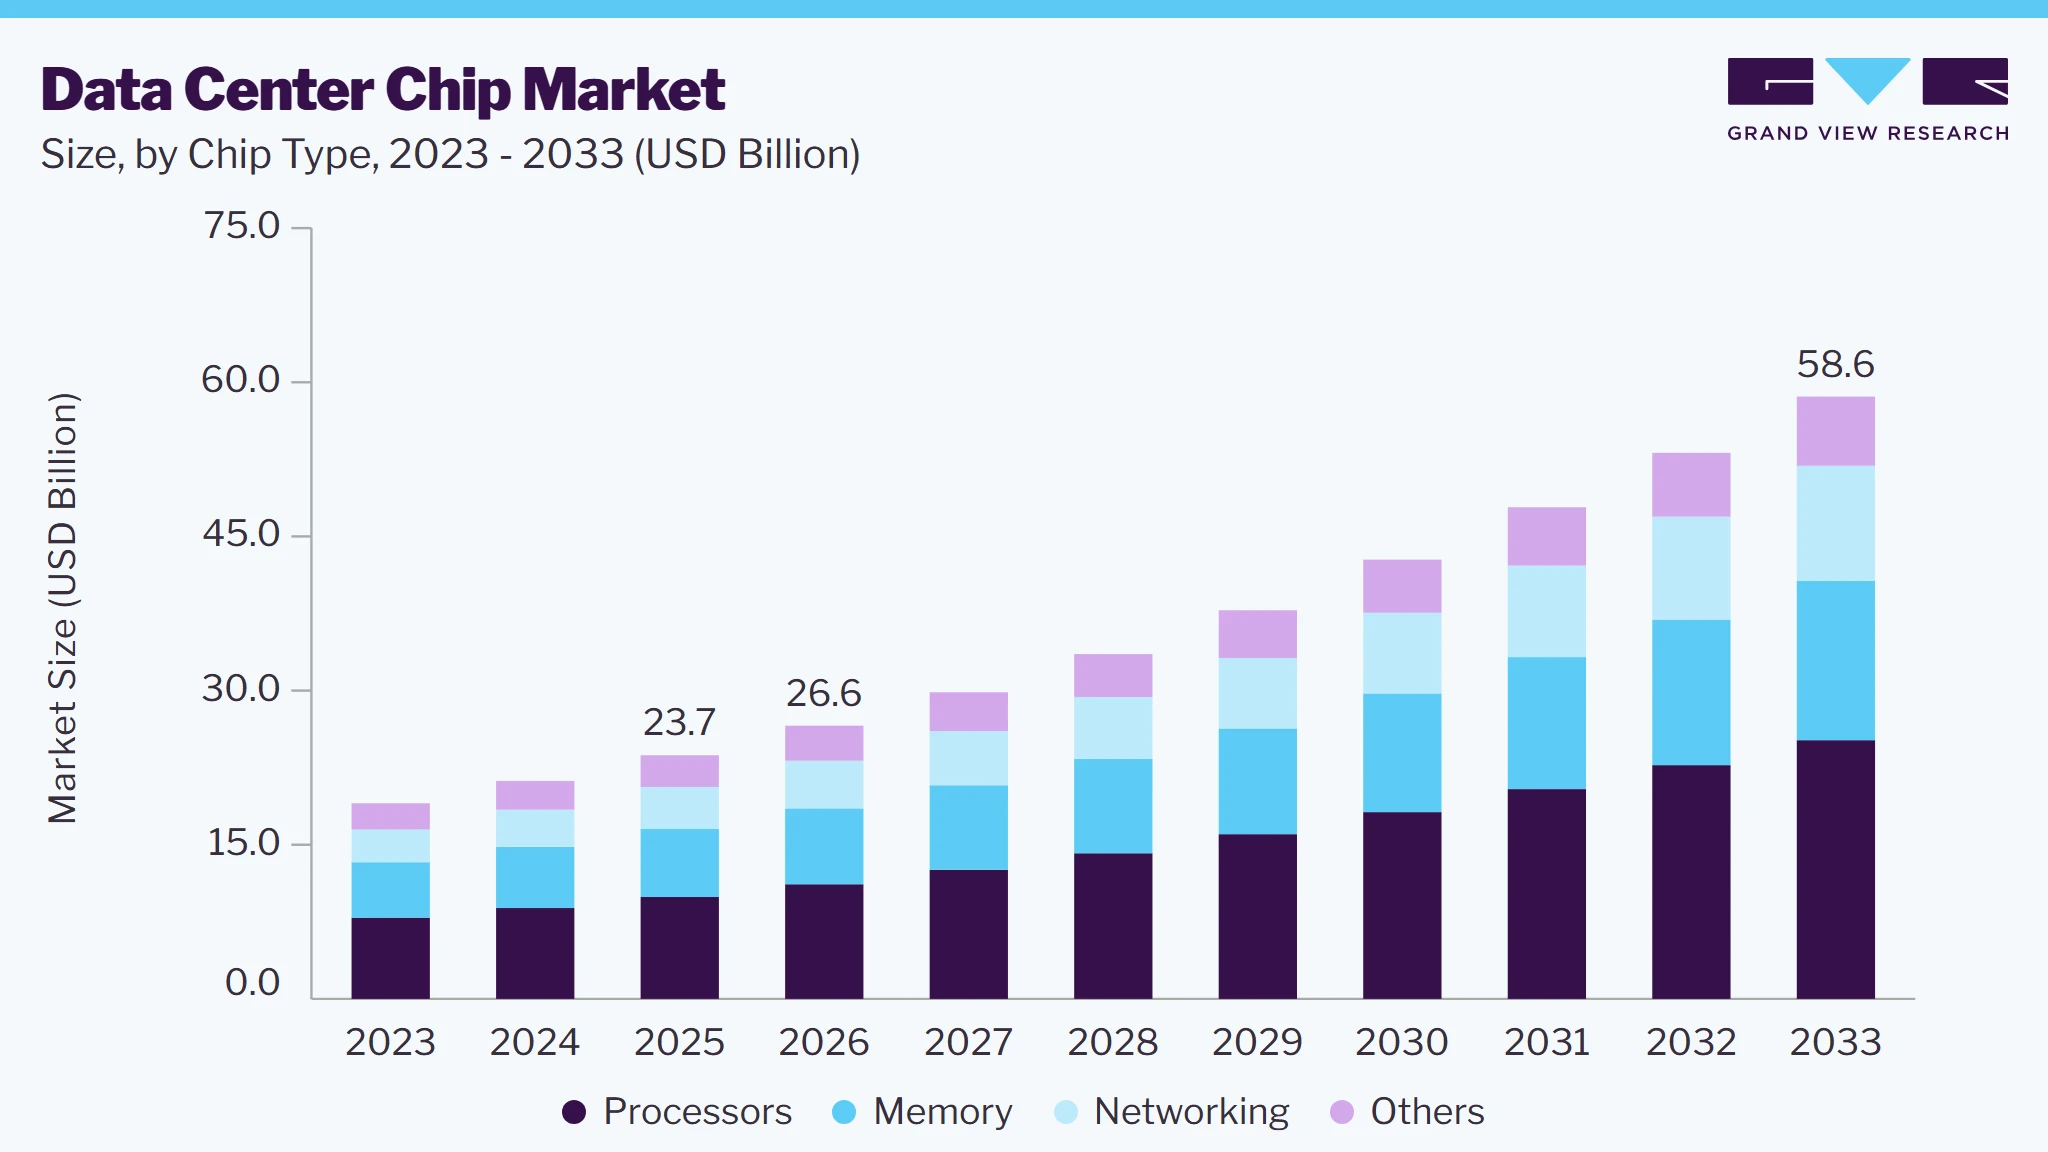
The global data center chip market size was valued at USD 23.7 billion in 2025 and is projected to grow from USD 26.6 billion in 2026 to USD 58.6 billion in 2033 at a CAGR of 12.0% from 2026 to 2033. North America market dominated, with a revenue share of 39.8% in 2025. North America is witnessing rapid expansion of AI and hyperscale data centers as cloud providers such as AWS, Microsoft Azure, Google Cloud, and Meta invest heavily in AI infrastructure.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By chip type: Processors segment dominated the market, with a revenue share of 41.8% in 2025.
- By data center type: Large Data Centers segment held the largest market share of 67.8% in 2025.
- By application: Artificial Intelligence segment held the largest revenue share of 43.6% in 2025.
- By end-use: IT segment led the market with the largest revenue share of 27.9% in 2025.
Regional Highlights
- Largest regional market: North America (39.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 23.7 Billion
- Estimated market size in 2026: USD 26.6 Billion
- Projected market size by 2033: USD 58.6 Billion
- CAGR (2026-2033): 12.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Large-scale AI training and inference workloads require advanced GPUs, CPUs, AI accelerators, and high-bandwidth memory (HBM), driving strong demand for high-performance data center chips that deliver greater computing power, efficiency, and scalability. The market is driven by several key factors such as demand for high-performance computing (HPC) and data-intensive applications surges, data centers require more advanced chip technologies to handle massive volumes of data. The increasing adoption of cloud computing, big data analytics, and artificial intelligence (AI) has fueled the need for efficient, high-capacity data center chips. These chips need to meet the processing power demands of modern applications while offering improved energy efficiency, scalability, and performance.
 To learn more about this report, Download Free Sample Report
The continuous evolution of chip architectures, with innovations such as ARM-based processors and specialized AI chips gaining prominence in the data center chip industry. ARM-based chips are gaining traction due to their energy efficiency, which is critical for large-scale data centers seeking to minimize operational costs. Moreover, the growing adoption of AI and machine learning (ML) workloads in data centers is driving the demand for chips that can handle parallel processing and complex computations with high throughput.
In addition, the proliferation of edge computing is creating a need for distributed computing resources closer to the data source, further driving demand for data center chips that offer low latency, high processing power, and reduced energy consumption. For instance, in January 2025, ZEDEDA, a U.S.-based company in edge management and orchestration, announced the opening of its new headquarters in Abu Dhabi, UAE. The move is supported by strategic investments from Alpha Wave Incubation and Prosperity7, a subsidiary of Aramco. This growth is driven by the rising demand for edge computing and AI solutions across the Middle East. The increasing reliance on 5G networks, which require robust data center infrastructure for real-time processing and low-latency communication, is also contributing to market growth.
The shift towards hybrid and multi-cloud environments is pushing the demand for more advanced data center infrastructure. Companies require flexible, scalable solutions to manage workloads across various platforms, which in turn increases the demand for high-performance chips that can seamlessly integrate with diverse cloud environments. The rising need for robust cybersecurity solutions in data centers is also spurring innovation in chip designs that offer enhanced security features, such as hardware-based encryption and secure boot mechanisms.
Market Dynamics
The data center chip market is experiencing strong growth as organizations accelerate investments in artificial intelligence (AI), cloud computing, and high-performance computing (HPC) to support increasingly compute-intensive workloads. The rapid expansion of hyperscale data centers and AI infrastructure is driving demand for high-performance CPUs, GPUs, AI accelerators, DPUs, networking ASICs, and high-bandwidth memory (HBM) capable of delivering greater processing power, bandwidth, and energy efficiency. Growing adoption of generative AI, large language models (LLMs), advanced analytics, and real-time inference is accelerating the deployment of heterogeneous computing architectures that integrate multiple specialized chips within modern servers. The increasing shift toward hybrid and multi-cloud environments, edge computing, and software-defined infrastructure is further boosting demand for advanced semiconductor solutions that optimize workload performance, scalability, and security. Advancements in chiplet architectures, advanced packaging technologies, silicon photonics, Compute Express Link (CXL), and liquid-cooled AI servers are enhancing compute density while reducing power consumption and latency. In addition, substantial investments by hyperscale cloud providers, semiconductor manufacturers, and governments in next-generation AI infrastructure and domestic chip manufacturing are strengthening supply chains and accelerating innovation. Rising deployments across cloud service providers, enterprise data centers, telecommunications, financial services, healthcare, manufacturing, research institutions, and government organizations are expected to sustain long-term growth in the global data center chip market.
The rapid adoption of generative AI, machine learning, and high-performance computing (HPC) is a key driver of the data center chip market. Hyperscale cloud providers and enterprises are investing heavily in AI infrastructure to support large language models (LLMs), AI training, and real-time inference. This is driving demand for high-performance CPUs, GPUs, AI accelerators, DPUs, networking ASICs, and high-bandwidth memory (HBM) that deliver greater compute density, memory bandwidth, and energy efficiency. The continued expansion of hyperscale data centers and AI clusters is accelerating innovation and deployment of next-generation semiconductor technologies.
The high cost of designing, manufacturing, and packaging advanced data center chips remains a significant restraint to market growth. Developing cutting-edge processors requires substantial investments in advanced process nodes, chiplet architectures, high-bandwidth memory integration, and sophisticated packaging technologies. Additionally, supply chain constraints, limited advanced foundry capacity, geopolitical uncertainties, and rising manufacturing costs can impact chip availability and increase production lead times. These challenges may delay infrastructure deployments and elevate procurement costs for cloud providers and enterprise data center operators.
The increasing adoption of custom AI processors and heterogeneous computing architectures presents significant opportunities for the data center chip market. Hyperscale cloud providers are developing proprietary AI accelerators, DPUs, and domain-specific processors to improve workload performance, optimize energy efficiency, and reduce total cost of ownership. At the same time, advancements in chiplet-based architectures, Compute Express Link (CXL), silicon photonics, advanced packaging, and liquid-cooled AI servers are enabling scalable, high-performance computing platforms. As AI adoption expands across cloud computing, financial services, healthcare, manufacturing, telecommunications, and scientific research, demand for specialized and energy-efficient data center chips is expected to grow substantially.
Market Concentration & Characteristics
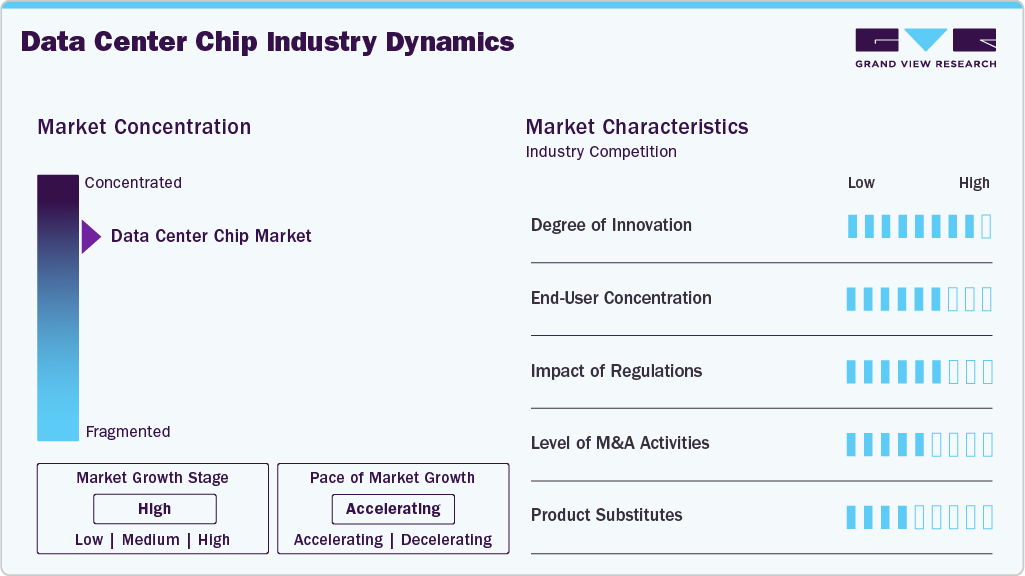
The data center chip market is highly concentrated at the top end of the value chain, particularly in AI accelerators and advanced GPUs, while remaining moderately fragmented in adjacent segments such as networking silicon, CPUs, and memory. A small number of dominant vendors led by NVIDIA, AMD, Intel, and leading hyperscaler custom silicon providers such as Google, AWS, and Microsoft control a disproportionate share of high-performance compute workloads. This concentration is especially pronounced in AI training workloads, where NVIDIA’s CUDA ecosystem and GPU acceleration stack create strong platform dominance and ecosystem lock-in.
 To learn more about this report, Download Free Sample Report
The data center chip market is highly technology-intensive and rapidly evolving, driven by the acceleration of AI workloads. Product cycles are shortening as GPU architectures, AI-specific accelerators (XPUs), chiplet-based designs, and the integration of high-bandwidth memory advance. The industry is shifting away from general-purpose CPUs toward workload-optimized silicon designed specifically for AI training and inference efficiency. Demand is primarily driven by the rapid growth of generative AI and large language models, as well as large-scale hyperscaler capital investments from AWS, Microsoft Azure, Google Cloud, and Meta. Additional demand comes from enterprise AI adoption, cloud-native application expansion, high-performance computing and simulation workloads, and increasing sovereign AI initiatives and national digital infrastructure programs aimed at strengthening local compute capacity and technological independence.
Analyst Perspective
The data center chip market is becoming a foundational pillar of AI-driven digital infrastructure as organizations accelerate investments in artificial intelligence, cloud computing, high-performance computing (HPC), and data-intensive applications. The rapid expansion of hyperscale data centers, generative AI, and large language models (LLMs) is significantly increasing demand for high-performance CPUs, GPUs, AI accelerators, networking ASICs, DPUs, and high-bandwidth memory capable of delivering superior compute performance, scalability, and energy efficiency. Enterprises and cloud service providers are increasingly adopting heterogeneous computing architectures that integrate specialized processors to optimize AI training, inference, virtualization, and cloud-native workloads while improving power efficiency and reducing total cost of ownership. The primary competitive advantage will belong to semiconductor vendors that can combine advanced chip architectures, chiplet-based designs, high-bandwidth memory, silicon photonics, and advanced packaging technologies with robust software ecosystems and developer tools. As AI adoption, edge computing, sovereign cloud initiatives, and next-generation data center deployments continue to expand, vendors capable of delivering high-performance, energy-efficient, and scalable semiconductor solutions while addressing power consumption, thermal management, and supply chain resilience will be best positioned to capitalize on long-term growth opportunities in the global data center chip market.
Chip Type Insights
Based on chip type, processors segment led the market with the largest revenue share of 41.8% in 2025 and is expected to grow at the significant CAGR over the forecast period, driven by innovations in processor architecture, such as those developed by companies like Intel, AMD, and ARM, are constantly improving computational efficiency, enabling faster processing speeds while reducing energy consumption. This technological advancement plays a crucial role in the adoption of these processors, as data centers seek energy-efficient solutions to lower operating costs. With the growing complexity of applications, such as edge computing, IoT, and virtualized environments, the processors segment in the data center chip market is positioned for sustained growth as these technological demands continue to evolve. The processors segment is further segmented into central processing units (CPUs), Graphics Processing Units (GPUs), field-programmable gate arrays (FPGAs), application-specific integrated circuits (ASICs), and others
The networking segment is anticipated to grow at a CAGR of 14.0% during the forecast period, driven by the adoption of disaggregated and software-defined networking (SDN) architectures, which rely on programmable chips to enhance flexibility and scalability. Open-source initiatives like SONiC (Software for Open Networking in the Cloud) are accelerating this trend, fostering demand for programmable ASICs and FPGAs that enable dynamic traffic management. The rise of edge data centers further amplifies the need for compact, power-efficient networking chips capable of real-time processing for applications like autonomous vehicles and industrial IoT. The networking segment is further segmented intonetwork interface cards (NICs)/network adapters, and interconnects.
Data Center Type Insights
Based on data center type, large data centers segment led the market with the largest revenue share of 67.8% in 2025. As cloud service providers like AWS, Microsoft Azure, and Google Cloud expand their global footprints to support digital transformation, they require increasingly powerful and efficient chips to manage massive workloads. This has led to a surge in demand for high-performance server CPUs, GPUs, and custom ASICs optimized for virtualization, containerization, and distributed computing. The shift toward AI-as-a-Service (AIaaS) and big data analytics further necessitates advanced silicon capable of handling parallel processing and real-time decision-making at scale.
The small and medium-sized data centers segment is expected to grow at a significant CAGR over the forecast period, driven by the increasing decentralization of computing power and the rise of edge-native applications. Unlike hyperscale facilities, SMDCs prioritize space efficiency, modular scalability, and cost-effective performance, creating a unique demand for chips that balance power with compact designs. The proliferation of IoT devices, Industry 4.0 automation, and real-time analytics is pushing these facilities to adopt system-on-chip (SoC) solutions and low-power ARM-based processors, which deliver high throughput without excessive energy consumption.
Application Insights
Based on application, the artificial intelligence (AI) segment led the market with the largest revenue share of 43.6% in 2025 due to the rapid adoption of machine learning, deep learning, and generative AI workloads across industries. These applications require specialized processing capabilities that go beyond traditional CPUs, driving demand for GPUs, TPUs, and AI-accelerator chips optimized for matrix operations, parallel computing, and high-speed inference. The deployment of AI in areas such as predictive analytics, autonomous systems, natural language processing, and image recognition is increasing the need for high-performance chips capable of handling massive datasets in real time.
The cloud computing segment is expected to grow at a significant CAGR over the forecast period owing to the global shift from on-premises IT infrastructure to cloud-based platforms. Enterprises across all sectors are increasingly embracing Infrastructure-as-a-Service (IaaS), Platform-as-a-Service (PaaS), and Software-as-a-Service (SaaS) solutions to gain flexibility, reduce capital expenditure, and scale operations rapidly. This transition demands robust and versatile chips that can efficiently manage diverse cloud workloads such as database processing, container orchestration, and serverless computing.
End-use Insights
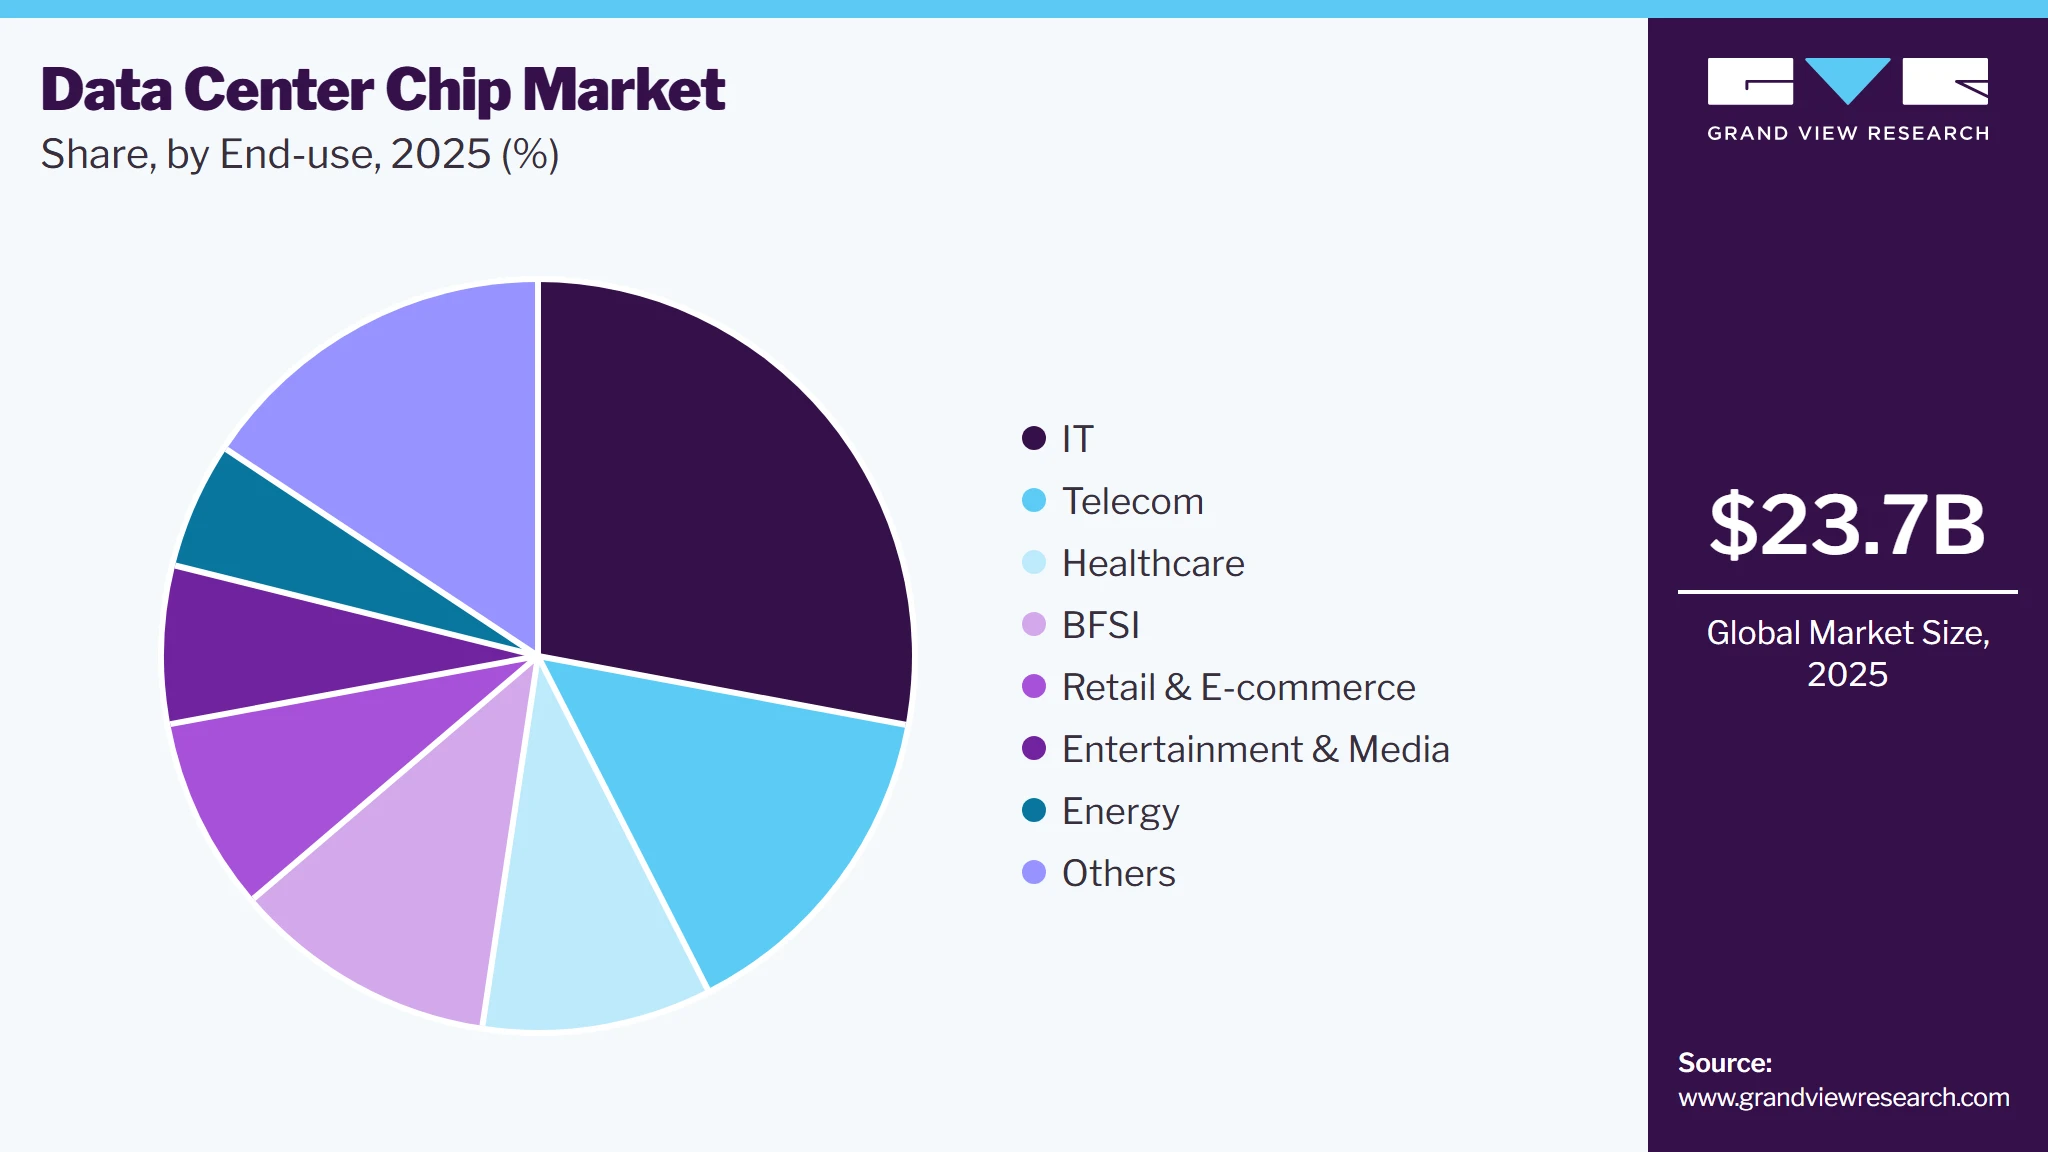
Based on end-use, the IT segment led the market with the largest revenue share of 27.9% in 2025 due to the evolution of DevOps, responsive methodologies, and continuous integration/continuous deployment (CI/CD) pipelines, which require substantial computational power and real-time responsiveness. These demands are fueling the adoption of chips that optimize workload orchestration, virtualization, and containerization. Moreover, the increasing reliance on data-intensive services such as backup and recovery, IT monitoring, and digital workspace management further amplifies the need for efficient, scalable chip solutions.
 To learn more about this report, Download Free Sample Report
The energy segment is expected to grow at a significant CAGR over the forecast period driven by the increasing adoption of smart grid technologies, digital twins, and real-time energy management systems. As energy companies modernize their infrastructure, they rely heavily on data centers to process vast volumes of operational data for grid monitoring, predictive maintenance, and energy forecasting. This transformation necessitates advanced chips capable of handling time-sensitive and data-intensive workloads, particularly for edge computing scenarios where fast local processing is critical.
Regional Insights
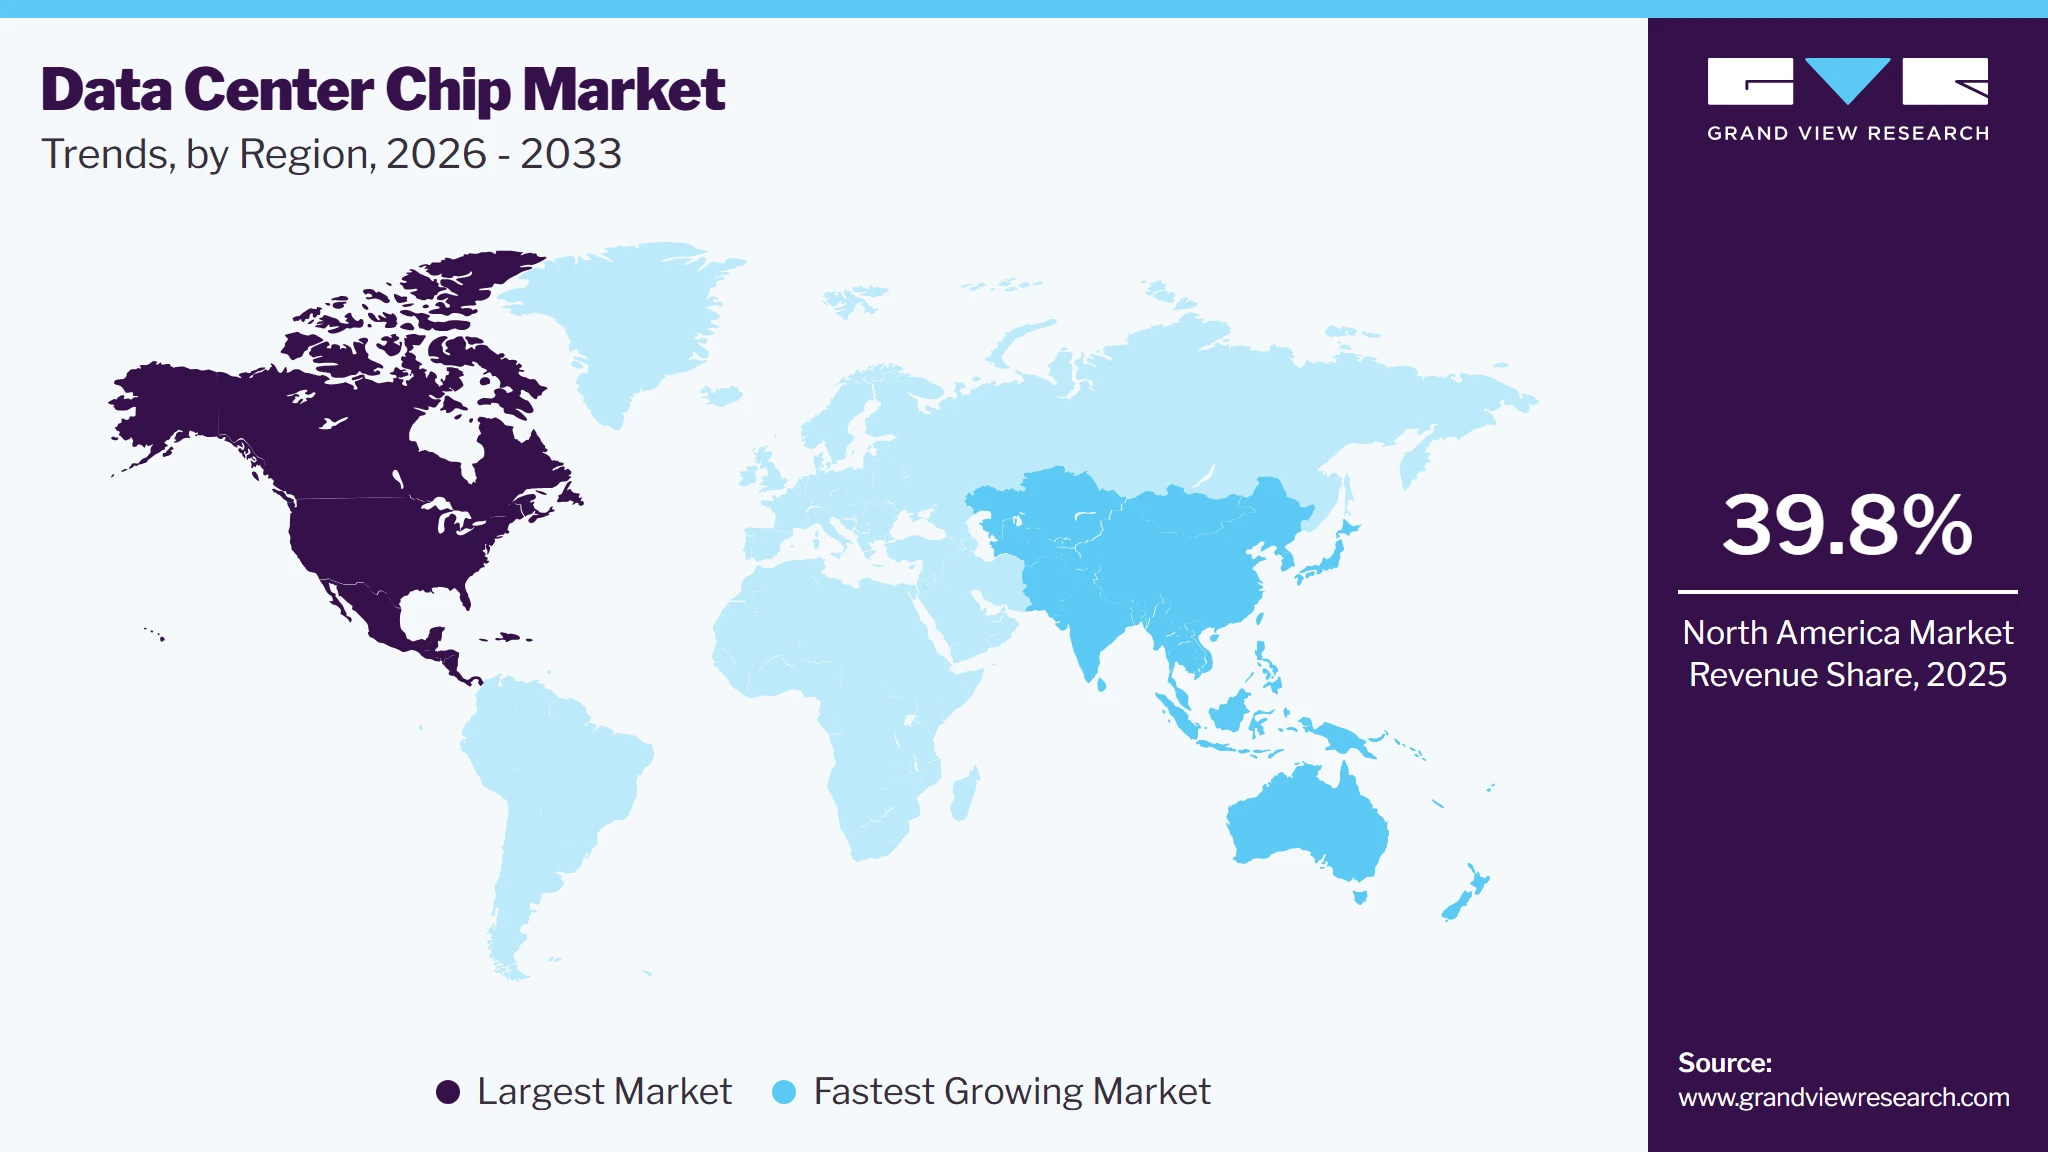
North America dominated the data center chip market with the largest revenue share of 39.8% in 2025 by the region’s dominance in cloud computing, artificial intelligence (AI), and big data analytics. With major companies such as Amazon, Google, and Microsoft leading the digital transformation, there is a growing demand for advanced data center chips capable of handling large-scale computing workloads. Moreover, the rapid growth of the Internet of Things (IoT) and 5G technologies is accelerating the need for high-performance, energy-efficient chips that can support the increasing data traffic in the region.
 To learn more about this report, Download Free Sample Report
U.S. Data Center Chip Industry Trends
The data center chip market in the U.S. held the largest share in the North America region in 2025 due to the heavy investments in AI/ML, and autonomous systems, which require cutting-edge data center chips. The U.S. continues to invest in next-generation data centers that leverage powerful processors, including specialized AI chips, for enhanced computational capabilities. For instance, in January 2025, Microsoft announced its plans to invest USD 80 billion in AI-powered data centers during 2025, with over half of the funding directed toward projects in the U.S. These new facilities feature cutting-edge technologies, including GPUs and AI accelerator chips, to significantly enhance computing power and support the growing demand for AI-driven solutions.
Europe Data Center Chip Industry Trends
The data center chip market in Europe is anticipated to register a considerable growth from 2025 to 2030, driven by the region's strong push toward digitalization and sustainability. Many European companies are modernizing their data centers with energy-efficient chips to align with green initiatives and carbon-neutral goals. Moreover, the adoption of advanced computing technologies such as AI, blockchain, and cloud computing is fueling the demand for high-performance processors.
The U.K. data center chip market is expected to grow rapidly in the coming years due to the rapid adoption of cloud data center type, digital transformation, and 5G network rollout. The U.K. has been increasingly focusing on improving its infrastructure to support high-speed data processing and storage, which in turn drives the need for advanced data center chips.
The data center chip market in Germany held a substantial market share in 2024, driven by the industrial sector's push toward digitalization and Industry 4.0, which relies on data centers to process real-time data generated by smart factories and automation systems. Germany's automotive industry, in particular, is embracing AI and IoT technologies that require high-performance chips to support autonomous driving and manufacturing processes.
Asia Pacific Data Center Chip Industry Trends
Asia Pacific is expected to register the fastest CAGR of 13.5% from 2025 to 2030, due to the region's booming digital economy and the increasing number of data centers being established to cater to the growing internet user base. Countries such as India and South Korea are witnessing significant investments in data center infrastructure, driving demand for advanced chips capable of supporting massive data processing, cloud computing, and AI applications. The rise of smart cities and IoT in this region is further contributing to the need for efficient, high-performance data center chips.
The data center chip market in Japan is expected to grow rapidly in the coming years. The country’s high reliance on automation in manufacturing and the ongoing adoption of smart technologies are creating a demand for data center chips that can handle complex tasks such as real-time data processing and machine learning. Moreover, Japan’s commitment to reducing energy consumption is encouraging the use of energy-efficient chips in data centers to meet sustainability goals in the country.
The China data center chip market held a substantial market share in 2024. The government's support for the development of a domestic semiconductor industry, combined with the rapid growth of cloud computing, big data, and 5G infrastructure, leads to demand for advanced chips for data centers. Moreover, the increasing adoption of AI and smart devices across various industries, including e-commerce, telecommunications, and manufacturing, is driving the need for efficient processing power.
Key Data Center Chip Company Insights
Key players operating in the data center chip industry are NVIDIA Corporation, Micron Technology, Inc., STMicroelectronics, and Sensirion AG. The companies are focusing on various strategic initiatives, including new product development, partnerships & collaborations, and agreements to gain a competitive advantage over their rivals. The following are some instances of such initiatives.
-
In February 2025, Intel Corporation introduced the Intel Xeon 6 processors, featuring performance cores optimized for delivering top-tier performance in data centers, including up to twice the performance in AI processing. In addition, these new processors, designed for network and edge applications, incorporate Intel vRAN Boost, which enhances capacity by up to 2.4 times for radio access network (RAN) workloads.
-
In February 2025, STMicroelectronics introduced a new computer chip designed for the growing AI in data center developed in partnership with Amazon Web Data center type (AWS). Utilizing photonics technology, the chip relies on light instead of electricity, enhancing speed while reducing power consumption in AI-driven data centers. These advanced chips are expected to play a key role in transceivers, essential components in data center infrastructure.
-
In October 2024, NVIDIA unveiled the NVIDIA Grace CPU, a high-performance data center processor designed to deliver exceptional energy efficiency while being optimized for large-scale data center performance. This new CPU aims to revolutionize the data center industry by offering enhanced energy efficiency and performance at scale.
Key Data Center Chip Companies:
The following key companies have been profiled for this study on the data center chip market.
-
Advanced Micro Devices, Inc.
-
Alibaba
-
Arm Holdings
-
Broadcom Inc.
-
Google
-
Huawei Technologies Co., Ltd.
-
IBM Corporation
-
Intel Corporation
-
Marvell
-
Micron Technology, Inc.
-
NVIDIA Corporation
-
Qualcomm
-
SAMSUNG
-
STMicroelectronics
-
Texas Instruments Incorporated
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (NVIDIA, Intel, AMD, Broadcom, Marvell Technology, Micron Technology, Samsung Electronics, SK hynix)
- Established semiconductor companies focus on developing high-performance CPUs, GPUs, AI accelerators, networking ASICs, DPUs, and advanced memory solutions for hyperscale, enterprise, and AI data centers. Their strategies emphasize continuous R&D, advanced process node adoption, chiplet architectures, high-bandwidth memory (HBM), strategic foundry partnerships, ecosystem expansion, and collaborations with hyperscalers, server OEMs, and cloud service providers to address AI, cloud computing, and HPC workloads.
- These companies benefit from strong technological expertise, extensive patent portfolios, global manufacturing and supply chain capabilities, established relationships with hyperscale cloud providers and server manufacturers, and comprehensive product portfolios. Their leadership in advanced semiconductor design, software ecosystems, AI frameworks, and networking technologies enables them to deliver high-performance, energy-efficient chips with strong scalability and reliability for next-generation data center infrastructure.
- Established vendors face challenges including high R&D and manufacturing costs, dependence on advanced foundries, geopolitical and supply chain risks, lengthy product development cycles, and increasing competition in AI silicon. Maintaining technology leadership while managing rising power consumption, advanced packaging complexity, and rapid shifts in AI workload requirements can impact profitability and time-to-market.
Emerging Players (Groq, Cerebras Systems, SambaNova Systems, Ampere Computing, Tenstorrent)
- Emerging companies primarily focus on developing specialized AI processors, domain-specific accelerators, RISC-V-based processors, wafer-scale computing architectures, and energy-efficient server chips optimized for AI training, inference, and high-performance computing. Their strategies emphasize architectural innovation, software optimization, lower total cost of ownership (TCO), and strategic partnerships with hyperscalers, enterprises, research institutions, and cloud infrastructure providers.
- Emerging vendors offer innovative chip architectures tailored for AI workloads, enabling higher performance per watt, lower latency, and improved scalability compared with conventional processors in specific applications. Their agility, faster innovation cycles, specialized software stacks, and focus on AI-native computing make them attractive to organizations deploying large language models (LLMs), generative AI, and next-generation AI infrastructure.
- Emerging companies generally have limited manufacturing scale, lower brand recognition, smaller customer bases, and greater dependence on third-party foundries and packaging providers. They also face challenges in building mature software ecosystems, securing long-term enterprise adoption, expanding global sales channels, and competing against established semiconductor leaders with broader product portfolios, stronger financial resources, and deeply integrated customer ecosystems.
Data Center Chip Market Report Scope
Report Attribute
Details
Market size in 2025
USD 23.7 billion
Estimated market size in 2026
USD 26.6 billion
Projected market size by 2033
USD 58.6 billion
Growth rate
CAGR of 12.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Chip Type, data center type, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Advanced Micro Devices, Inc.; Alibaba; Arm Holdings; Broadcom Inc.; Google; Huawei Technologies Co., Ltd.; IBM Corporation; Intel Corporation; Marvell; Micron Technology, Inc.; NVIDIA Corporation; Qualcomm; SAMSUNG; STMicroelectronics; Texas Instruments Incorporated
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Data Center Chip Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global data center chip market report based on game chip type, data center type, application, end-use, and region:
-
Chip Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Processors
-
Central Processing Units (CPUs)
-
Graphics Processing Units (GPUs)
-
Field-Programmable Gate Arrays (FPGAs)
-
Application-Specific Integrated Circuits (ASICs)
-
Others
-
-
Memory
-
High Bandwidth Memory (HBM)
-
Double Data Rate (DDR)
-
-
Networking
-
Network Interface Cards (NICs)/Network Adapters
-
Interconnects
-
-
Others
-
-
Data Center Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Small and Medium-Sized Data Centers
-
Large Data Centers
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Artificial Intelligence (AI)
-
Cloud Computing
-
Big Data Analytics
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
IT
-
Telecom
-
Healthcare
-
BFSI
-
Retail & E-commerce
-
Entertainment & Media
-
Energy
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The data center chip market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each data center chip segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Chip Type
Revenue capture definition
Processors
Semiconductor chips that execute computing instructions and process workloads within data center servers. They provide the computational power required for cloud computing, AI, virtualization, databases, and enterprise applications.
Memory
Memory chips that temporarily or permanently store data required for fast processing, workload execution, and application performance within data center infrastructure.
Networking
Semiconductor devices enabling high-speed communication, networking, and data transfer between servers, storage systems, and external networks within data centers.
Segment - Data Center Type
Revenue capture definition
Small and Medium-Sized Data Centers
Facilities operated by enterprises, government organizations, regional cloud providers, and edge operators with relatively limited server capacity. These data centers primarily support local business applications, branch operations, disaster recovery, and edge computing workloads.
Large Data Centers
Large-scale enterprise, colocation, and hyperscale facilities containing thousands of servers that support cloud computing, AI, big data analytics, HPC, and global digital services. These facilities require high-performance processors, accelerators, networking chips, and memory solutions.
Segment - Application
Revenue capture definition
Artificial Intelligence (AI)
Data center chips deployed for AI model training, inference, generative AI, machine learning, deep learning, recommendation engines, computer vision, and natural language processing workloads.
Cloud Computing
Chips used to power public, private, and hybrid cloud platforms by supporting virtualization, containerization, storage services, web applications, databases, and cloud-native workloads.
Big Data Analytics
Semiconductor solutions designed to accelerate large-scale data processing, business intelligence, predictive analytics, scientific computing, and real-time analytics across distributed computing environments.
Others
Includes applications such as branch office IT, content delivery, educational campuses, healthcare facilities, retail stores, transportation hubs, smart city infrastructure, and mobile command centers.
Segment - End-use
Revenue capture definition
IT
Technology companies, software providers, cloud service providers, and enterprise IT organizations deploying data center chips for computing, virtualization, storage, AI, and digital infrastructure.
Telecom
Telecommunications operators utilizing data center chips to support 5G core networks, network virtualization, edge computing, content delivery, and communication services.
Healthcare
Hospitals, research institutions, pharmaceutical companies, and healthcare providers deploying data center chips for AI diagnostics, medical imaging, genomics, electronic health records, and healthcare analytics.
BFSI
Banks, financial institutions, insurance companies, and fintech organizations using high-performance data center chips for transaction processing, fraud detection, risk analytics, algorithmic trading, and regulatory compliance.
Retail & E-commerce
Retailers and e-commerce platforms leveraging data center chips for recommendation engines, customer analytics, inventory optimization, digital payments, and omnichannel commerce.
Entertainment & Media
Media companies, streaming platforms, gaming providers, and content creators utilizing high-performance computing infrastructure for video streaming, rendering, content delivery, AI content generation, and interactive entertainment.
Energy
Oil & gas companies, utilities, renewable energy providers, and grid operators deploying data center chips for smart grid management, seismic analysis, predictive maintenance, energy optimization, and industrial AI applications.
Others
Includes government organizations, defense, manufacturing, education, research institutions, transportation, automotive, and other industries utilizing data center chips for mission-critical computing, simulation, cybersecurity, and data-intensive workloads.
Estimation Model
Layer
Question
Analysis
AI, Cloud & Digital Infrastructure Demand Layer
Who drives demand for Data Center Chips?
Identify organizations investing in AI infrastructure, hyperscale cloud, enterprise digital transformation, high-performance computing (HPC), edge computing, and next-generation networking. Assess cloud service providers, colocation operators, telecom companies, government agencies, research institutions, financial organizations, healthcare providers, and large enterprises deploying AI, analytics, and mission-critical workloads to estimate the Total Addressable Market (TAM).
Data Center Infrastructure Expansion Layer
Where is demand for Data Center Chips generated?
Evaluate expansion of hyperscale, enterprise, colocation, and edge data centers, along with increasing server deployments, AI clusters, GPU farms, and cloud infrastructure. Assess investments in AI factories, digital transformation, 5G, hybrid cloud, and HPC facilities to determine the Operationally Reachable Market (ORM) for processors, accelerators, networking chips, and memory.
Chip Deployment & Technology Adoption Layer
Who adopts Data Center Chips?
Analyze adoption across cloud providers, server OEMs, enterprises, telecommunications companies, government & defense organizations, research institutions, healthcare providers, BFSI, retail, manufacturing, and media companies. Assess deployment of CPUs, GPUs, AI ASICs, FPGAs, DPUs, SmartNICs, networking ASICs, HBM, and DDR memory supporting AI, virtualization, analytics, and cloud workloads to identify deployment opportunities and end-user demand.
Revenue Generation Layer
How is revenue generated?
Assess revenue generated from the sales of data center processors (CPUs, GPUs, AI accelerators, FPGAs), networking chips (NICs, DPUs, switch ASICs, interconnects), and server memory (HBM, DDR). Include revenue from OEM server shipments, hyperscaler infrastructure procurement, enterprise upgrades, AI server deployments, networking hardware integration, and replacement cycles. Analyze average selling prices (ASPs), shipment volumes, technology node transitions, and adoption of premium AI chips to estimate market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Data Center Chip Vendor Competitive Benchmarking
Assessed leading data center chip vendors based on processor portfolio (CPU, GPU, AI ASIC, FPGA, DPU/IPU), AI performance, memory bandwidth, networking capabilities, process node, power efficiency, software ecosystem, packaging technologies, partnerships, pricing strategies, geographic presence, innovation roadmap, and market share.
Enables stakeholders to benchmark competitors, identify technology leaders, evaluate product differentiation, assess AI and cloud infrastructure capabilities, and formulate competitive product development and go-to-market strategies.
Chip Architecture & Technology Assessment
Evaluated demand across CPUs, GPUs, AI ASICs, FPGAs, DPUs, HBM, DDR memory, networking ASICs, and interconnect technologies based on workload performance, power efficiency, scalability, AI readiness, deployment models, and total cost of ownership (TCO).
Enables semiconductor vendors, OEMs, and investors to optimize product portfolios, prioritize R&D investments, identify emerging technology trends, and align chip development strategies with evolving AI, cloud computing, and hyperscale data center requirements.
Pricing & Average Selling Price (ASP) Analysis
Assessed ASP trends by chip category (CPU, GPU, AI ASIC, FPGA, HBM, networking chips), technology generation, performance tier, and customer segment.
Helps stakeholders estimate revenue potential, optimize pricing strategies, evaluate profitability, and improve market forecasting accuracy.
Frequently Asked Questions About This Report
The processors segment led with a 41.8% revenue share in 2025 and is the fastest-growing segment.
The large data centers segment led with a 67.8% revenue share in 2025 and is the fastest-growing segment.
The artificial intelligence (AI) segment led the market with the largest revenue share of 43.6% in 2025.
Key players include Advanced Micro Devices, Inc., Alibaba, Arm Holdings, Broadcom Inc., Google, Huawei Technologies Co., Ltd., IBM Corporation, Intel Corporation, Marvell, Micron Technology, Inc., NVIDIA Corporation, Qualcomm, SAMSUNG, STMicroelectronics, Texas Instruments Incorporated.
The global data center chip market size was valued at USD 23.7 billion in 2025 and is estimated at USD 26.6 billion in 2026.
The global data center chip market is expected to grow at a CAGR of 12.0% from 2026 to 2033,reaching USD 58.6 billion by 2033.
As demand for high-performance computing (HPC) and data-intensive applications surges, data centers require more advanced chip technologies to handle massive volumes of data. The increasing adoption of cloud computing, big data analytics, and artificial intelligence (AI) has fueled the need for efficient, high-capacity data center chips.
North America dominated with 39.8% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
IT Services & Applications Research Team
Technology · IT Services & ApplicationsThis report was authored by the it services & applications research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the it services & applications segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


