
- Home
- »
- HVAC & Construction
- »
-
Fire Protection System Market Size, Share Report 2026-2033GVR Report cover

Fire Protection System Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Product, Service), By Application (Commercial, Industrial, Residential), By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa), And Forecasts
Market Size, 2025
$94.9BMarket Estimate, 2026
$101.2BMarket Forecast, 2033
$156.2BCAGR, 2026–2033
6.4%Fire Protection System Market Summary
The global fire protection system market size was valued at USD 94.9 billion in 2025 and is projected to grow from USD 101.2 billion in 2026 to USD 156.2 billion by 2033, at a CAGR of 6.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 34.9% in 2025. Governments and regulatory bodies are imposing stringent fire and safety regulations for commercial and industrial infrastructure.
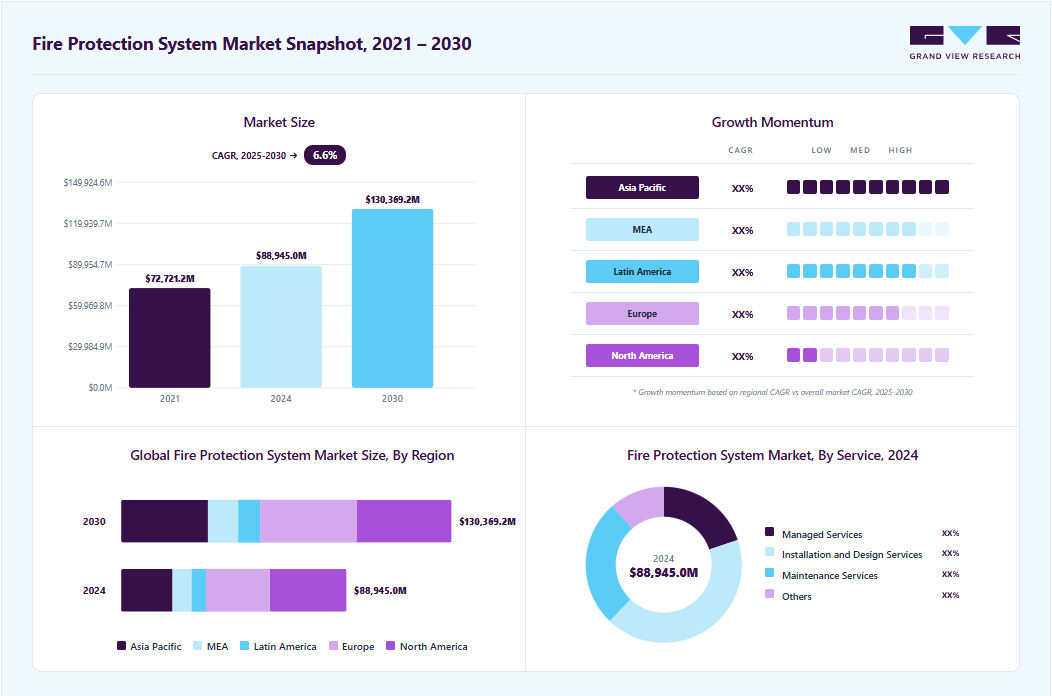 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- Based on component: Products held the largest revenue share of 73.0% in 2025.
- Based on application: Commercial held the largest revenue share of 46.4% in 2025.
Regional Highlights
- Largest regional market: North America (34.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 94.9 Billion
- Estimated market size in 2026: USD 101.2 Billion
- Projected market size by 2033: USD 156.2 Billion
- CAGR (2026-2033): 6.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
This has encouraged the sales of fire protection systems across all end use and promoted market growth. Besides, growing awareness towards incorporation of fire protection systems for residential application is also boosting market growth. The adoption of fire alarm and detection systems across commercial, residential, and industrial facilities is being driven by increasing investments in infrastructure protection, stringent fire safety regulations, and growing awareness of the need to safeguard assets and human lives. Regulatory mandates requiring the installation of fire safety equipment are encouraging organizations to upgrade or deploy reliable detection and alarm systems. For instance, NFPA 90A and various model mechanical codes require smoke detection in designated HVAC ducts, enabling systems to automatically shut down during fire incidents. To learn more about this report, Download Free Sample Report
Additionally, the integration of internet of things (IoT), wireless sensor networks, and connected fire safety devices enables real-time monitoring, automated alerts, faster emergency response, and improved communication between fire detection and suppression systems. Growing emphasis on incorporating fire and security risk assessments into building design is also encouraging the adoption of advanced solutions.
However, high installation and maintenance costs remain a key market restraint. Fire alarm systems are often customized according to facility-specific requirements, resulting in variations in system complexity and deployment costs. The increasing use of sophisticated sensors, wireless technologies, and electronic components further raises equipment and service costs, despite providing improved sensitivity, reliability, and response times.
Market Dynamics
The fire protection system market is experiencing steady growth, supported by increasingly stringent fire safety regulations, rapid urbanization, expanding commercial and industrial infrastructure, and growing awareness of life and property protection. Fire protection solutions, including fire detection and alarm systems, suppression equipment, sprinklers, and emergency response technologies, play a critical role in minimizing fire-related fatalities and property damage, ensuring business continuity, and helping organizations comply with safety standards.
Increasing investments in smart buildings, data centers, manufacturing facilities, healthcare infrastructure, and transportation networks are creating additional demand for advanced fire protection solutions. At the same time, the rising occurrence of fire incidents and greater emphasis on workplace and occupant safety are encouraging businesses and facility operators to strengthen their fire protection infrastructure. The integration of IoT-enabled monitoring, connected sensors, real-time alerts, and automated suppression technologies is further enhancing system capabilities and enabling faster, more coordinated responses to fire emergencies. These developments are expected to support the continued adoption of comprehensive fire protection systems across residential, commercial, and industrial applications.
The growing demand for intelligent and integrated fire protection solutions is driving market growth. The organizations are increasingly prioritizing proactive fire prevention, rapid detection, and effective emergency response. Building owners and facility managers are seeking customized fire safety systems that address specific operational risks, building configurations, and regulatory requirements across commercial, industrial, residential, and institutional facilities. In response, solution providers are developing modular and scalable solutions that integrate fire detection, alarms, suppression, monitoring, and emergency communication capabilities.
The advent of smart buildings and connected infrastructure is further accelerating adoption of intelligent fire protection systems. IoT-enabled sensors and cloud-based monitoring allow facility operators to remotely monitor fire safety conditions, receive real-time alerts, and respond more quickly to potential incidents. In addition, growing awareness of fire risks and stricter safety standards are encouraging organizations to modernize existing systems and invest in advanced technologies. The increasing focus on occupant safety, asset protection, operational continuity, and regulatory compliance is therefore expected to create sustained demand for flexible, connected, and technologically advanced fire protection systems worldwide.
The high costs associated with the installation, maintenance, and periodic upgrading of fire protection systems are a key restraint on market growth. Advanced fire detection, alarm, suppression, and monitoring solutions often require substantial upfront investment, particularly in large commercial, industrial, and critical infrastructure facilities. Ongoing expenses associated with inspection, testing, maintenance, and regulatory compliance further increase the financial burden on end users. Budget constraints may deter SMEs and building owners in cost-sensitive markets to investments in comprehensive fire protection solutions. In addition, the complexity of integrating advanced systems with legacy building infrastructure can increase installation and maintenance costs, potentially restricting the adoption across certain regions and end-use sectors.
The growing adoption of smart buildings and connected infrastructure offers a significant growth opportunity for the fire protection system market. Increasing deployment of IoT-enabled fire detection, monitoring, and suppression solutions is enabling real-time monitoring, automated alerts, predictive maintenance, and faster emergency response. Integration with building management systems (BMS), artificial intelligence (AI), and cloud-based platforms is further improving system efficiency, remote monitoring, and risk management while supporting regulatory compliance.
The expansion of data centers, healthcare facilities, transportation hubs, and high-rise commercial buildings is driving demand for advanced fire protection solutions that meet complex, critical safety requirements. As organizations increasingly prioritize digital transformation, operational resilience, and proactive risk management, the integration of intelligent technologies into fire safety infrastructure is expected to create significant opportunities for market growth.
Market Concentration & Characteristics
The fire protection system market is moderately consolidated, with multinational fire safety companies, smart building technology providers, and specialized fire protection equipment manufacturers accounting for a significant portion of the market. Leading players face intense competition with respect to product reliability, technological innovation, regulatory compliance, service capabilities, distribution networks, and comprehensive fire safety portfolios. Established companies maintain strong market positions through broad offerings that include fire detection, alarm, suppression, sprinkler, and emergency communication systems, supported by extensive installation, maintenance, and service networks.
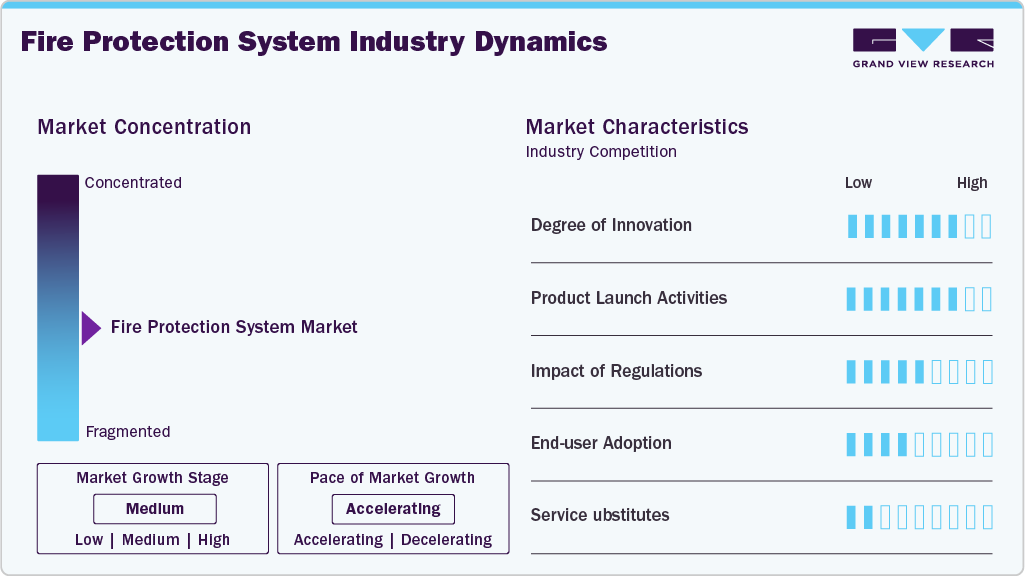 To learn more about this report, Download Free Sample Report
Strategic partnerships, acquisitions, technology integration, and geographic expansion are common strategies adopted by market participants to strengthen their competitive positions and expand end-to-end fire safety capabilities. Recurring revenue from maintenance contracts, inspections, system upgrades, and monitoring services also supports customer retention and long-term relationships. Although multinational companies typically have a stronger presence in large commercial, industrial, and infrastructure projects, regional manufacturers and service providers remain competitive in local markets by offering cost-effective solutions and products aligned with country-specific fire safety regulations.
Analyst Perspective
The fire protection systems market is driven by increasingly stringent fire safety regulations, rapid urbanization, expanding commercial and industrial infrastructure, and growing awareness of life and asset protection. Rising investments in smart buildings, data centers, manufacturing facilities, healthcare infrastructure, and transportation networks are generating demand for advanced fire detection, suppression, sprinkler, and emergency response solutions.
However, high installation and maintenance costs, complex regulatory requirements, integration challenges with existing infrastructure, and budget constraints among small and medium-sized enterprises may limit the pace of market adoption. Despite these challenges, technological advancements in IoT-enabled monitoring, AI-based fire analytics, cloud-connected safety platforms, and predictive maintenance are creating new growth opportunities. These innovations are improving real-time monitoring, operational efficiency, and emergency response capabilities, supporting the adoption of advanced fire protection solutions across developed and emerging markets.
Component Insights
The product segment accounted for the largest revenue share of 73.0% in 2025, supported by the increasing implementation of stringent fire safety regulations across residential, commercial, industrial, and institutional facilities. Governments and regulatory bodies worldwide are actively mandating the installation of fire detection, alarm, suppression, and sprinkler systems to enhance occupant safety and minimize property damage. In addition, rapid urbanization and the expansion of smart buildings, manufacturing facilities, data centers, and critical infrastructure are driving demand for advanced fire protection equipment. Ongoing innovations in sensors, wireless connectivity, and intelligent fire detection technologies are further strengthening growth in the product segment.
The services segment is expected to register a significant CAGR of 5.2% from 2026 to 2033, driven by the growing need for regular inspection, testing, maintenance, and system upgrades to ensure operational reliability and regulatory compliance. Periodic assessments and certification requirements under fire safety standards are generating recurring demand for professional services. Furthermore, aging infrastructure and the expanding installed base of fire protection systems are driving demand for retrofit and modernization services. The growing adoption of connected fire protection solutions and remote monitoring technologies is also creating demand for specialized technical support, predictive maintenance, and lifecycle management services, supporting sustained growth in the services segment.
Product Insights
The fire detection systems segment accounted for the largest revenue share of 58.1% in 2025, supported by stringent fire safety regulations and increasing requirements for early fire detection across residential, commercial, industrial, and institutional facilities. Fire detection systems integrate multiple devices to identify and alert occupants to fire, smoke, carbon monoxide, and other emergency conditions through audible and visual notification mechanisms. Regulatory frameworks and building safety codes, including requirements established by the National Fire Protection Association (NFPA) in the U.S. and the Building Code of Australia, mandate the installation of fire detection equipment in designated facilities, thereby supporting segment demand.
The fire suppression systems segment is expected to witness a consistent growth of 3.9%, driven by increasing adoption of advanced and environmentally friendly suppression agents. Fire suppression systems are designed to control or extinguish fires and prevent re-ignition through the targeted application of water, dry chemicals, or other suppression agents. The continued expansion of commercial buildings and industrial facilities is creating additional demand for effective fire suppression solutions. Furthermore, new construction, infrastructure development, and renovation projects are subject to increasingly stringent fire safety requirements, encouraging investments in compliant suppression systems. These regulatory obligations, combined with growing awareness of fire safety and the need to protect property and critical infrastructure, are expected to support continued growth of the fire suppression systems segment.
Service Insights
The installation and design services segment accounted for the largest share of 40.8% of the global fire protection system market in 2025, supported by the increasing deployment of fire protection solutions across residential, commercial, industrial, and institutional buildings. These services encompass the design, development, documentation, installation, and upgrading of fire protection systems, often provided by specialized vendors with extensive technical expertise. As building owners and occupants become more aware of the importance of comprehensive fire safety, demand for professionally designed and installed systems is increasing across small, medium-sized, and large facilities. The specialized knowledge and compliance expertise offered by service providers further support the adoption of installation and design services.
The maintenance services segment is projected to register the fastest CAGR of 6.5% from 2026 to 2033. Regular maintenance is essential to ensure that fire protection systems operate reliably during emergencies and to minimize the risk of system failures, property damage, and loss of life. Maintenance services typically include periodic inspections, testing, audits, repairs, and servicing of fire protection equipment to ensure compliance with applicable fire safety standards and regulations. The growing installed base of fire protection systems and increasing emphasis on operational reliability are expected to further drive demand for maintenance services over the forecast period.
Application Insights
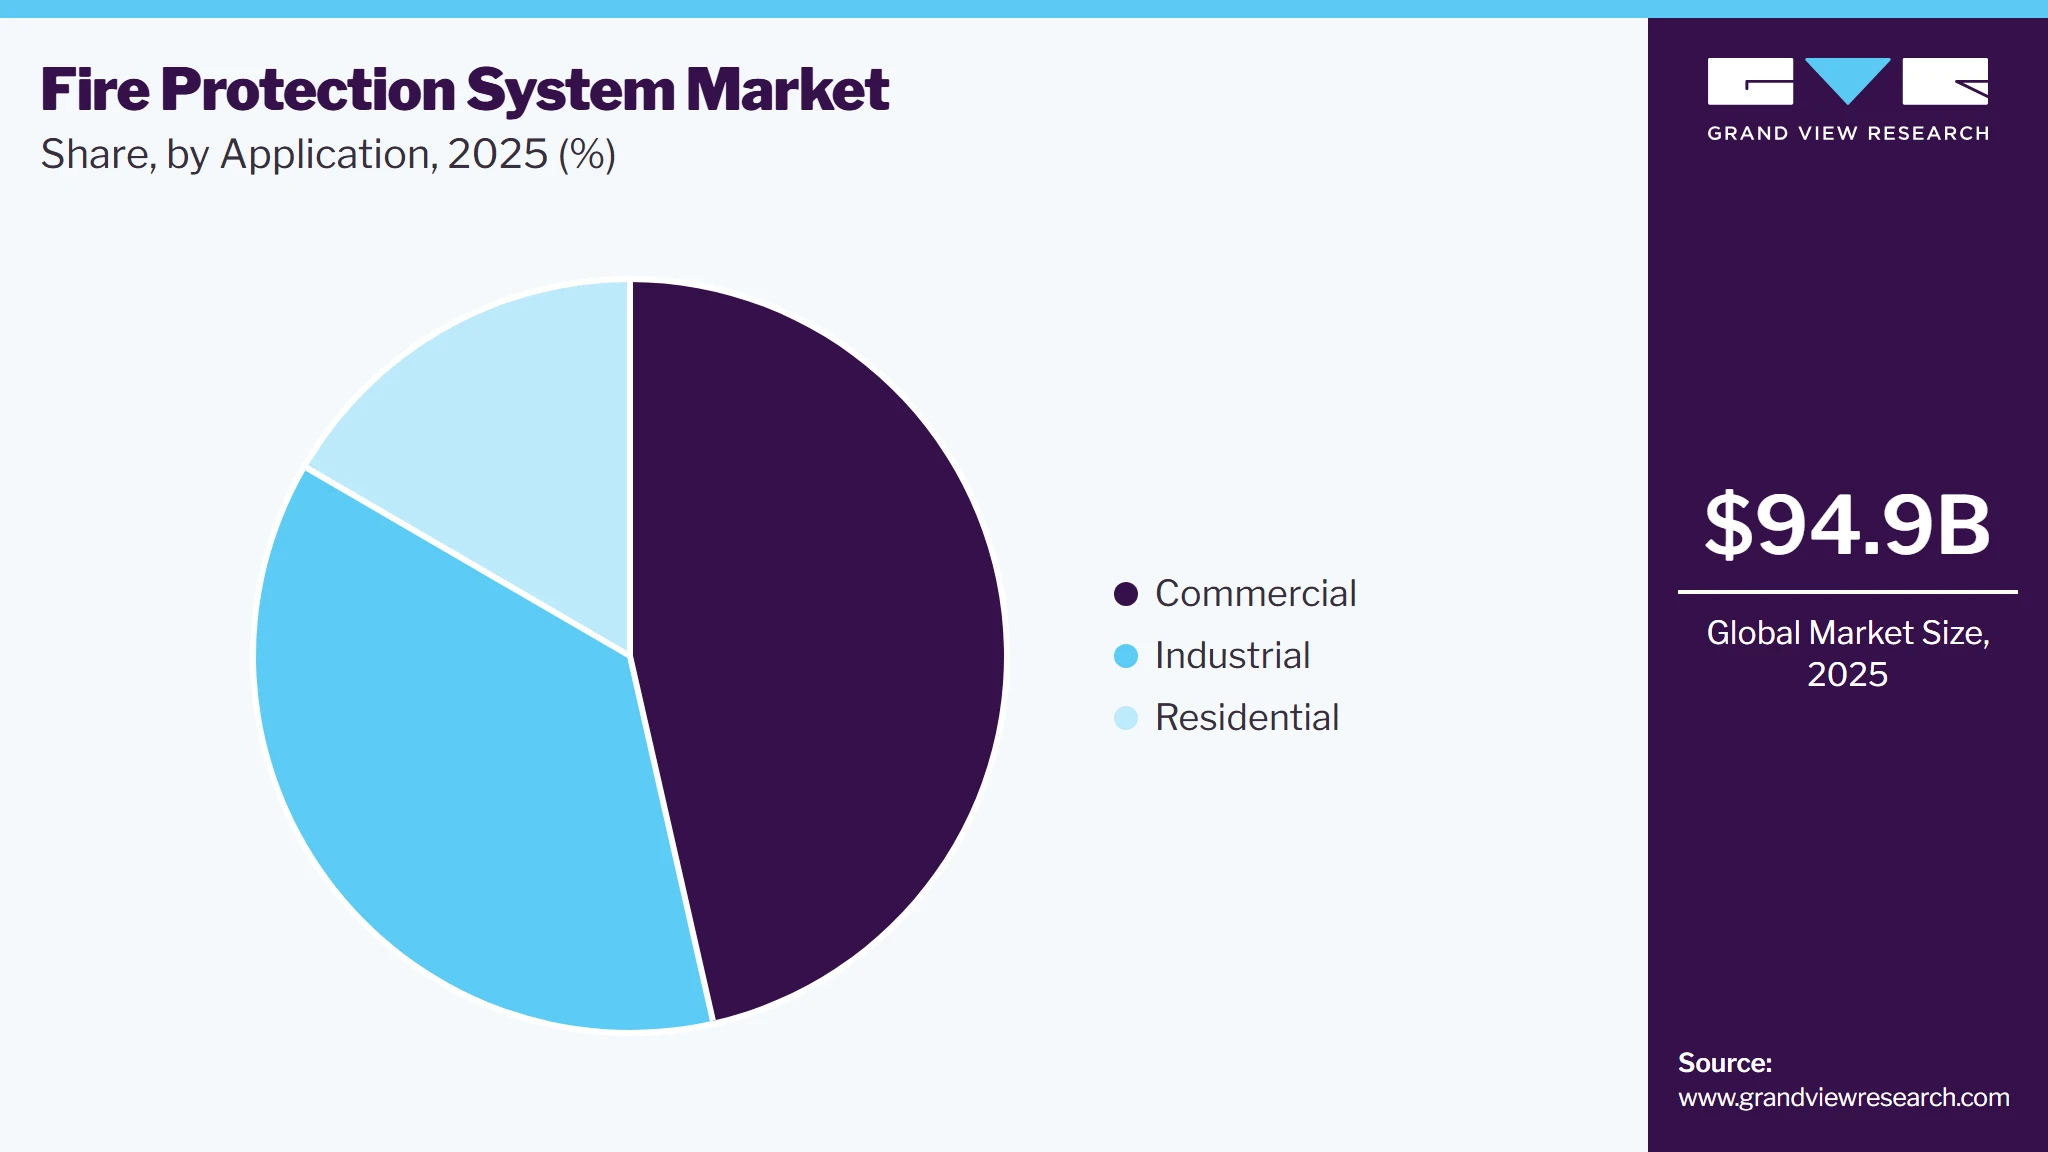
The commercial application segment accounted for the largest revenue share of 46.4% in the fire protection system market in 2025, driven by increasing adoption across retail, BFSI, government, healthcare, telecom and IT, and educational institutions. The implementation of stringent fire prevention and safety regulations worldwide is encouraging commercial establishments to deploy comprehensive fire protection solutions. In addition, growing investments by businesses to protect people, property, and critical infrastructure from fire-related risks are further supporting demand for fire detection, suppression, alarm, and other safety systems across commercial facilities.
 To learn more about this report, Download Free Sample Report
The industrial application segment is expected to register the fastest CAGR of 7.5% from 2026 to 2033, supported by increasing demand for fire protection solutions across oil and gas, mining, energy and power, and manufacturing industries. These sectors often involve highly automated systems, hazardous materials, and complex operating environments, increasing the need for reliable fire prevention and protection measures. The growing emphasis on protecting industrial assets, production infrastructure, and automated equipment from fire-related incidents, coupled with stringent government safety regulations, is expected to further drive the adoption of comprehensive fire protection systems across industrial facilities.
Regional Insights
The North America fire protection system market accounted for the largest revenue share of 34.9% in 2025, supported by increasing adoption of smart homes and intelligent buildings designed to enhance occupant safety and security. The region also has a strong presence of established fire protection and building technology companies, including Raytheon Technologies Corporation, GENTEX Corporation, and Honeywell International Inc. The U.S. fire protection system market is expected to grow significantly from 2026 to 2033, driven by stringent fire safety regulations established by organizations such as the National Fire Protection Association (NFPA) and by requirements in local building codes. Increasing investment in commercial buildings, industrial facilities, healthcare infrastructure, and data centers is driving demand for advanced fire detection, alarm, and suppression systems. In addition, the rising incidence of wildfires and climate-related fire risks is encouraging property owners and facility operators to strengthen fire protection measures. The growing adoption of smart building technologies and IoT-enabled fire protection solutions is further accelerating system upgrades across both new and existing facilities, supporting continued market expansion.
 To learn more about this report, Download Free Sample Report
Europe Fire Protection System Market Trends
The Europe fire protection system market is expected to witness significant growth of 7.0% from 2026 to 2033, driven by stringent fire safety standards, increasing renovation and modernization activities, and rising investments in sustainable building infrastructure. Governments across the region are strengthening fire safety requirements to enhance occupant protection and ensure compliance with evolving regulations. The modernization of aging commercial and industrial facilities is generating demand for advanced fire detection, alarm, and suppression technologies. In addition, the growing adoption of smart buildings and integrated building management systems is accelerating the deployment of intelligent fire protection solutions that improve monitoring, response, and overall safety. The UK fire protection system market is projected to grow significantly during the forecast period, supported by increasing emphasis on building safety and fire risk management following major regulatory reforms. Stricter requirements for fire detection, alarm systems, and passive fire protection measures are encouraging investments across residential and commercial properties. Furthermore, the development of high-rise buildings and public infrastructure is creating additional demand for comprehensive fire safety solutions.
Asia Pacific Fire Protection System Market Trends
The Asia Pacific fire protection system market is expected to register the fastest growth of 9.3% from 2026 to 2033, supported by increasing investments in fire safety across manufacturing facilities, automotive plants, logistics centers, and chemical processing sites. In addition, the growing adoption of Industry 4.0 technologies is driving demand for integrated and automated fire protection solutions that enable real-time monitoring, faster response, and improved safety management. The China fire protection system market accounted for a substantial share in 2025, supported by rapid urbanization, expanding construction activities, and increasing investments in commercial and industrial infrastructure. Government initiatives aimed at strengthening fire safety and public protection standards are encouraging the deployment of advanced fire protection systems across residential complexes, manufacturing facilities, transportation hubs, and public buildings. Furthermore, the rapid expansion of data centers, electronics manufacturing, and smart city projects is generating additional demand for intelligent fire detection, monitoring, and suppression solutions, supporting continued market growth in China.
Key Fire Protection System Company Insights
Major players are adopting strategic initiatives and undertaking measures to gain benefits from the opportunities in the emerging market. The key companies in the market have launched new advanced products to meet the evolving customer needs. For instance, in March 2026, Siemens launched its next-gen fire safety protection as part of their autonomous building systems. The new Sinteso Nova and Cerberus Nova fire detector portfolio offers enhanced operational safety, streamlines service team efficiency, and ease of system upgrades with cloud-connectivity.
-
Johnson Controls has established itself as a leading player in the fire protection system market through its comprehensive portfolio of fire detection, alarm, suppression, and integrated building safety solutions. The company leverages its expertise in smart buildings and connected infrastructure to deliver advanced fire protection systems across commercial, industrial, healthcare, education, and critical infrastructure sectors. Johnson Controls continues to invest in digital fire safety technologies, cloud-based monitoring platforms, and integrated building management systems to enhance real-time threat detection, operational efficiency, and regulatory compliance. The company's strong focus on intelligent building ecosystems, lifecycle service offerings, and sustainable infrastructure solutions has further strengthened its position in the global fire protection market.
-
Honeywell International is a prominent participant in the fire protection system industry, offering a wide range of fire detection, alarm, emergency communication, and life-safety solutions for residential, commercial, and industrial applications. The company is focused on advancing connected fire safety technologies through the integration of IoT, cloud connectivity, artificial intelligence, and building automation platforms. Honeywell continues to expand its portfolio of intelligent fire protection solutions designed to improve situational awareness, accelerate emergency response, and support compliance with evolving fire safety regulations. Its emphasis on digital transformation, smart building integration, predictive maintenance capabilities, and global service networks has enabled the company to strengthen customer engagement and maintain a competitive position in the rapidly evolving fire protection industry.
Key Fire Protection System Companies
The following are the leading companies in the fire protection systems market. These companies collectively hold the largest market share and dictate industry trends.
Recent Developments
-
In January 2026, Halma plc acquired Safetec srl, an Italy-based provider of integrated fire and gas safety systems for industrial markets. Safetec srl specializes in customized fire detection and hazard monitoring solutions for high-risk environments, such as oil & gas and manufacturing. The acquisition strengthens Halma plc industrial fire protection capabilities and expands its portfolio of integrated safety systems.
-
In July 2025, Honeywell International, Inc. acquired Li-ion Tamer, an early detection technology that identifies lithium-ion battery thermal runaway risks before a fire starts. The solution strengthens the company's fire life-safety portfolio, particularly for data centers, energy storage, and EV infrastructure. The acquisition enhances the company's position in advanced fire detection and battery fire prevention systems.
Fire Protection System Market Report Scope
Report Attribute
Details
Market size in 2025
USD 94.9 billion
Estimated Market size value in 2026
USD 101.2 billion
Revenue forecast in 2033
USD 156.2 billion
Growth Rate
CAGR of 6.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market position analysis, competitive landscape, growth factors, and trends
Segments covered
Component, application, region
Regional Scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country Scope
U.S.; Canada; Mexico; Germany; UK; France; China; India; Japan; South Korea; Australia; Brazil; Kingdom of Saudi Arabia (KSA); UAE; South Africa
Key companies profiled
Johnson Controls; Honeywell International, Inc.; Raytheon Technologies Corporation; GENTEX CORPORATION; Siemens; Robert Bosch GmbH; Halma plc; Eaton; Napco Security Technologies; Hitachi Ltd.
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Fire Protection System Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global fire protection system market report based on component, application, and region:
-
Component Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Product
-
Fire Detection
-
Fire Suppression
-
Fire Response
-
Fire Analysis
-
Fire Sprinkler System
-
-
Services
-
Managed Service
-
Installation and Design Service
-
Maintenance Service
-
Others
-
-
-
Application Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Commercial
-
Industrial
-
Residential
-
-
Regional Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Scope & Research Methodology
The market study on the fire protection systems market has been developed using a structured, multi-stage research framework designed to ensure accuracy, consistency, and reliability of the market size estimates and forecasts. The methodology combines quantitative modeling techniques with qualitative validation, following the sequence outlined below.
The fire protection systems market is segmented into three levels, namely component, application, and regions. In the first level, the market has been split, by component, as follows:
- Products: This segment includes revenue generated from the sale of physical fire protection equipment and systems designed to detect, suppress, monitor, and respond to fire incidents. It encompasses hardware components, including fire alarms, smoke detectors, fire suppression systems, sprinkler systems, control panels, emergency communication devices, and fire monitoring solutions, deployed across residential, commercial, and industrial facilities.
- Fire Detection: This segment includes fire detection solutions designed to identify the presence of smoke, heat, flames, or combustible gases and provide early warning of fire incidents. Revenue is generated from products such as smoke detectors, heat detectors, flame detectors, fire alarm panels, sensors, and associated monitoring devices.
- Fire Suppression: This segment includes systems and equipment designed to control, contain, or extinguish fires automatically or manually. Revenue is generated from fire extinguishers, gaseous suppression systems, foam suppression systems, water mist systems, chemical suppression systems, and related control equipment.
- Fire Response: This segment includes products that facilitate emergency response and occupant safety during fire incidents. Revenue is generated from emergency communication systems, voice evacuation systems, public address systems, firefighter communication equipment, emergency lighting, and incident management solutions.
- Fire Analysis: This segment includes technologies used for fire monitoring, analytics, risk assessment, and incident intelligence. Revenue is generated from fire monitoring software, analytics platforms, cloud-based fire management systems, predictive maintenance solutions, AI-enabled fire risk assessment tools, and integrated fire safety management applications.
- Fire Sprinkler System: This segment includes automatic sprinkler systems designed to detect and suppress fires through water discharge mechanisms. Revenue is generated from sprinkler heads, piping networks, valves, pumps, control assemblies, pre-action systems, deluge systems, and associated sprinkler infrastructure components.
- Services: This segment includes revenue generated from professional and managed services associated with fire protection systems, including system design, engineering, installation, testing, inspection, monitoring, maintenance, repair, upgrades, and compliance-related support services throughout the system lifecycle
- Managed Services: This segment includes outsourced fire protection system management services such as remote monitoring, centralized alarm management, compliance reporting, system performance monitoring, predictive maintenance, and cloud-based fire safety management services provided under recurring service contracts.
- Installation and Design Services: This segment includes consulting, engineering, system design, integration, deployment, commissioning, and project implementation services associated with the installation of fire protection systems in new and existing facilities.
- Maintenance Services: This segment includes periodic inspection, testing, certification, preventive maintenance, repair, replacement, calibration, and upgrade services required to maintain system functionality, regulatory compliance, and operational readiness.
- Others: This segment includes additional professional services such as fire risk assessments, fire safety audits, employee training, emergency preparedness consulting, code compliance advisory services, and retrofit project support.
Based on region, the market has been segmented into North America, Europe, Asia Pacific, Latin America, and Middle East & Africa:
• North America: The North America regional market includes the markets of the U.S., Canada, and Mexico.
• Europe: The Europe regional market includes the markets of the U.K., Germany, and France.
• Asia Pacific: The Asia Pacific regional market includes the markets of China, India, Japan, Australia and South Korea.
• Latin America: The Latin America market includes the markets of Brazil.
• Middle East & Africa: The MEA regional market includes the markets of UAE, Saudi Arabia and South Africa
Estimation Model
Layer Name
Key Question
Description
Building & Infrastructure Base Layer
What creates demand for fire protection systems?
Global installed base and annual construction of commercial buildings, industrial facilities, manufacturing plants, data centers, healthcare facilities, educational institutions, residential buildings, transportation infrastructure, energy facilities, warehouses, and other structures requiring fire safety compliance and protection.
Fire Safety Equipment Layer
How many fire protection systems can be deployed?
Assessment of fire protection equipment requirements across buildings and facilities, including fire detection systems, fire suppression systems, sprinkler systems, fire alarms, extinguishers, hydrants, emergency communication systems, and specialized fire protection solutions. Evaluation based on building size, occupancy levels, fire risk classification, asset value, and regulatory requirements.
Fire Safety Compliance & Adoption Intensity Layer
How rapidly are fire protection systems being adopted?
Adoption is driven by stringent fire safety regulations, building codes, insurance requirements, industrial safety standards, urbanization, infrastructure development, increasing awareness of fire risks, asset protection needs, and modernization of existing fire safety systems. Includes retrofitting activities and investments in smart fire protection technologies.
Revenue Layer
How is revenue captured?
Revenue is generated from the sale, installation, integration, inspection, testing, monitoring, and maintenance of fire protection systems across product types, technologies, applications, and end-user industries. Includes revenues from fire detection equipment, fire suppression systems, sprinkler networks, fire alarm systems, software platforms, monitoring services, maintenance contracts, and recurring inspection and compliance services.
Delivered Customizations
Client Request
Customization Delivered
Value Adds
Fire Protection System Market Opportunity Assessment
- Country/region-wise fire protection system market sizing and growth forecasts across North America, Europe, Asia Pacific, and the Rest of the World.
- Assessment of fire safety regulations, building codes, industrial safety standards, and compliance requirements influencing fire protection system deployment across key markets.
- Identified region-specific growth opportunities driven by infrastructure development, industrial expansion, urbanization, and increasing fire safety compliance requirements.
- Supported market expansion strategies, product portfolio planning, and investment prioritization.
Competitive Benchmarking and Strategic Positioning in the Fire Protection System Market
- Benchmarking of leading vendors across pricing strategies, product portfolios, managed services, installation capabilities, maintenance offerings, and digital fire safety technologies.
- Comparative assessment of market share, operational capabilities, and growth strategies.
- Identified market gaps across integrated building safety systems, predictive maintenance solutions, wireless fire protection technologies, and lifecycle service offerings.
- Supported strategic expansion, mergers & acquisitions planning, and ecosystem partnership development.
Application-Level Growth Opportunity Assessment
- Detailed assessment of fire protection system adoption across commercial, industrial, and residential applications.
- Analysis of demand trends across data centers, healthcare facilities, manufacturing plants, warehouses, transportation infrastructure, and smart buildings.
- Identified high-growth application segments and emerging investment opportunities.
- Supported customer targeting strategies, vertical expansion planning, and resource allocation decisions.
Frequently Asked Questions About This Report
The global fire protection system market size was estimated at USD 94.9 billion in 2025 and is expected to reach USD 101.2 billion in 2026.
The global fire protection system market is expected to grow at a compound annual growth rate of 6.4% from 2026 to 2033 to reach USD 156.2 billion by 2033.
Some key players operating in the fire protection system market include Johnson Controls; Honeywell International, Inc.; GENTEX CORPORATION; Siemens; Robert Bosch GmbH; Halmaplc; Eaton; and Raytheon Technologies Corporation.
Key factors that are driving the fire protection system market growth include growth in the adoption of wireless technology in fire detection systems and the development of the construction industry across the world.
North America dominated the fire protection system market with a share of over 34.9% in 2025. This is attributable to the implementation of stringent fire safety regulations and norms and rapid infrastructural developments.
Fire detection systems segment dominated the fire protection system market with a share of over 58.1% in 2025.
Commercial segment dominated the fire protection system market with a share of over 46.4% in 2025.
The Asia Pacific region witnessed for high CAGR in the global fire protection system market. This is due to Rapid urbanization, strict government safety mandates, and massive commercial construction expansions across developing nations.
The UK witnessed for high CAGR in the Europe fire protection system market. This is due to strict regulatory mandates, a surge in high-density urban developments, and localized infrastructure investments across major commercial and healthcare hubs.
Fire Protection System Market By Country
- U.S. Fire Protection System Market
- Canada Fire Protection System Market
- Mexico - North America Fire Protection System Market
- Germany Fire Protection System Market
- France Fire Protection System Market
- Italy Fire Protection System Market
- Spain Fire Protection System Market
- Denmark Fire Protection System Market
- Sweden Fire Protection System Market
- Finland Fire Protection System Market
- Norway Fire Protection System Market
- Japan Fire Protection System Market
- China Fire Protection System Market
- India Fire Protection System Market
- Australia Fire Protection System Market
- South Korea Fire Protection System Market
- Argentina Fire Protection System Market
- Brazil Fire Protection System Market
- South Africa Fire Protection System Market
- Saudi Arabia Fire Protection System Market
- Uae Fire Protection System Market
- U.K. Fire Protection System Market
- Poland Fire Protection System Market
About the Author(s)
HVAC & Construction Research Team
Technology · HVAC & ConstructionThis report was authored by the hvac & construction research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the hvac & construction segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


