
- Home
- »
- Next Generation Technologies
- »
-
Smart Agriculture Market Size Report, 2025-2033GVR Report cover
![Smart Agriculture Market Size, Share & Trends Report]()
Smart Agriculture Market (2025 - 2033) Size, Share & Trends Analysis Report By Offering (Hardware, Software, Services), By Application (Precision Farming, Livestock Monitoring, Smart Greenhouse), By Region, And Segment Forecasts
Market Size, 2024
$25.4BMarket Estimate, 2026
$32.2BMarket Forecast, 2033
$83.7BCAGR, 2025–2033
14.6%Smart Agriculture Market Summary
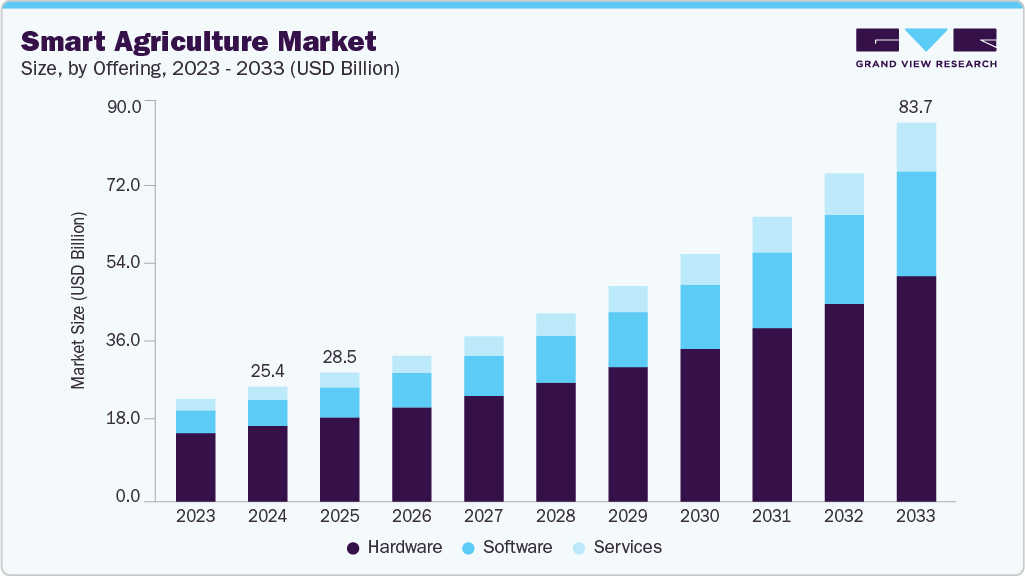
The global smart agriculture market size was valued at USD 25.4 billion in 2024 and is projected to grow from USD 32.2 billion in 2026 to USD 83.7 billion by 2033, at a CAGR of 14.6% from 2025 to 2033. North America dominated the market, accounting for a revenue share of 43.5% in 2024. Increasing automation of commercial greenhouses and growing implementation of the controlled environment agriculture (CEA) are the key factors driving demand during the forecast period.

Key Market Trends & Insights
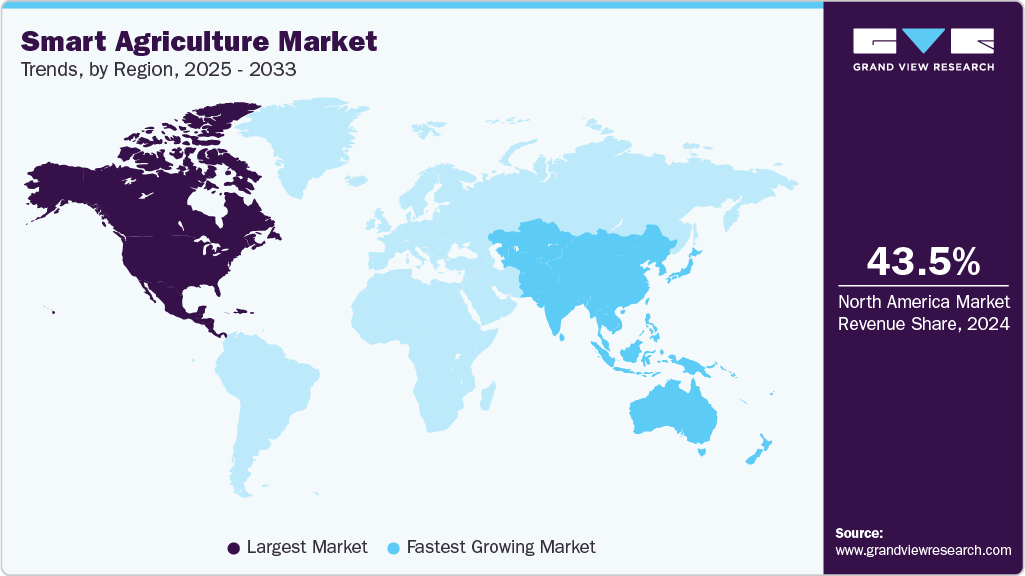
- North America dominated the global smart agriculture market with the largest revenue share of 43.5% in 2024.
- The smart agriculture industry in the U.S. accounted for the largest market revenue share in North America in 2024.
- By offering, the hardware segment led the market with the largest revenue share of 66.1% in 2024.
- By application, the precision farming segment accounted for the largest market revenue share in 2024.
Market Size & Forecast
- 2024 Market Size: USD 25.4 Billion
- 2033 Projected Market Size: USD 83.7 Billion
- CAGR (2025-2033): 14.6%
- North America: Largest market in 2024
- Asia Pacific: Fastest growing market
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2025–2033 annual, 2024 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Smart agriculture companies are shifting their focus toward the development of equipment that is integrated with advanced sensors and cameras. Key technologies driving the market demand include livestock biometrics, such as RFID, biometrics, and GPS, to help cultivators automatically obtain information regarding livestock in real-time. Furthermore, infrastructural health sensors are used to monitor material conditions and vibrations in buildings, factories, bridges, farms, and other types of infrastructure. Coupled with an intelligent network, infrastructural health sensors help provide real-time information to the maintenance team. In addition, agricultural robots are being used to automate various farming processes, including soil maintenance, weeding, fruit picking, harvesting, planting, plowing, and irrigation, among others.To sustain profits, farmers are increasingly adopting smarter and more efficient agriculture technologies to deliver high-quality products to the smart agriculture industry in sufficient quantities. Mobile technology enables the development of innovative types and applications that are utilized throughout the entire agricultural value chain.
Machine-to-machine (M2M) applications are particularly well-suited for the agricultural sector, enabling farmers to monitor equipment, assess the environmental impact on production, precisely manage livestock and crops, and track tractors and other agricultural equipment. M2M is an integral part of IoT, which describes the coordination of multiple devices, appliances, and machines connected to the internet through multiple networks.
Offering Insights
The hardware segment led the market with the largest revenue share of 66.1% in 2024. The hardware segment has further been bifurcated into automation & control systems, HVAC systems, LED grow lights, RFID tags & readers, and sensing devices. Automation & control systems are further segmented into application control devices, milking robots, guidance systems, driverless tractors, mobile devices, remote sensing, variable rate technology, agricultural drones, and wireless modules.
The growing automation of raw material production and product manufacturing in the dairy and food industry is likely to drive the milking robots segment in the future. Automation technology has improved milk quality and animal welfare. The rising need to reduce labor costs and improve productivity is expected to positively impact the profitability of the dairy & food processing industries. Factors such as increased milk frequency, efficient management of the herd, cow health, and welfare benefits are driving the demand for milking robots.
The drones sub-segment under the automation & control system is expected to witness at the fastest growth during the forecast period. Several types of drones include hybrid and fixed-wing. Fixed-wing drones feature a rigid wing with a predetermined airfoil, which aids in flight by generating lift due to the drone’s forward airspeed. Forward thrust acquired by a propeller, an electric motor, or an internal combustion engine produces this airspeed.
Rotary blade drones comprise single-rotor and multi-rotor type drones that revolve around a fixed mast, which enables them to fly in any direction and hover in one place. Hybrid drones can stay in flight for years at a stretch as they operate on multiple sources of energy. Solar panels mounted on the wings of the hybrid drones provide fuel during the flight.
The software segment is anticipated to grow at the fastest CAGR during the forecast period. The proliferation of smartphones and IoT-connected devices in rural areas has expanded the accessibility and functionality of agriculture software. With mobile apps and user-friendly interfaces, even smallholder farmers are beginning to adopt digital solutions to manage their fields, access market prices, and receive alerts on pest outbreaks or adverse weather conditions. The increasing digital literacy among farmers and the widespread penetration of internet services are important enablers for the rapid adoption of the software segment in developing regions.
Application Insights
The precision farming segment accounted for the largest market revenue share in 2024. The increasing use of drones and unmanned aerial vehicles (UAVs) in agricultural monitoring is significantly contributing to the adoption of precision farming. Drones equipped with multispectral imaging and mapping capabilities offer detailed views of crop health and field variability, enabling farmers to detect issues early and optimize interventions. As drone technology becomes more affordable and regulations around its usage become more farmer-friendly, its integration into precision farming workflows is becoming commonplace, adding a new dimension to data-driven agriculture.
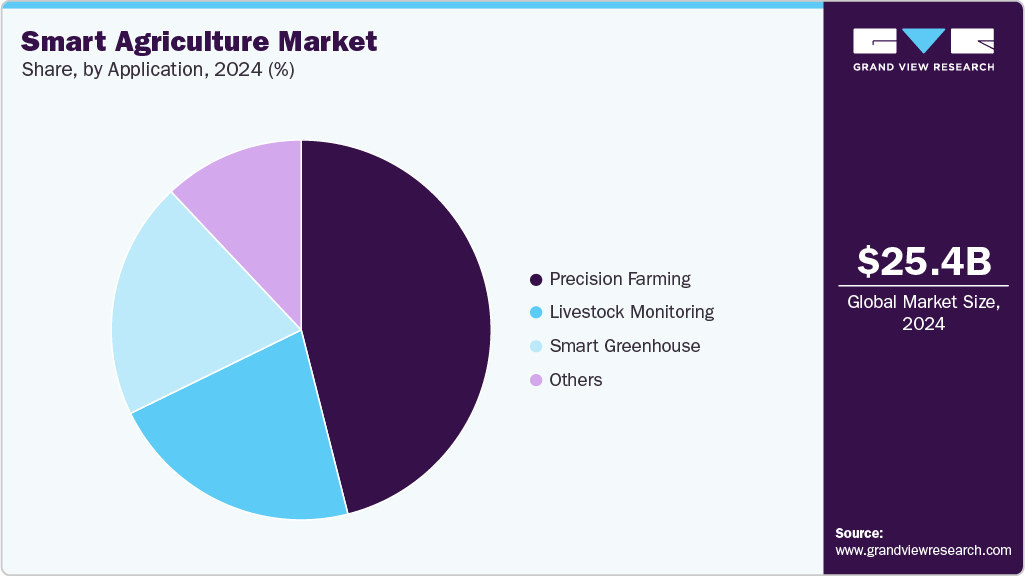
The smart greenhouse segment is anticipated to grow at the fastest CAGR during the forecast period. The growing focus on urban agriculture and local food production is also driving the expansion of smart greenhouses. As urban populations expand and the distance between production and consumption centers grows, smart greenhouses are being adopted in urban and peri-urban areas to meet local food demands. These systems are well-suited for integration into urban environments due to their compact footprint and ability to produce fresh crops close to consumers, reducing transportation costs and emissions.
Regional Insights
North America dominated the global smart agriculture market with the largest revenue share of 43.5% in 2024. The region is an early adopter of technologies. Growing government initiatives and regulations to enhance the agriculture industry in the region are expected to drive the North American regional demand during the forecast period. Various agricultural organizations have come together to form the North America Climate Smart Agriculture Alliance (NACSAA), a platform for educating and equipping the cultivators for sustainable agricultural productivity. With the growing concern for water conservation, governments in North America are actively providing subsidies to promote the adoption of smart irrigation systems. For instance, the California government has provided a rebate on smart controllers.
U.S. Smart Agriculture Market Trends
The smart agriculture market in the U.S. accounted for the largest market revenue share in North America in 2024. The rising popularity of vertical farming, smart greenhouses, and indoor agriculture in urban areas of the U.S. is opening new avenues for smart agriculture technologies. These methods rely heavily on automation, IoT, and AI to control growing environments and maximize output within limited spaces, making them ideal for metropolitan regions. The integration of smart systems in these innovative agricultural models is expanding the scope of the U.S. smart agriculture industry beyond traditional farms.
Europe Smart Agriculture Market Trends
The smart agriculture market in the Europe is expected to grow at a significant CAGR during the forecast period. Europe’s highly developed digital infrastructure and widespread access to broadband internet in rural areas provide a strong foundation for the deployment of connected agricultural technologies. The availability of high-speed connectivity enables real-time monitoring of fields, machinery, and livestock, making it easier for farmers to leverage IoT, AI, and big data analytics for informed decision-making. This digital readiness supports the expansion of precision farming, smart irrigation systems, and autonomous machinery throughout the continent.
The Germany smart agriculture market is expected to account for a significant revenue share in the European market in 2024. Germany’s robust R&D ecosystem is another key driver of the smart agriculture industry. The country hosts numerous agricultural research institutions, agri-tech startups, and collaborations between academia and the private sector. Initiatives such as Smart Agriculture Made in Germany promote the development and export of innovative farming technologies, while substantial government and EU funding support experimentation and scalability of digital solutions in agriculture.
Asia Pacific Smart Agriculture Market Trends
The smart agriculture market in Asia Pacific is expected to witness at the fastest CAGR over the forecasted period. Government initiatives and policy support are also major catalysts for growth. Programs such as India's Digital Agriculture Mission, China's Smart Agriculture Development Plan, and Japan’s Society 5.0 vision are driving the integration of AI, robotics, and big data into farming practices. These policies not only encourage technology adoption but also offer subsidies, training programs, and infrastructure development to support digitized farming ecosystems.
China's smart agriculture market held a significant revenue share in Asia Pacific in 2024. The country’s expanding e-commerce and agri-food export sectors are pushing the need for enhanced traceability and quality control. Smart agriculture technologies enable the monitoring and documentation of every stage of the crop lifecycle, from seed to shelf. This traceability is becoming a key value differentiator in domestic and global markets, especially in the context of food safety regulations and consumer demand for transparency.
Key Smart Agriculture Company Insights
Some of the key players operating in the market include Trimble, Inc., AGCO Corporation, and Deere & Company, among others, which are among the leading participants in the smart agriculture industry.
-
AGCO Corporation is a U.S.-based agriculture equipment manufacturer. The company develops and sells a range of products and solutions, including tractors, combines, foragers, hay tools, self-propelled sprayers, smart farming technologies, seeding equipment, and tillage equipment.
-
Deere & Company is engaged in the manufacturing & construction of agricultural and forestry machinery, drivetrains, and diesel engines for heavy equipment, and lawn care machinery. In addition, the Company manufactures and supplies other heavy-duty manufacturing equipment. The company serves diverse industries, including agriculture, forestry, construction, landscaping & grounds care, engines & drivetrain, government and military, and sports turf.
Prospera Technologies and Agrible, Inc. are some of the emerging market participants in the smart agriculture industry.
-
Prospera Technologies is a global service provider of agriculture technology for managing and optimizing irrigation and crop health. The company provides AI-based sensors and cameras that aid farmers in crop monitoring.
-
Agrible is a U.S.-based agriculture solution provider. The company helps customers in more than 30 countries optimize water use, crop protection, fertilization, fieldwork, research trials, food supply chains, and sustainability initiatives.
Key Smart Agriculture Companies:
The following are the leading companies in the smart agriculture market. These companies collectively hold the largest Market share and dictate industry trends.
- Ag Leader Technology
- AGCO Corporation
- Kubota Corporation.
- AgEagle Aerial Systems Inc.
- Autonomous Solutions, Inc.
- Argus Control Systems Ltd
- BouMatic Robotic B.V.
- CropMetrics
- CLAAS KGaA mbH
- CropZilla
- Deere & Company
- DICKEY-john
- DroneDeploy
- DeLaval Inc
- Farmers Edge Inc
- Grownetics, Inc.
- Corteva Agriscience.
- Gamaya
- GEA Group Aktiengesellschaft
- Raven Industries
- Trimble Inc.
- Topcon Positioning System
Recent Developments
-
In July 2026, CLAAS expanded its CLAAS connect digital platform with automated data exchange between farms and contractors, brand-independent mixed-fleet tracking, data-driven operational reports, and remote machine-support capabilities. The enhanced platform is designed to improve connectivity, fleet visibility, data management, and operational efficiency across agricultural workflows
-
In April 2025, Farmers Edge Inc. partnered with Taurus Ag Marketing Inc. to expand access to high-quality soil testing solutions across Canada. Taurus will improve the availability of advanced lab services, delivering industry-leading turnaround times and tailored insights to support data-driven decisions for growers, agronomists, and agri-businesses.
-
In July 2023, Deere & Company announced the acquisition of Smart Apply, Inc. The company planned to leverage Smart Apply’s precision spraying to assist growers in addressing the challenges associated with input costs, labor, regulatory requirements, and environmental goals.
-
In May 2023, AgEagle Aerial Systems Inc. announced that it had entered into a 2-year supply agreement with Wingtra AG. This agreement is intended to secure the supply of RedEdge-P sensor kits for incorporation with WingtraOne VTOL drones. This is particularly beneficial for those seeking to derive tangible benefits from unparalleled, high precision, and plant-level detail in commercial agriculture, environmental research, forestry, and water management applications.
-
In April 2023, AGCO Corporation announced a strategic collaboration with Hexagon for the expansion of AGCO’s factory-fit and aftermarket guidance offerings. The new guidance system was planned to be commercialized as Fuse Guide on Valtra and Massey Ferguson tractors.
-
In February 2023, Topcon Agriculture unveiled the launch of Transplanting Control, an exceptional guidance control solution for specialty farmers. This turnkey solution was designed to boost efficiency, reduce labor, and increase production. Further, it delivers GNSS-driven guidance, autosteering & control, thereby proving advantageous for the growers of perennial trees, vegetables, and fruits.
-
In January 2023, ASI Logistics, in collaboration with SICK, Inc., announced the successful implementation of autonomous yard truck operations. In this collaboration, ASI Logistics leveraged its groundbreaking Vehicle Automation Kit (VAK) along with the industry-leading LiDAR systems of SICK.
Smart Agriculture Market Report Scope
Report Attribute
Details
Market size in 2024
USD 25.4 billion
Estimated market size in 2026
USD 32.2 billion
Projected market size by 2033
USD 83.7 billion
Growth rate
CAGR of 14.6% from 2025 to 2033
Base year for estimation
2024
Historical data
2021 - 2023
Forecast period
2025 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2025 to 2033
Report coverage
Revenue forecast, company share, competitive landscape, growth factors, and trends
Segments covered
Offering, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico UK; Germany; France; Netherlands; Russia; China; India; Japan; Australia; Singapore; Brazil; Turkey
Key companies profiled
Ag Leader Technology; AGCO Corporation; Kubota Corporation.; AgEagle Aerial Systems Inc.; Autonomous Solutions, Inc.; Argus Control Systems Ltd; BouMatic Robotic B.V.; CropMetrics; CLAAS KGaA mbH; CropZilla; Deere & Company; DICKEY-john; DroneDeploy; DeLaval Inc; Farmers Edge Inc.; Grownetics, Inc.; Corteva Agriscience.; Gamaya; GEA Group Aktiengesellschaft; Raven Industries; Trimble Inc.; Topcon Positioning System
Customization scope
Free report customization (equivalent to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Smart Agriculture Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global smart agriculture market report based on offering, application, and region.
Global Smart Agriculture Market Report - Table of Contents
Chapter 1. Methodology and Scope
1.1. Market Segmentation and Scope
1.2. Research Methodology
1.2.1. Information Procurement
1.3. Information or Data Analysis
1.4. Methodology
1.5. Research Scope and Assumptions
1.6. Market Formulation & Validation
1.7. Country Based Segment Share Calculation
1.8. List of Data Sources
Chapter 2. Executive Summary
2.1. Market Outlook
2.2. Segment Outlook
2.3. Competitive Insights
Chapter 3. Smart Agriculture Market Variables, Trends, & Scope
3.1. Market Lineage Outlook
3.2. Market Dynamics
3.2.1. Market Driver Analysis
3.2.2. Market Restraint Analysis
3.2.3. Industry Challenge
3.3. Smart Agriculture Market Analysis Tools
3.3.1. Industry Analysis - Porter’s
3.3.1.1. Bargaining power of the suppliers
3.3.1.2. Bargaining power of the buyers
3.3.1.3. Threats of substitution
3.3.1.4. Threats from new entrants
3.3.1.5. Competitive rivalry
3.3.2. PESTEL Analysis
3.3.2.1. Political landscape
3.3.2.2. Economic landscape
3.3.2.3. Social landscape
3.3.2.4. Technological landscape
3.3.2.5. Environmental landscape
3.3.2.6. Legal landscape
Chapter 4. Smart Agriculture Market Offering Outlook
4.1. Smart Agriculture Market, By Offering Analysis & Market Share, 2025 & 2033
4.2. Hardware
4.2.1. Hardware market estimates and forecasts, 2021 - 2033 (USD Million)
4.2.2. Automation & Control Systems
4.2.2.1. Automation & control systems market estimates and forecasts, 2021 - 2033 (USD Million)
4.2.2.1.1. Drones
4.2.2.1.2. Application Control Devices
4.2.2.1.3. Guidance System
4.2.2.1.3.1. GPS
4.2.2.1.3.2. GIS
4.2.2.1.4. Remote Sensing
4.2.2.1.4.1. Handheld
4.2.2.1.4.2. Satellite Sensing
4.2.2.1.5. Driverless Tractors
4.2.2.1.6. Mobile Devices
4.2.2.1.7. VRT
4.2.2.1.7.1. Map-based
4.2.2.1.7.2. Sensor-based
4.2.2.1.8. Wireless Modules
4.2.2.1.8.1. Bluetooth Technology
4.2.2.1.8.2. Wi-Fi Technology
4.2.2.1.8.3. Zigbee Technology
4.2.2.1.8.4. RF Technology
4.2.2.1.9. Milking Robots
4.2.3. Sensing Devices
4.2.3.1. Sensing devices market estimates and forecasts, 2021 - 2033 (USD Million)
4.2.3.1.1. Soil Sensor
4.2.3.1.1.1. Nutrient Sensor
4.2.3.1.1.2. Moisture Sensor
4.2.3.1.1.3. Temperature Sensor
4.2.3.1.2. Water Sensors
4.2.3.1.3. Climate Sensors
4.2.3.1.4. Others
4.2.4. HVAC System
4.2.4.1. HVAC system market estimates and forecasts, 2021 - 2033 (USD Million)
4.2.5. LED Grow Light
4.2.5.1. LED grow light market estimates and forecasts, 2021 - 2033 (USD Million)
4.2.6. RFID Tags & Readers
4.2.6.1. RFID tags & readers market estimates and forecasts, 2021 - 2033 (USD Million)
4.3. Software
4.3.1. Software market estimates and forecasts, 2021 - 2033 (USD Million)
4.3.2. Web-based
4.3.2.1. Web-based market estimates and forecasts, 2021 - 2033 (USD Million)
4.3.3. Cloud-based
4.3.3.1. Cloud-based market estimates and forecasts, 2021 - 2033 (USD Million)
4.4. Services
4.4.1. Services market estimates and forecasts, 2021 - 2033 (USD Million)
4.4.2. System Integration & Consulting
4.4.2.1. System integration & consulting market estimates and forecasts, 2021 - 2033 (USD Million)
4.4.3. Maintenance & Support
4.4.3.1. Maintenance & support market estimates and forecasts, 2021 - 2033 (USD Million)
4.4.4. Managed Types
4.4.4.1. Managed types market estimates and forecasts, 2021 - 2033 (USD Million)
4.4.4.1.1. Data Types
4.4.4.1.2. Analytics Types
4.4.4.1.3. Farm Operation Types
4.4.5. Assisted Professional Types
4.4.5.1. Assisted professional types market estimates and forecasts, 2021 - 2033 (USD Million)
4.4.5.1.1. Supply Chain Management Types
4.4.5.1.2. Climate Information Types
Chapter 5. Smart Agriculture Market Application Outlook
5.1. Smart Agriculture Market, By Application Analysis & Market Share, 2025 & 2033
5.2. Precision Farming
5.2.1. Precision farming market estimates and forecasts, 2021 - 2033 (USD Million)
5.2.2. Yield Monitoring
5.2.2.1. Yield monitoring market estimates and forecasts, 2021 - 2033 (USD Million)
5.2.2.2. On-Farm
5.2.2.2.1. On-farm market estimates and forecasts, 2021 - 2033 (USD Million)
5.2.2.3. Off-Farm
5.2.2.3.1. Off-farm market estimates and forecasts, 2021 - 2033 (USD Million)
5.2.3. Field Mapping
5.2.3.1. Field mapping market estimates and forecasts, 2021 - 2033 (USD Million)
5.2.4. Crop Scouting
5.2.4.1. Crop scouting market estimates and forecasts, 2021 - 2033 (USD Million)
5.2.5. Weather Tracking & Forecasting
5.2.5.1. Weather tracking & forecasting market estimates and forecasts, 2021 - 2033 (USD Million)
5.2.6. Irrigation Management
5.2.6.1. Irrigation management market estimates and forecasts, 2021 - 2033 (USD Million)
5.2.7. Inventory Management
5.2.7.1. Inventory management market estimates and forecasts, 2021 - 2033 (USD Million)
5.2.8. Farm Labor Management
5.2.8.1. Farm labor management market estimates and forecasts, 2021 - 2033 (USD Million)
5.3. Livestock Monitoring
5.3.1. Livestock monitoring market estimates and forecasts, 2021 - 2033 (USD Million)
5.4. Smart Greenhouse
5.4.1. Smart greenhouse market estimates and forecasts, 2021 - 2033 (USD Million)
5.5. Others
5.5.1. Others market estimates and forecasts, 2021 - 2033 (USD Million)
Chapter 6. Smart Agriculture Market: Regional Estimates & Trend Analysis
6.1. Smart Agriculture Market Share, By Region, 2025 & 2033, USD Million
6.2. North America
6.2.1. North America Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.2.2. U.S.
6.2.2.1. U.S. Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.2.3. Canada
6.2.3.1. Canada Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.2.4. Mexico
6.2.4.1. Mexico Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.3. Europe
6.3.1. Europe Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.3.2. UK
6.3.2.1. UK Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.3.3. Germany
6.3.3.1. Germany Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.3.4. France
6.3.4.1. France Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.3.5. Netherlands
6.3.5.1. Netherlands Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.3.6. Russia
6.3.6.1. Russia Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.4. Asia Pacific
6.4.1. Asia Pacific Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.4.2. China
6.4.2.1. China Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.4.3. India
6.4.3.1. India Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.4.4. Japan
6.4.4.1. Japan Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.4.5. Australia
6.4.5.1. Australia Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.4.6. Singapore
6.4.6.1. Singapore Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.5. Latin America
6.5.1. Latin America Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.5.2. Brazil
6.5.2.1. Brazil Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.6. Middle East and Africa
6.6.1. Middle East and Africa Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
6.6.2. Turkey
6.6.2.1. Turkey Smart Agriculture Market Estimates and Forecasts, 2021 - 2033 (USD Million)
Chapter 7. Competitive Landscape
7.1. Company Categorization
7.2. Company Market Positioning
7.3. Company Heat Map Analysis
7.4. Company Profiles/Listing
7.4.1. Ag Leader Technology
7.4.1.1. Participant’s Overview
7.4.1.2. Financial Performance
7.4.1.3. Product Benchmarking
7.4.1.4. Strategic Initiatives
7.4.2. AGCO Corporation
7.4.2.1. Participant’s Overview
7.4.2.2. Financial Performance
7.4.2.3. Product Benchmarking
7.4.2.4. Strategic Initiatives
7.4.3. Kubota Corporation.
7.4.3.1. Participant’s Overview
7.4.3.2. Financial Performance
7.4.3.3. Product Benchmarking
7.4.3.4. Strategic Initiatives
7.4.4. AgEagle Aerial Systems Inc.
7.4.4.1. Participant’s Overview
7.4.4.2. Financial Performance
7.4.4.3. Product Benchmarking
7.4.4.4. Strategic Initiatives
7.4.5. Autonomous Solutions, Inc.
7.4.5.1. Participant’s Overview
7.4.5.2. Financial Performance
7.4.5.3. Product Benchmarking
7.4.5.4. Strategic Initiatives
7.4.6. Argus Control Systems Ltd
7.4.6.1. Participant’s Overview
7.4.6.2. Financial Performance
7.4.6.3. Product Benchmarking
7.4.6.4. Strategic Initiatives
7.4.7. BouMatic Robotic B.V.
7.4.7.1. Participant’s Overview
7.4.7.2. Financial Performance
7.4.7.3. Product Benchmarking
7.4.7.4. Strategic Initiatives
7.4.8. CropMetrics
7.4.8.1. Participant’s Overview
7.4.8.2. Financial Performance
7.4.8.3. Product Benchmarking
7.4.8.4. Strategic Initiatives
7.4.9. CLAAS KGaA mbH
7.4.9.1. Participant’s Overview
7.4.9.2. Financial Performance
7.4.9.3. Product Benchmarking
7.4.9.4. Strategic Initiatives
7.4.10. CropZilla
7.4.10.1. Participant’s Overview
7.4.10.2. Financial Performance
7.4.10.3. Product Benchmarking
7.4.10.4. Strategic Initiatives
7.4.11. Deere & Company
7.4.11.1. Participant’s Overview
7.4.11.2. Financial Performance
7.4.11.3. Product Benchmarking
7.4.11.4. Strategic Initiatives
7.4.12. DICKEY-john
7.4.12.1. Participant’s Overview
7.4.12.2. Financial Performance
7.4.12.3. Product Benchmarking
7.4.12.4. Strategic Initiatives
7.4.13. DroneDeploy
7.4.13.1. Participant’s Overview
7.4.13.2. Financial Performance
7.4.13.3. Product Benchmarking
7.4.13.4. Strategic Initiatives
7.4.14. Farmers Edge Inc
7.4.14.1. Participant’s Overview
7.4.14.2. Financial Performance
7.4.14.3. Product Benchmarking
7.4.14.4. Strategic Initiatives
7.4.15. Grownetics, Inc.
7.4.15.1. Participant’s Overview
7.4.15.2. Financial Performance
7.4.15.3. Product Benchmarking
7.4.15.4. Strategic Initiatives
7.4.16. Corteva Agriscience.
7.4.16.1. Participant’s Overview
7.4.16.2. Financial Performance
7.4.16.3. Product Benchmarking
7.4.16.4. Strategic Initiatives
7.4.17. Gamaya
7.4.17.1. Participant’s Overview
7.4.17.2. Financial Performance
7.4.17.3. Product Benchmarking
7.4.17.4. Strategic Initiatives
7.4.18. GEA Group Aktiengesellschaft
7.4.18.1. Participant’s Overview
7.4.18.2. Financial Performance
7.4.18.3. Product Benchmarking
7.4.18.4. Strategic Initiatives
7.4.19. Raven Industries
7.4.19.1. Participant’s Overview
7.4.19.2. Financial Performance
7.4.19.3. Product Benchmarking
7.4.19.4. Strategic Initiatives
7.4.20. Trimble Inc.
7.4.20.1. Participant’s Overview
7.4.20.2. Financial Performance
7.4.20.3. Product Benchmarking
7.4.20.4. Strategic Initiatives
7.4.21. Topcon Positioning System
7.4.21.1. Participant’s Overview
7.4.21.2. Financial Performance
7.4.21.3. Product Benchmarking
7.4.21.4. Strategic InitiativesList of Tables
Table 1 Global smart agriculture market size estimates & forecasts 2021 - 2033 (USD Million)
Table 2 Global smart agriculture market, by region 2021 - 2033 (USD Million)
Table 3 Global smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 4 Global smart agriculture market, by application 2021 - 2033 (USD Million)
Table 5 Hardware smart agriculture market, by region 2021 - 2033 (USD Million)
Table 6 Software smart agriculture market, by region 2021 - 2033 (USD Million)
Table 7 Services smart agriculture market, by region 2021 - 2033 (USD Million)
Table 8 Precision farming smart agriculture market, by region 2021 - 2033 (USD Million)
Table 9 Livestock monitoring smart agriculture market, by region 2021 - 2033 (USD Million)
Table 10 Smart greenhouse smart agriculture market, by region 2021 - 2033 (USD Million)
Table 11 Others smart agriculture market, by region 2021 - 2033 (USD Million)
Table 12 North America smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 13 North America smart agriculture market, by application 2021 - 2033 (USD Million)
Table 14 U S smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 15 U S smart agriculture market, by application 2021 - 2033 (USD Million)
Table 16 Canada smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 17 Canada smart agriculture market, by application 2021 - 2033 (USD Million)
Table 18 Mexico smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 19 Mexico smart agriculture market, by application 2021 - 2033 (USD Million)
Table 20 Europe smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 21 Europe smart agriculture market, by application 2021 - 2033 (USD Million)
Table 22 UK smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 23 UK smart agriculture market, by application 2021 - 2033 (USD Million)
Table 24 Germany smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 25 Germany smart agriculture market, by application 2021 - 2033 (USD Million)
Table 26 France smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 27 France smart agriculture market, by application 2021 - 2033 (USD Million)
Table 28 Netherlands smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 29 Netherlands smart agriculture market, by application 2021 - 2033 (USD Million)
Table 30 Russia smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 31 Russia smart agriculture market, by application 2021 - 2033 (USD Million)
Table 32 Asia Pacific smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 33 Asia Pacific smart agriculture market, by application 2021 - 2033 (USD Million)
Table 34 China smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 35 China smart agriculture market, by application 2021 - 2033 (USD Million)
Table 36 India smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 37 India smart agriculture market, by application 2021 - 2033 (USD Million)
Table 38 Japan smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 39 Japan smart agriculture market, by application 2021 - 2033 (USD Million)
Table 40 Australia smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 41 Australia smart agriculture market, by application 2021 - 2033 (USD Million)
Table 42 Singapore smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 43 Singapore smart agriculture market, by application 2021 - 2033 (USD Million)
Table 44 Latin America smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 45 Latin America smart agriculture market, by application 2021 - 2033 (USD Million)
Table 46 Brazil smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 47 Brazil smart agriculture market, by application 2021 - 2033 (USD Million)
Table 48 MEA smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 49 MEA smart agriculture market, by application 2021 - 2033 (USD Million)
Table 50 Turkey smart agriculture market, by offering 2021 - 2033 (USD Million)
Table 51 Turkey smart agriculture market, by application 2021 - 2033 (USD Million)List of Figures
Fig. 1 Smart agriculture market segmentation
Fig. 2 Information procurement
Fig. 3 Data analysis models
Fig. 4 Market formulation and validation
Fig. 5 Data validating & publishing
Fig. 6 Market snapshot
Fig. 7 Segment snapshot, by offering
Fig. 8 Segment snapshot, by agriculture type
Fig. 9 Segment snapshot by application
Fig. 10 Competitive landscape snapshot
Fig. 11 Smart agriculture market value, 2021 - 2033 (USD Million)
Fig. 12 Smart agriculture market - Industry value chain analysis
Fig. 13 Smart agriculture market - Market trends
Fig. 14 Smart agriculture market: Porter’s analysis
Fig. 15 Smart agriculture market: PESTEL analysis
Fig. 16 Smart agriculture market, by offering: Key takeaways
Fig. 17 Smart agriculture market, by offering: Market share, 2025 & 2033
Fig. 18 Hardware smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 19 Software smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 20 Services smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 21 Smart agriculture market, by application: Key takeaways
Fig. 22 Smart agriculture market, by application: Market share, 2025 & 2033
Fig. 23 Precision farming smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 24 Livestock monitoring smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 25 Smart greenhouse smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 26 Others smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 27 Global smart agriculture market revenue, by region, 2025 & 2033, (USD Million)
Fig. 28 North America smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 29 U.S. smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 30 Canada smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 31 Mexico smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 32 Europe smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 33 UK smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 34 Germany smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 35 France smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 36 Netherlands smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 37 Russia smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 38 Asia Pacific smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 39 China smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 40 India smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 41 Japan smart agriculture Market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 42 Australia smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 43 Singapore smart agriculture Market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 44 Latin America smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 45 Brazil smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 46 Middle East & Africa smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 47 Turkey smart agriculture market estimates & forecasts, 2021 - 2033 (USD Million)
Fig. 48 Key company categorization
Fig. 49 Smart agriculture market - Key company market share analysis, 2025
Fig. 50 Strategic frameworkFrequently Asked Questions About This Report
The global smart agriculture market size was valued at USD 25.4 billion in 2024 and is estimated at USD 32.2 billion for 2026.
The global smart agriculture market is expected to grow at a CAGR of 14.6% from 2025 to 2033, reaching USD 83.7 billion by 2033.
North America dominated with a 43.5% revenue share in 2024.
Key factors that are driving the smart agriculture market growth include increasing automation of commercial greenhouses and growing adoption of the Controlled Environment Agriculture (CEA) in the indoor farming sector.
Some key players operating in the smart agriculture market include Argus Control Systems Ltd. (Canada), Autonomous Solutions, Inc. (U.S.), CLAAS (Germany), and CropZilla Software, Inc. (U.S.).
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


