
- Home
- »
- Plastics, Polymers & Resins
- »
-
Silicone Film Market Size, Share & Trends Report 2026-2033GVR Report cover

Silicone Film Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Silicone Release Films, Silicone Coated Films), By Application (Release Liners, Labels & Tapes, Medical Dressings, Graphic Films), By Region, And Segment Forecasts
Market Size, 2025
$4.3BMarket Estimate, 2026
$4.6BMarket Forecast, 2033
$7.5BCAGR, 2026–2033
7.3%Silicone Film Market Summary
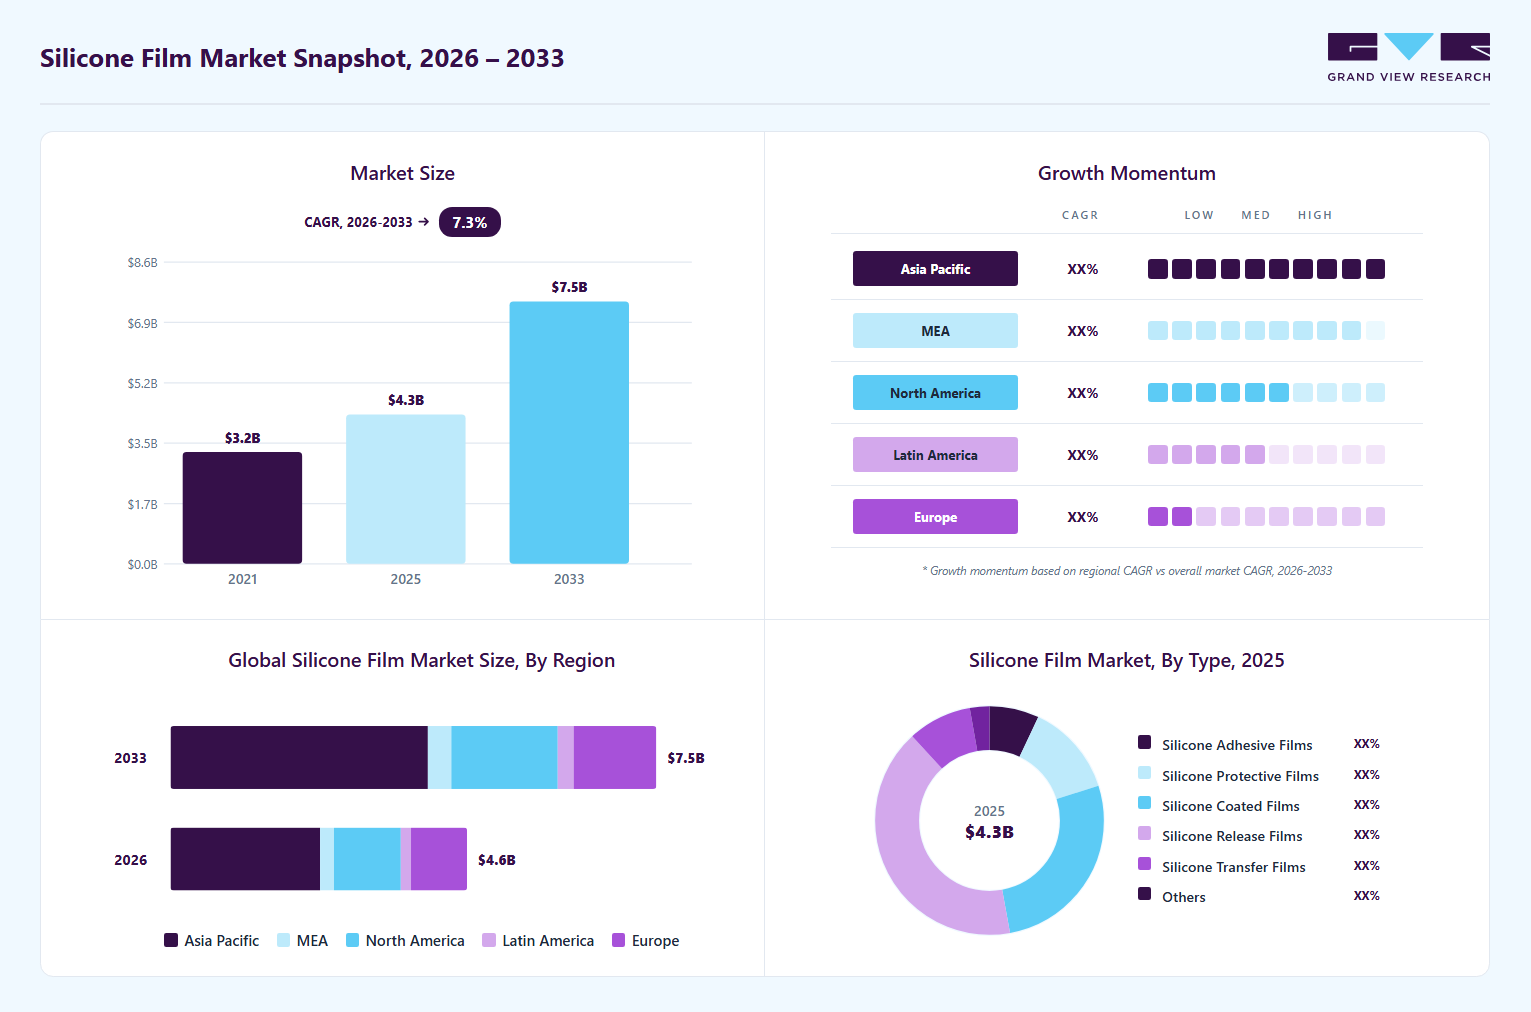
The global silicone film market size was valued at USD 4.3 billion in 2025 and is projected to grow from USD 4.6 billion in 2026 to USD 7.5 billion by 2033, at a CAGR of 7.3% from 2026 to 2033. Asia Pacific dominated the global market with the largest revenue share of 50.1% in 2025. The global silicone film market is witnessing growth due to increasing demand from electronics, EVs, aerospace, and healthcare industries.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Silicone release films segment dominated the market in terms of revenue, accounting for 41.0% market share in 2025.
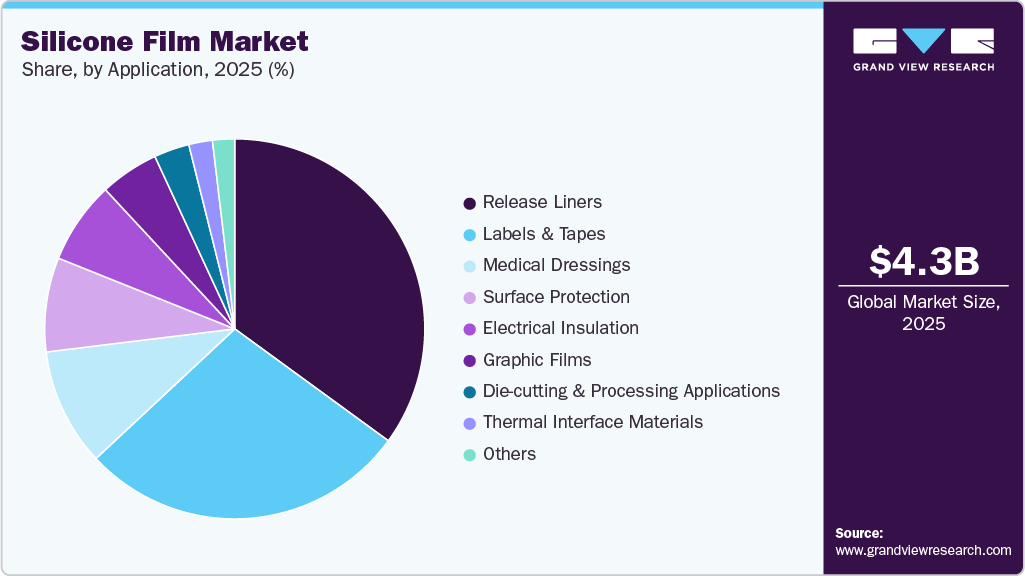
- By application: Release liners segment led the market by application, accounting for 35.0% of revenue in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (50.1% revenue share, 2025)
- The silicone film industry in India is expected to grow at a CAGR of 9.6% from 2026 to 2033.
Market Size & Forecast
- Market size in 2025: USD 4.3 Billion
- Estimated market size in 2026: USD 4.6 Billion
- Projected market size by 2033: USD 7.5 Billion
- CAGR (2026-2033): 7.3%
Prism AI by Grand View Research Free to tryAsk a question about the silicone film marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Rising use in flexible electronics, battery insulation, medical dressings, and drug delivery systems owing to its optical clarity, thermal stability, flexibility, biocompatibility, breathability, and water-resistant properties. Rapid adoption of skin-friendly and biocompatible silicone films for advanced wound care and wearable medical devices is emerging as a major trend in the silicone film market. Healthcare manufacturers are increasingly integrating breathable silicone films in wound dressings, transdermal drug-delivery patches, scar management products, and soft-contact diagnostic devices. Silicone films are gaining preference due to their gentle skin adhesion, moisture permeability, chemical resistance, and long-term biocompatibility. Demand is rising across minimally invasive healthcare technologies, remote patient monitoring systems, and flexible biosensors. Increasing investments in home healthcare, aging population care, and advanced medical electronics are further accelerating market expansion.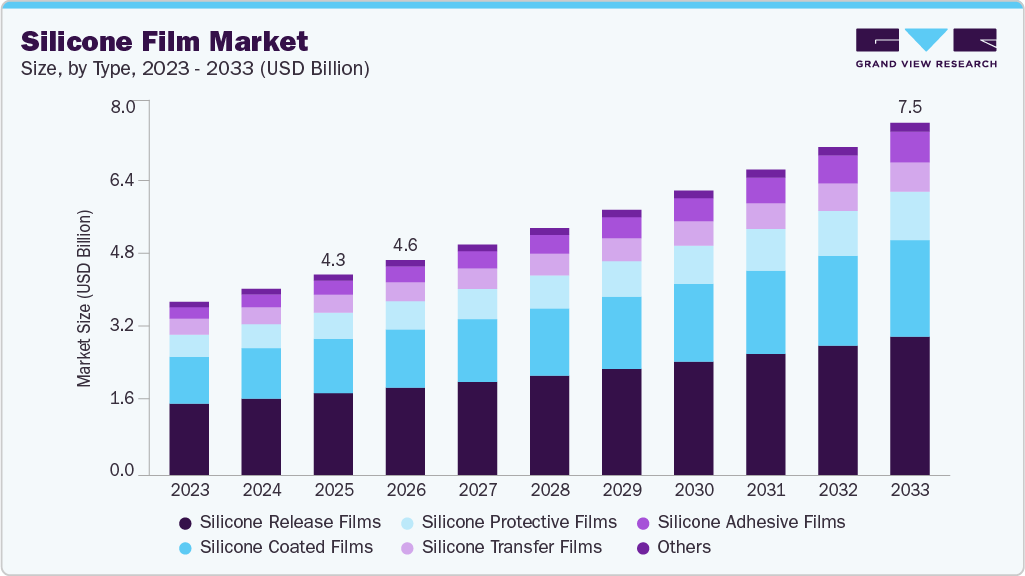 To learn more about this report, Download Free Sample Report
Sustainability-focused silicone film technologies and flexible electronics applications are gaining significant traction in the silicone film market due to tightening environmental regulations and rapid growth in smart connected devices. Manufacturers are investing in recyclable and biodegradable silicone-release liners along with silicone-free release coatings to support circular economy initiatives and reduce industrial waste generation. Growing demand from wearable electronics and IoT-enabled devices is driving the use of flexible silicone films for encapsulation, insulation, and moisture protection. The renewable energy sector is also increasing the adoption of silicone films in lightweight and portable solar panel applications that require high durability and thermal stability.
Market Dynamics
The silicone film market is witnessing strong growth from the electronics and electrical sector due to rising demand for compact, lightweight, and high-performance electronic components. Silicone films are widely used as insulation materials, adhesive layers, and protective barriers in flexible electronics, printed circuit boards, electronic displays, and touchscreen devices. Increasing production of consumer electronics, wearable devices, and advanced display technologies is accelerating material demand across the Asia Pacific and North America. In addition, expanding investments in semiconductor fabrication facilities and electronics manufacturing plants are strengthening long-term consumption of high-durability silicone film materials.
Government incentive programs supporting domestic electronics manufacturing and supply chain localization are further contributing to market expansion. Financial support for semiconductor plants, display panel production, and advanced electronics assembly is increasing the adoption of silicone films in critical thermal management and electrical insulation applications. Rapid improvements in IoT gadgets, smart devices, and connected consumer electronics are also supporting demand for high-performance protective films with enhanced flexibility and heat resistance. Manufacturers are focusing on technologically advanced silicone film formulations that provide superior dielectric performance, dimensional stability, moisture protection, and compatibility with next-generation electronic systems.
One of the key restraints affecting the silicone film market is the instability in the supply of critical raw materials used in silicone production. Silicon metal, methyl chloride, and specialty organic intermediates are exposed to frequent supply chain disruptions caused by limited supplier concentration, logistics bottlenecks, and tightening environmental regulations in key producing countries. These disruptions have increased procurement uncertainty for silicone film manufacturers, particularly in high-performance electronics, medical, and industrial applications. In addition, fluctuating availability of upstream materials has extended lead times and reduced production flexibility, creating challenges in maintaining stable supply commitments across global end-use industries.
Market Concentration & Characteristics
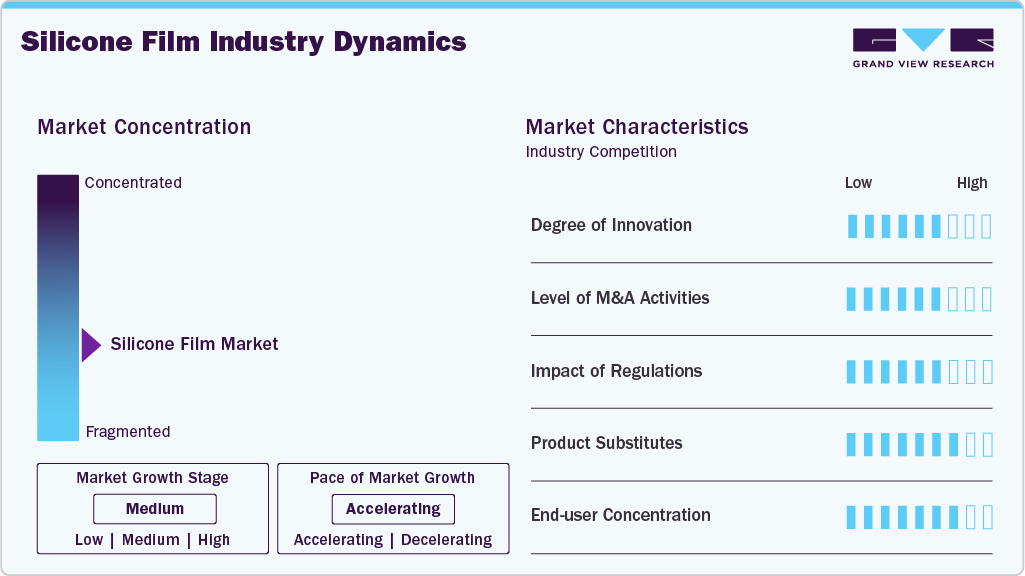
The market growth stage is medium, and growth is accelerating. The market exhibits slight fragmentation, with key players dominating the industry landscape. Major companies such as 3M, Dow Inc., Momentive Performance Materials, Shin-Etsu Chemical, Wacker Chemie, Mitsubishi Chemical, Polyplex Corporation, Gascogne Flexible, Quanjiao Guangtai Adhesive Products, Fujiko, and others play a significant role in shaping the market dynamics. These leading players often drive innovation in the market by introducing new products, technologies, and materials to meet the industry's evolving demands.
The degree of innovation in the silicone film market is driven by continuous improvements in material performance, coating technology, and application-specific design. Manufacturers are focusing on thinner films, better thermal resistance, improved release properties, and enhanced durability to meet the needs of electronics, medical, industrial, and personal care applications. These innovations help improve product efficiency, reduce waste, and expand use in high-value segments. They also support compliance with stricter environmental and performance standards, which strengthens market differentiation and encourages premium pricing in specialized applications.
 To learn more about this report, Download Free Sample Report
Product substitutes in the silicone film market include polyurethane films, fluoropolymer films, polyester films, and polyethylene films. These alternatives affect the market by offering lower-cost or more widely available options for applications where the highest heat resistance, flexibility, or chemical stability of silicone films is not essential. As a result, silicone film manufacturers face pricing pressure in standard-use segments. However, silicone films continue to hold an advantage in demanding applications such as medical, electronics, and high-temperature industrial uses, where substitute materials may not provide the same performance, durability, or reliability.
Type Insights
The silicone release films segmentdominated the market across type segmentation in terms of revenue, accounting for 41.0% market share in 2025, and is forecast to grow at a 6.8% CAGR from 2026 to 2033. Growth is driven by the automotive industry’s increasing focus on lightweight vehicles and improved performance. These films are used in composite manufacturing for thermal insulation, vibration control, and surface protection in advanced automotive components. Rising electric vehicle adoption, supported by emission regulations, is boosting demand. Automation in vehicle production and growing industrialization, along with higher demand for commercial vehicles in logistics, are further supporting market growth.
The silicone adhesive films segment is expected to expand at a 10.2% CAGR in the silicone film market over the forecast period.Growth is supported by the healthcare and medical devices sector, driven by an aging population and rising use of remote patient monitoring systems. Increasing lifestyle diseases are boosting demand for wearable devices such as glucose monitors, biosensors, and diagnostic patches. Silicone films are used in medical adhesives, surgical tapes, and wound care due to skin-friendly, flexible, and breathable properties, supporting wider adoption in advanced healthcare applications.
Application Insights
The release liners segment led the market by application, accounting for 35.0% of revenue in 2025, and is projected to grow at a 6.3% CAGR from 2026 to 2033. The growth of e-commerce and logistics is driving demand higher for release liner applications used in packaging and labeling. Increasing online sales are boosting the use of shipping labels, barcodes, tamper-evident seals, and pressure-sensitive tapes. Quick commerce is adding to frequent packaging needs. Demand is also rising from food-grade packaging and pharmaceutical applications requiring secure, hygienic, and compliant labeling solutions.
 To learn more about this report, Download Free Sample Report
The thermal interface materials segment is expected to grow at the fastest CAGR of 11.6% over the forecast period. Growth is driven by miniaturization of consumer electronics, mobile devices, medical equipment, and home appliances, where compact designs increase material demand. Rising disposable incomes support higher consumption of advanced electrical and digital devices, strengthening component requirements. Expansion of online retail platforms, IoT devices, and home automation systems further accelerates adoption. Increasing power density in compact architectures raises heat generation, creating demand for silicone films with high thermal stability, dielectric strength, and thin-film consistency. Growth in AI-enabled devices, high-performance computing, and data centers reinforces insulation and thermal management to ensure computing stability and prevent hardware failure.
Regional Insights
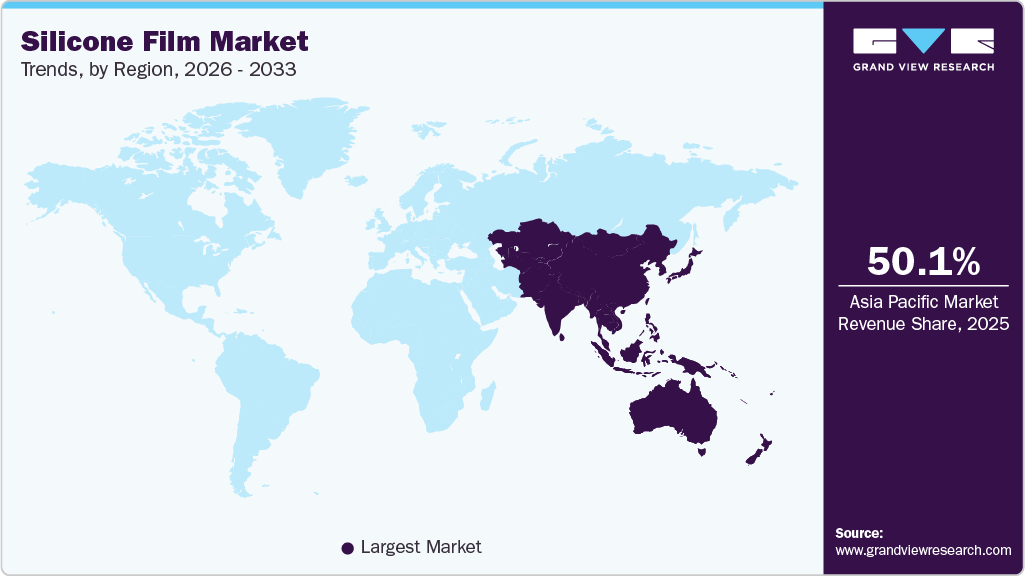
The Asia Pacific silicone film market held the largest revenue share of 50.1% in 2025. The region is expected to grow at a CAGR of 8.1% over the forecast perioddue to strong manufacturing concentration in China, Japan, South Korea, and India. Expansion in electronics production driven by AI-enabled devices, semiconductors, and advanced consumer electronics is increasing the adoption of silicone film for insulation, surface protection, and thermal stability applications. Growing output of home appliances, medical devices, and flexible electronic components is further supporting demand. Key end users include electronics assemblers, appliance manufacturers, medical device producers, and precision component suppliers across integrated supply chains.
 To learn more about this report, Download Free Sample Report
India Silicone Film Market Trends
The Indian silicone film market is expanding steadily, driven by strong demand from electronics and semiconductors, healthcare, packaging, and e-commerce applications. Rapid growth in electronics manufacturing is increasing the need for high-heat-resistant and micro-durable silicone films used in device protection and precision components. Healthcare modernization is supporting adoption in wound care, transdermal patches, and advanced medical dressings. Packaging and e-commerce growth is driving demand for silicone release liners in tapes, labels, and protective packaging solutions. Domestic manufacturing initiatives further strengthen market expansion across end-use industries.
North America Silicone Film Market Trends
North America's silicone film market growth is supported by semiconductor miniaturization, advanced medical technologies, and rising demand for premium personal care products. The region continues to attract large investments in chip fabrication and advanced packaging, strengthening consumption across high-performance materials. Medical device manufacturers are expanding connected and electronics-enabled healthcare systems, increasing reliance on thin, stable silicone films. Demand is concentrated among semiconductor producers, electronics OEMs, medical device companies, and personal care formulators requiring thermal stability, dielectric strength, and uniform film performance in critical applications.
The U.S. silicone film market is witnessing steady growth driven by increasing adoption of thin-film solar cells and expanding demand from electronics and display applications. The shift toward renewable energy is accelerating the deployment of thin-film photovoltaic systems, supporting the need for high-performance silicone films used in encapsulation and protection layers. In electronics and displays, demand is rising for flexible amorphous silicon in flat-panel displays, sensors, and wearable devices. These materials offer thermal stability, flexibility, and durability, which are critical for advanced miniaturized electronic systems and next-generation energy-efficient technologies.
Europe Silicone Film Market Trends
Europe’s silicone film market is driven by a strong cosmetics and personal care industry, supported by premium skincare, haircare, and beauty formulation innovation. High consumer preference for high-performance and sensory-enhancing ingredients sustains demand for silicone-based films in emulsions, serums, and protective skin applications. The region’s advanced medical device sector further strengthens uptake, particularly for wound care, diagnostic patches, and skin-contact products requiring biocompatibility and regulatory compliance. Key end users include cosmetic manufacturers, contract formulation companies, medical device producers, and specialty electronics firms focusing on precision, safety, and sustainable material performance.
Central & South America Silicone Film Market Trends
The Central & South America silicone film market is experiencing steady growth driven by rising demand from consumer electronics, beauty, and medical aesthetics sectors. Increasing adoption of silicone films in skincare formulations, cosmetic products, and advanced wound care applications is supporting regional consumption. Expanding e-commerce channels are improving access to premium consumer and specialty materials, strengthening downstream demand. The manufacturing base remains relatively limited, but local assembly and packaging activities are increasing. Key end users include personal care brands, electronics distributors, and medical device manufacturers focused on high-performance functional materials. Growth is moderated by supply chain dependence and uneven industrial development.
Middle East and Africa Silicone Film Market Trends
In the Middle East & Africa silicone film market, demand is primarily driven by expanding healthcare infrastructure, improving access to medical devices, and rising consumption of premium personal care products. International agencies such as WHO and UNIDO highlight ongoing investments to strengthen regional healthcare systems and local medical manufacturing capabilities, supporting the adoption of advanced silicone-based materials. Growth in cosmetics, skincare, and hygiene products is further reinforcing demand across urban consumer segments. Key end users include medical device importers, hospitals, healthcare providers, cosmetics manufacturers, and consumer electronics distributors operating across import-dependent supply chains and emerging regional production hubs.
Key Silicone Film Company Insights
Some of the key players operating in the market include Shin-Etsu Chemical and Mitsubishi Chemical.
-
Shin-Etsu Chemical is a major participant in the silicone film market with a strong portfolio of high-purity silicones, silicone resins, and advanced functional materials. The company focuses on high-performance applications across electronics, semiconductors, automotive components, and industrial manufacturing. Its emphasis on material purity, thermal resistance, and dimensional stability strengthens its position in precision-driven silicone film applications. Shin-Etsu Chemical’s advanced R&D capabilities, large-scale integrated production facilities, and strong global supply chain support consistent quality and enable the development of specialized silicone films for next-generation electronics, optical systems, and high-reliability industrial uses.
-
Mitsubishi Chemical is a prominent participant in silicone film market with a diversified portfolio of advanced materials, functional polymers, and specialty film technologies. The company focuses on high-performance applications across electronics, automotive, medical, and industrial packaging sectors, supporting demand for durable and thermally stable film solutions. Its emphasis on carbon neutrality initiatives, process efficiency, and material innovation strengthens its position in next-generation sustainable materials. Mitsubishi Chemical’s global manufacturing footprint and strong R&D capabilities enable the development of customized film solutions for evolving electronics and mobility requirements.
Polyplex Corporation and Fujiko are some of the emerging participants in the silicone film market.
-
Polyplex Corporation is strengthening its position in the silicone film market value chain through high-performance polyester films used as key substrates for silicone-coated and functional films across packaging, electronics, and industrial insulation applications. The company focuses on expanding specialty biaxially oriented PET film capacity with improved thermal resistance, optical clarity, and barrier performance. Growing demand from flexible electronics, solar backsheet materials, and advanced packaging is supporting adoption. Its global manufacturing footprint and cost-efficient production base enable reliable supply to converters and downstream coating players. Emphasis on sustainability and recyclable film solutions further supports long-term market relevance.
-
Fujiko is a regional participant in the silicone film market with a focus on adhesive-based films and specialty material solutions for packaging, electronics, and industrial applications. It emphasizes formulation expertise in pressure-sensitive adhesives, surface coatings, and functional film systems that enhance durability, moisture resistance, and thermal stability in end-use environments. Its regional manufacturing capabilities and cost-competitive production base support growing demand from electronics, consumer packaging, and industrial conversion sectors across Asia. Fujiko’s expanding presence in customized silicone film solutions supports its positioning in mid-tier specialty materials markets.
Key Silicone Film Companies
The following key companies have been profiled for this study on the silicone film market.
-
3M
-
Dow Inc.
-
Momentive Performance Materials
-
Shin-Etsu Chemical
-
Wacker Chemie
-
Mitsubishi Chemical
-
Polyplex Corporation
-
Gascogne Flexible
-
Quanjiao Guangtai Adhesive Products
-
Fujiko
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weakness
Mature Players: Dow Inc.; Shin-Etsu Chemical; Wacker Chemie and Mitsubishi Chemical
- Focuses on delivering high-performance silicone film products for electronics, healthcare, industrial protection, and release liner applications. Growth strategy centers on integrated silicone production capabilities, strategic partnerships with customers, and innovation tailored to specific applications, while advancing sustainable formulations and coating technologies.
- Concentrates on advanced silicone film materials used in semiconductors, electronics, optical systems, and specialty industrial applications. Prioritizes continuous research and development, improvement in material purity, and expansion of high-value silicone technology portfolios.
- Develops specialty silicone film solutions for automotive, electronics, medical, and industrial processing sectors. Emphasizes performance enhancement, material integration, sustainable product innovation, technical collaborations, and expansion of regional manufacturing and customer support networks.
- Extensive global production footprint supported by an integrated silicone value chain, enabling efficient supply stability and broad market reach. Diverse product offerings and strong technical service capabilities enhance customer engagement across various end-use industries. Established brand reputation and long-term client partnerships further strengthen competitive positioning.
- Advanced expertise in specialty silicone technologies and electronic materials supports the development of high-performance solutions. Consistent product quality, operational reliability, and technical precision reinforce its strong position in premium market segments. Deep integration within semiconductor and electronics supply networks enhances industry presence.
- Vulnerability to fluctuations in raw material prices and high energy consumption during manufacturing can pressure operating costs. Extensive large-scale production structures may also limit adaptability for highly customized niche requirements. In addition, reliance on industrial market cycles can affect profitability consistency.
- Strong exposure to technology-oriented industries increases sensitivity to semiconductor sector demand variations. A premium product pricing strategy may further restrict competitiveness in price-sensitive regional markets.
- Manufacturing operations concentrated in Europe may result in elevated compliance and operational expenses. Dependence on automotive and industrial sectors can create cyclical demand risks, while the silicone film segment’s smaller contribution within the overall portfolio may reduce dedicated strategic attention and intensify competition from specialized silicone film manufacturers..
Emerging Players: Polyplex Corporation and Fujiko
- Concentrates on specialty film production with increasing involvement in premium industrial and packaging film segments. Expanding manufacturing capacity across key regions while enhancing export reach in Asia, Europe, and North America. Prioritizes diversified product offerings alongside efficient and cost-effective production practices.
- Specializes in tailored adhesive films and silicone-coated material solutions serving electronics, industrial, and packaging industries. Focuses on application-driven product development, adaptable manufacturing systems, and strong regional customer collaborations.
- Targets medium-scale specialty market demand through competitive pricing strategies, operational flexibility, and customized solution capabilities to strengthen market positioning across diverse end-use sectors.
- Advanced film processing know-how and vertically integrated manufacturing operations help maintain cost-efficient production. A well-established customer network in packaging and industrial films also strengthens cross-selling opportunities for silicone-coated film products. Broad global distribution capabilities further support deeper regional market reach.
- Strong understanding of regional market dynamics and expertise in adhesive-based film technologies enable quick adaptation to evolving customer needs. High flexibility in product customization enhances competitiveness across specialized industrial applications.
- Cost-effective pricing strategies support stronger penetration in mid-range market segments, particularly across rapidly growing Asian markets
- Comparatively lower participation in advanced silicone film technologies than leading global silicone material companies, with significant reliance on packaging-sector demand trends potentially limiting growth in specialty applications.
- Reduced international brand recognition and a more limited global distribution presence compared to well-established silicone film manufacturers, affecting broader market penetration.
- Smaller manufacturing scale and comparatively lower investment capacity in R&D and technology development may hinder expansion into high-performance electronics and medical-grade silicone film app
Recent Developments
-
In November 2025, Techlan Ltd introduced its new 80gsm Glassine Silicone Release Liner. The product is engineered to offer strong processing efficiency, high reliability, and improved environmental performance, supporting sustainable and high-quality requirements across industrial and packaging applications.
-
In April 2025, Elkem ASA expanded its SILCOLEASE portfolio for release liners with two new products. The company stated that the solutions support sustainability goals by offering lower carbon impact while maintaining the same technical performance as conventional non-recycled silicone products.
Silicone Film Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.3 billion
Estimated Market size in 2026
USD 4.6 billion
Projected Market size by 2033
USD 7.5 billion
Growth rate
CAGR of 7.3% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue & volume forecast, competitive landscape, growth factors, and trends
Segments covered
Type, application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
U.S.; Canada; Mexico; Europe; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
3M; Dow Inc.; Momentive Performance Materials; Shin-Etsu Chemical; Wacker Chemie; Mitsubishi Chemical; Polyplex Corporation; Gascogne Flexible; Quanjiao Guangtai Adhesive Products; Fujiko
Customization scope
Free report customization (equivalent to up to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Silicone Film Market Report Segmentation
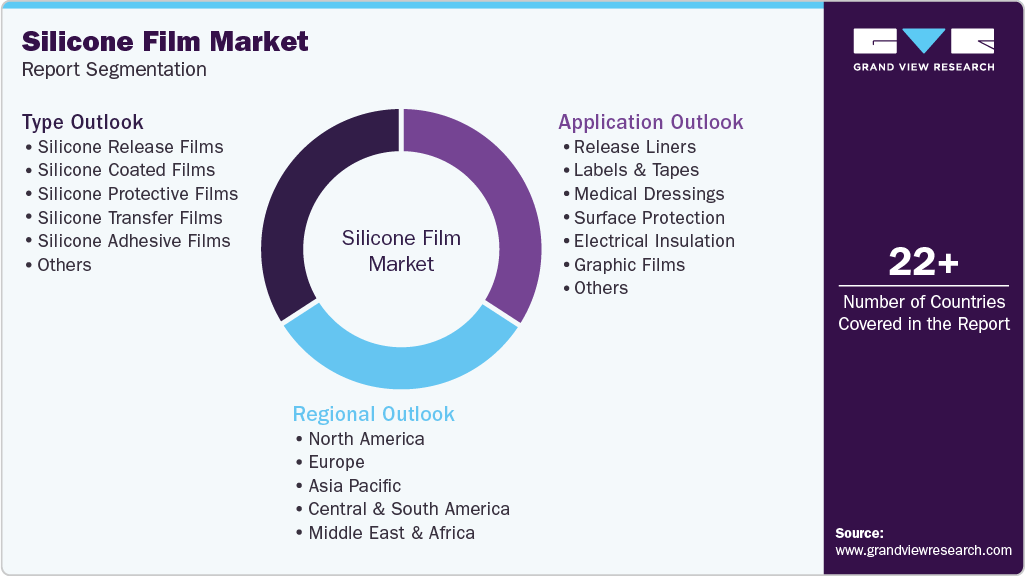
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global silicone film market report based on type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Silicone Release Films
-
Silicone Coated Films
-
Silicone Protective Films
-
Silicone Transfer Films
-
Silicone Adhesive Films
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Release Liners
-
Labels & Tapes
-
Medical Dressings
-
Surface Protection
-
Electrical Insulation
-
Graphic Films
-
Die-cutting & Processing Applications
-
Thermal Interface Materials
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Built the silicone film market outlook by key regions such as North America, Europe, Asia Pacific, Central & South America, and the Middle East & Africa. Included demand patterns, end-use concentration, and regional growth drivers.
Helped identify the most attractive geographies for market entry, expansion, and distribution planning.
Competitive benchmarking
Compared major and emerging players on product portfolio, manufacturing scale, technical capability, market presence, and innovation focus.
Supported competitive positioning, gap analysis, and supplier selection decisions.
Cross-Segmentation
Analyzed the market across region, application, end-use industry, and product type to show where demand overlaps and where growth is concentrated
Enabled a clearer view of high-opportunity niches and the most relevant customer clusters.
Frequently Asked Questions About This Report
The global silicone film market was estimated at around USD 4.3 billion in the year 2025 and is expected to reach around USD 4.6 billion in 2026.
The global silicone film market is expected to grow at a compound annual growth rate of 7.3% from 2026 to 2033 to reach around USD 7.5 billion by 2033.
The silicone release films led the silicone film market in 2025 with a 41.0 % share. The growth is driven by rising demand for high-performance liner materials that provide excellent non-stick properties, heat resistance, and clean release in applications such as labels, tapes, medical products, and industrial packaging.
The key players in the silicone film market are 3M, Dow Inc., Momentive Performance Materials, Shin-Etsu Chemical, Wacker Chemie, Mitsubishi Chemical, Polyplex Corporation, Gascogne Flexible, Quanjiao Guangtai Adhesive Products, and Fujiko
The silicone film market is witnessing growth due to increasing demand from electronics, EVs, aerospace, and healthcare industries. Rising use in flexible electronics, battery insulation, medical dressings, and drug delivery systems owing to its optical clarity, thermal stability, flexibility, biocompatibility, breathability, and water-resistant properties.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


