
- Home
- »
- Next Generation Technologies
- »
-
U.S. Sovereign AI Market Size, Share & Trends Report, 2033GVR Report cover

U.S. Sovereign AI Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Hardware, Software, Services), By Deployment Model (Cloud, On premises, Hybrid), By Technology, By End-use, And Segment Forecasts
Market Size, 2025
$12.7BMarket Estimate, 2026
$14.7BMarket Forecast, 2033
$46.9BCAGR, 2026–2033
18.0%U.S. Sovereign AI Market Summary
The U.S. sovereign AI market size was valued at USD 12.7 billion in 2025 and is projected to grow from USD 14.7 billion in 2026 to USD 46.9 billion by 2033, at a CAGR of 18.0% from 2026 to 2033. The market growth is driven by rising government investments in sovereign AI infrastructure and national AI computing capabilities, increasing demand for data sovereignty and digital sovereignty across critical sectors, expanding deployment of sovereign cloud and secure AI platforms for sensitive workloads, growing focus on AI sovereignty through domestic foundation models and trusted AI ecosystems, and strengthening regulatory frameworks promoting localized AI development, sovereign data centers, and strategic technological independence.
Key Market Trends & Insights
- By component: Hardware segment held the largest revenue share of over 48.0% in 2025
- By deployment model: On-premises segment held the largest revenue share of 42.0% in 2025
- By technology: Machine learning segment held the largest revenue share in 2025
- By end-use: Government & public sector held the largest revenue share in 2025
Market Size & Forecast
- Market Size in 2025: USD 12.7 Billion
- Estimated Market Size in 2026: USD 14.7 Billion
- Projected Market Size by 2033: USD 46.9 Billion
- CAGR (2026–2033): 18.0%
Prism AI by Grand View Research Free to tryAsk a question about the U.S. sovereign AI marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The growing adoption of trusted AI governance frameworks is becoming a defining trend in the U.S. sovereign AI industry as organizations prioritize secure and ethical AI deployment. Government agencies are implementing AI governance, responsible AI, AI risk management, AI compliance, and AI security frameworks to ensure transparency, explainability, and accountability across sovereign AI applications. Increasing emphasis on data privacy, cybersecurity, AI model governance, and regulatory compliance is driving the deployment of trusted sovereign artificial intelligence systems across defense and public-sector organizations. Enterprises are integrating governance capabilities throughout the AI lifecycle to improve operational reliability and reduce cybersecurity risks. Consequently, trusted sovereign AI platforms, secure AI models, and government AI solutions are emerging as key growth areas within the market.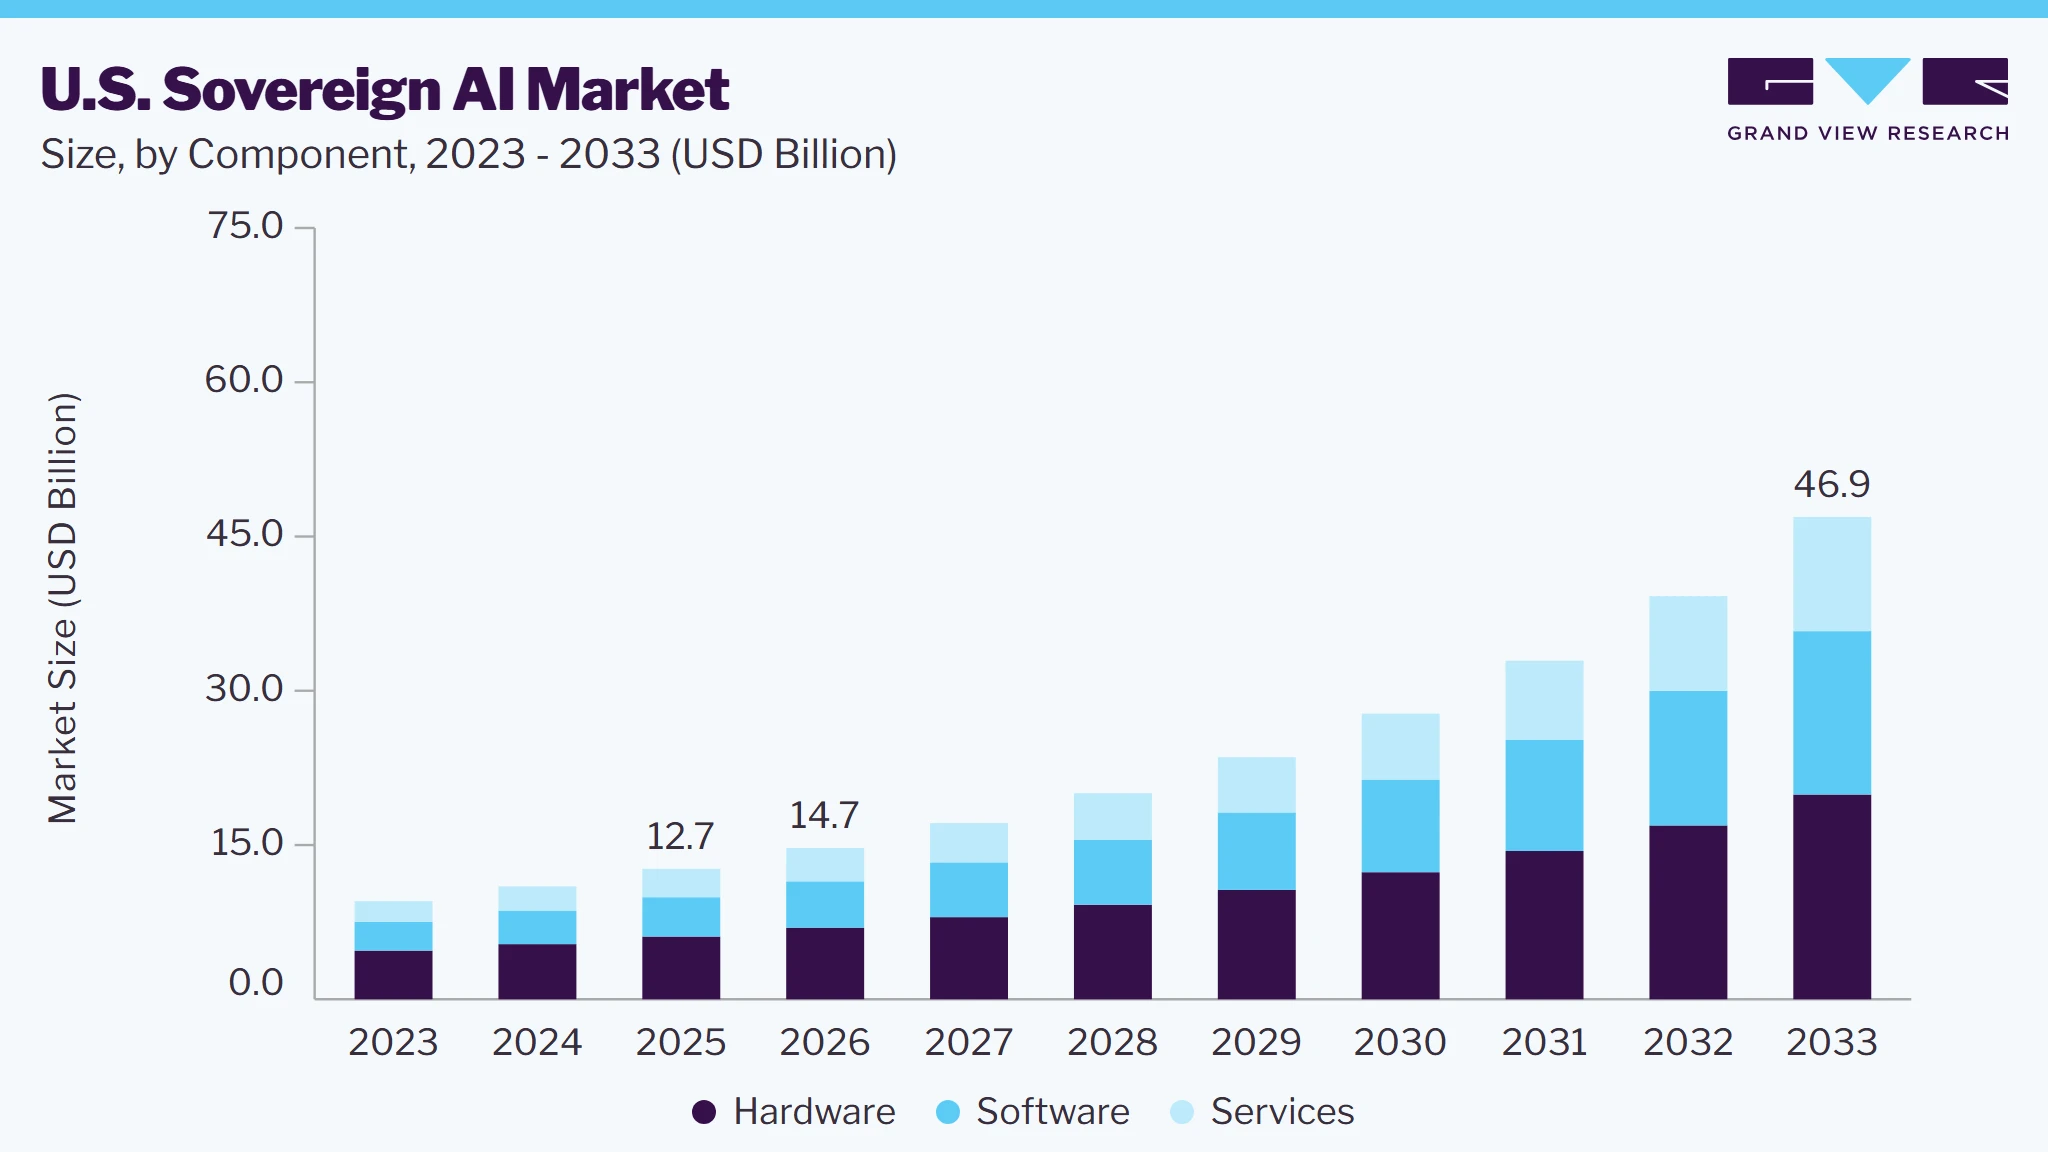 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Increasing deployment of sovereign AI across mission-critical industries is creating significant growth opportunities for the U.S. sovereign AI market. Government agencies and enterprises across defense, healthcare, public safety, critical infrastructure, energy, and financial services are adopting sovereign AI solutions to ensure data sovereignty, AI security, and regulatory compliance. Growing demand for secure AI platforms, AI-powered analytics, machine learning models, large language models (LLMs), computer vision, and natural language processing (NLP) is accelerating digital transformation across highly regulated sectors. Organizations are leveraging sovereign cloud, AI infrastructure, edge AI, and secure AI workloads to enhance operational efficiency, cybersecurity, and decision intelligence. This trend is expected to drive continued market expansion, strengthen the sovereign AI ecosystem, and accelerate the adoption of enterprise AI and government AI solutions across the U.S.
Accelerating investments in sovereign AI infrastructure are transforming the U.S. sovereign AI market as government agencies and enterprises expand domestic AI computing capabilities. Increasing deployment of AI data centers, sovereign cloud infrastructure, high-performance computing (HPC), AI supercomputers, and AI infrastructure is strengthening national AI readiness and supporting secure AI workloads. Federal funding for sovereign AI platforms, AI chips, GPU infrastructure, and advanced networking technologies is enabling scalable and resilient artificial intelligence infrastructure across the United States. The growing focus on data sovereignty, digital sovereignty, and national AI infrastructure is reducing dependence on foreign cloud providers and enhancing operational resilience. This trend is expected to strengthen the U.S. sovereign AI industry, drive innovation in sovereign AI solutions, and accelerate the adoption of secure AI infrastructure.
Market Dynamics
With the rising investments in sovereign AI infrastructure, the U.S. sovereign AI market is experiencing strong momentum as organizations prioritize secure AI ecosystems, domestic AI computing, and data sovereignty for mission-critical applications. The increasing adoption of sovereign cloud platforms, AI data centers, high-performance computing (HPC), AI supercomputers, and GPU infrastructure is enabling the scalable deployment of artificial intelligence across government and regulated industries. Furthermore, supportive federal policies that promote digital sovereignty, AI governance, responsible AI, cybersecurity, and domestic semiconductor manufacturing are accelerating the commercialization of sovereign AI solutions across the United States. However, substantial capital requirements, limited AI infrastructure capacity, shortages of skilled AI professionals, and interoperability complexities continue to present challenges for widespread sovereign AI adoption. Looking ahead, advancements in generative AI, large language models (LLMs), machine learning, AI accelerators, edge AI, and enterprise AI platforms, combined with expanding public-private partnerships, are expected to strengthen the U.S. sovereign AI ecosystem and create significant long-term growth opportunities.
Increasing federal investments in sovereign AI infrastructure are a primary driver of growth for the U.S. sovereign AI market. Government initiatives supporting AI data centers, high-performance computing (HPC), AI supercomputers, sovereign cloud infrastructure, and advanced AI semiconductor manufacturing are strengthening domestic AI capabilities and reducing reliance on foreign technology ecosystems. Rising demand for data sovereignty, secure AI platforms, trusted artificial intelligence, and mission-critical AI applications across defense, intelligence, healthcare, and public administration is further accelerating market expansion. Public funding and strategic partnerships with hyperscalers, AI developers, and semiconductor companies are enhancing the deployment of sovereign AI solutions while improving national cybersecurity and digital resilience. As investment in AI infrastructure, GPU computing, and enterprise AI continues to grow, the U.S. sovereign AI industry is expected to witness sustained technological advancement and long-term market growth.
High capital investment requirements remain a significant restraint for the U.S. sovereign AI market, limiting the pace of large-scale deployment. Establishing sovereign AI infrastructure, AI data centers, high-performance computing clusters, GPU infrastructure, and secure sovereign cloud environments require substantial financial resources and long implementation timelines. Organizations must also address challenges related to AI infrastructure integration, legacy system modernization, cybersecurity compliance, the availability of a skilled workforce, and energy-intensive computing operations. These costs and operational complexities can delay the adoption of sovereign AI platforms, particularly among smaller government agencies and enterprises with constrained budgets. Consequently, barriers to infrastructure investment and implementation challenges may moderate the near-term growth of the U.S. sovereign AI ecosystem, despite strong long-term demand.
Expanding adoption of sovereign AI solutions across critical industries presents a significant growth opportunity for the U.S. sovereign AI market. Increasing digital transformation initiatives in defense, healthcare, financial services, energy, critical infrastructure, and public administration are creating sustained demand for secure AI platforms, AI-powered analytics, and sovereign cloud computing. Organizations are increasingly investing in generative AI, large language models (LLMs), machine learning, edge AI, and AI cybersecurity to improve operational efficiency while maintaining data residency and regulatory compliance. Growing collaboration between government agencies, cloud providers, AI software vendors, and semiconductor manufacturers is accelerating innovation across the sovereign AI ecosystem and expanding commercialization opportunities. As demand for trusted artificial intelligence, AI infrastructure, and data-sovereign AI applications continues to increase, the market is expected to unlock substantial long-term revenue opportunities.
Market Concentration & Characteristics
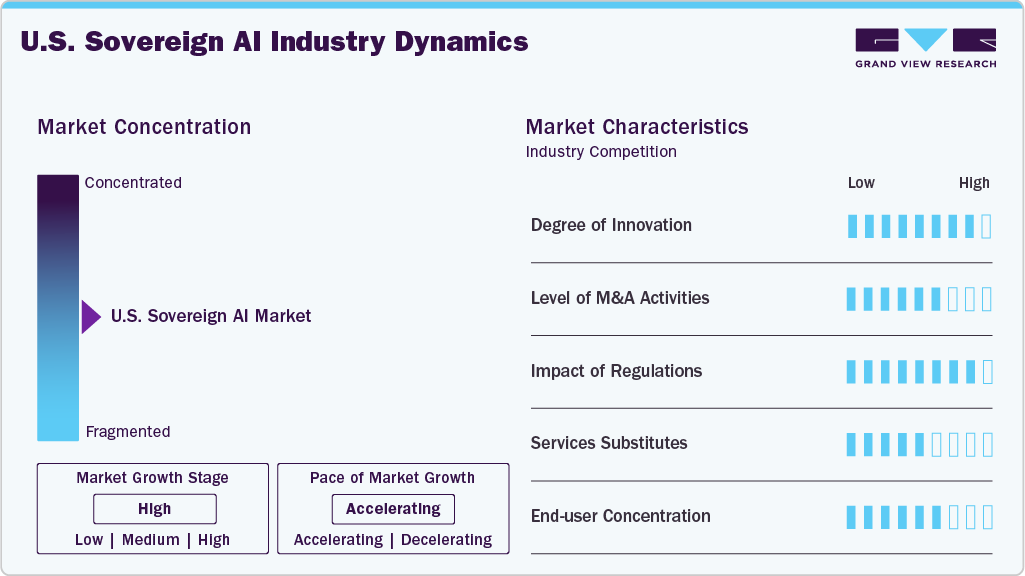
The U.S. sovereign AI market exhibits a moderately concentrated competitive landscape, with leading technology companies, cloud service providers, AI infrastructure vendors, semiconductor manufacturers, and defense-focused solution providers accounting for a significant share of market revenue. The market is characterized by substantial investments in sovereign AI infrastructure, sovereign cloud, AI data centers, high-performance computing (HPC), AI accelerators, and GPU infrastructure, creating high barriers to entry for new participants. Established companies leverage extensive R&D capabilities, proprietary AI models, advanced computing infrastructure, and strategic government partnerships to strengthen their position in the sovereign artificial intelligence market. The increasing demand for secure AI platforms, data sovereignty, trusted AI, and enterprise AI solutions is further intensifying competition among established vendors and emerging AI technology providers.
 To learn more about this report, Download Free Sample Report
The U.S. sovereign AI industry is also characterized by rapid innovation in generative AI, large language models (LLMs), machine learning, edge AI, and AI cybersecurity, enabling vendors to expand their sovereign AI portfolios across mission-critical applications. Strategic collaborations among federal agencies, hyperscalers, semiconductor companies, AI software developers, and research institutions are accelerating the commercialization of sovereign AI solutions while strengthening the domestic AI ecosystem. Market participants are increasingly focusing on AI governance, responsible AI, AI security, regulatory compliance, and interoperable AI infrastructure to differentiate their offerings and address evolving customer requirements. As federal investment in national AI infrastructure and digital sovereignty continues to increase, the market is expected to remain innovation-driven, technology-intensive, and highly competitive throughout the forecast period.
Analyst Perspective
The U.S. sovereign AI market is entering a new phase of growth as federal agencies and regulated industries increase investments in secure, domestically controlled AI capabilities to strengthen national security and technological leadership. Growing deployment of sovereign AI infrastructure, government cloud, AI data centers, high-performance computing (HPC), and AI accelerators is creating a resilient foundation for mission-critical applications. The adoption of generative AI, large language models (LLMs), machine learning, AI governance, and trusted AI is enabling secure, compliant, and high-performance AI ecosystems while addressing data sovereignty and cybersecurity requirements. Strategic collaboration among federal agencies, technology companies, semiconductor manufacturers, and research institutions is accelerating innovation and strengthening the domestic AI value chain. Continued investments in sovereign AI, AI infrastructure, responsible AI, and advanced computing are expected to reinforce U.S. leadership and create substantial long-term growth opportunities.
Component Insights
The hardware segment dominated the U.S. sovereign AI market, accounting for over 48.0% of revenue share in 2025, reflecting the increasing preference for high-performance AI computing infrastructure across government agencies, defense organizations, and regulated industries. The widespread implementation of AI servers, GPU clusters, AI accelerators, high-performance computing (HPC), AI data centers, and sovereign cloud infrastructure has established hardware as the foundation of the market. Growing investments in AI semiconductor manufacturing, advanced processors, high-speed networking, and AI storage systems are enabling organizations to deploy secure and scalable sovereign AI solutions. The expansion of generative AI, large language models (LLMs), machine learning, and AI model training is further increasing the demand for next-generation AI hardware with enhanced computing capabilities. Consequently, continuous modernization of AI infrastructure, digital sovereignty initiatives, and enterprise AI ecosystems is expected to sustain the hardware segment's market leadership throughout the forecast period.
The software segment is projected to witness significant growth during the forecast period, owing to the increasing adoption of sovereign AI software, AI platforms, AI model management, and AI orchestration solutions across government and enterprise environments. Rapid advancements in generative AI, large language models (LLMs), machine learning, natural language processing (NLP), and computer vision are accelerating demand for intelligent software capable of supporting secure and scalable AI deployments. Organizations are increasingly investing in AI governance, responsible AI, AI security, MLOps, AI lifecycle management, and model monitoring to ensure regulatory compliance, transparency, and operational efficiency. The growing integration of sovereign cloud, edge AI, AI analytics, and enterprise AI applications is further expanding the adoption of advanced AI software across defense, healthcare, public administration, and critical infrastructure. As the market continues to evolve, continuous innovation in AI software, foundation models, and sovereign AI platforms is expected to accelerate the segment's growth throughout the forecast period.
Deployment Model Insights
The on-premises segment dominated the U.S. sovereign AI industry, accounting for over 42.0% of revenue in 2025, driven by the growing need for data sovereignty, secure AI infrastructure, and complete control over sensitive government and defense data. Organizations operating in highly regulated sectors continue to prioritize on-premises AI deployment to ensure regulatory compliance, minimize cybersecurity risks, and maintain ownership of mission-critical AI workloads. The expansion of AI data centers, high-performance computing (HPC) infrastructure, GPU clusters, AI supercomputers, and private sovereign cloud environments has further reinforced the adoption of on-premises artificial intelligence solutions. Growing investments in AI cybersecurity, AI governance, enterprise AI, machine learning, and large language models (LLMs) are enabling organizations to deploy advanced AI capabilities within secure domestic environments. The segment is well-positioned to retain its leadership as enterprises continue prioritizing infrastructure ownership, enhanced cybersecurity, regulatory compliance, and mission-critical AI operations.
Cloud deployment is gaining significant momentum in the U.S. sovereign AI market, driven by the growing adoption of cloud-native AI, sovereign cloud platforms, and AI Platform-as-a-Service (AI PaaS) for secure, scalable AI operations. Enterprises and government agencies are leveraging hybrid cloud, multi-cloud environments, and managed AI services to accelerate AI application development while optimizing infrastructure costs and operational efficiency. Continuous advancements in AI orchestration, foundation model hosting, AI inference services, containerized AI workloads, and API-driven AI platforms enable faster deployment and seamless integration of intelligent applications. The growing preference for flexible computing resources, automated software updates, and consumption-based pricing models is encouraging organizations to modernize their AI deployment strategies. These evolving cloud capabilities are strengthening the adoption of cloud-based sovereign AI solutions across regulated industries while expanding opportunities for AI service providers and hyperscale cloud vendors.
Technology Insights
The machine learning segment accounted for a significant revenue share of over 28.0% in 2025, underpinned by the increasing adoption of predictive analytics, intelligent automation, data-driven decision-making, and AI-powered analytics across government agencies and regulated industries. The growing availability of high-quality datasets, advancements in ML algorithms, deep learning frameworks, and model optimization techniques have significantly improved the accuracy and efficiency of sovereign AI applications. Organizations are increasingly integrating machine learning models into cybersecurity, fraud detection, threat intelligence, predictive maintenance, and operational planning to enhance mission-critical decision support. Rising investments in MLOps, AI model lifecycle management, feature engineering, and model monitoring are further accelerating enterprise-scale deployment of machine learning solutions. These technological advancements continue to reinforce the strategic importance of machine learning as a foundational technology within the market.
The generative AI segment is projected to experience substantial growth, fueled by the increasing demand for sovereign large language models (LLMs), foundation models, multimodal AI, and AI copilots capable of operating within secure national environments. Government agencies and enterprises are expanding the adoption of generative AI applications for document intelligence, knowledge management, code generation, content creation, and mission planning while ensuring compliance with data sovereignty and security requirements. Continuous advancements in retrieval-augmented generation (RAG), synthetic data generation, prompt engineering, AI fine-tuning, and domain-specific AI models are improving model accuracy, contextual understanding, and operational efficiency. Increasing investments in trusted AI, responsible AI, and secure model deployment are enabling organizations to accelerate the adoption of generative AI across defense, healthcare, public administration, and critical infrastructure. The expanding use of enterprise generative AI, AI assistants, and intelligent automation is creating new opportunities for innovation and strengthening the role of generative AI within the market.
End-use Insights
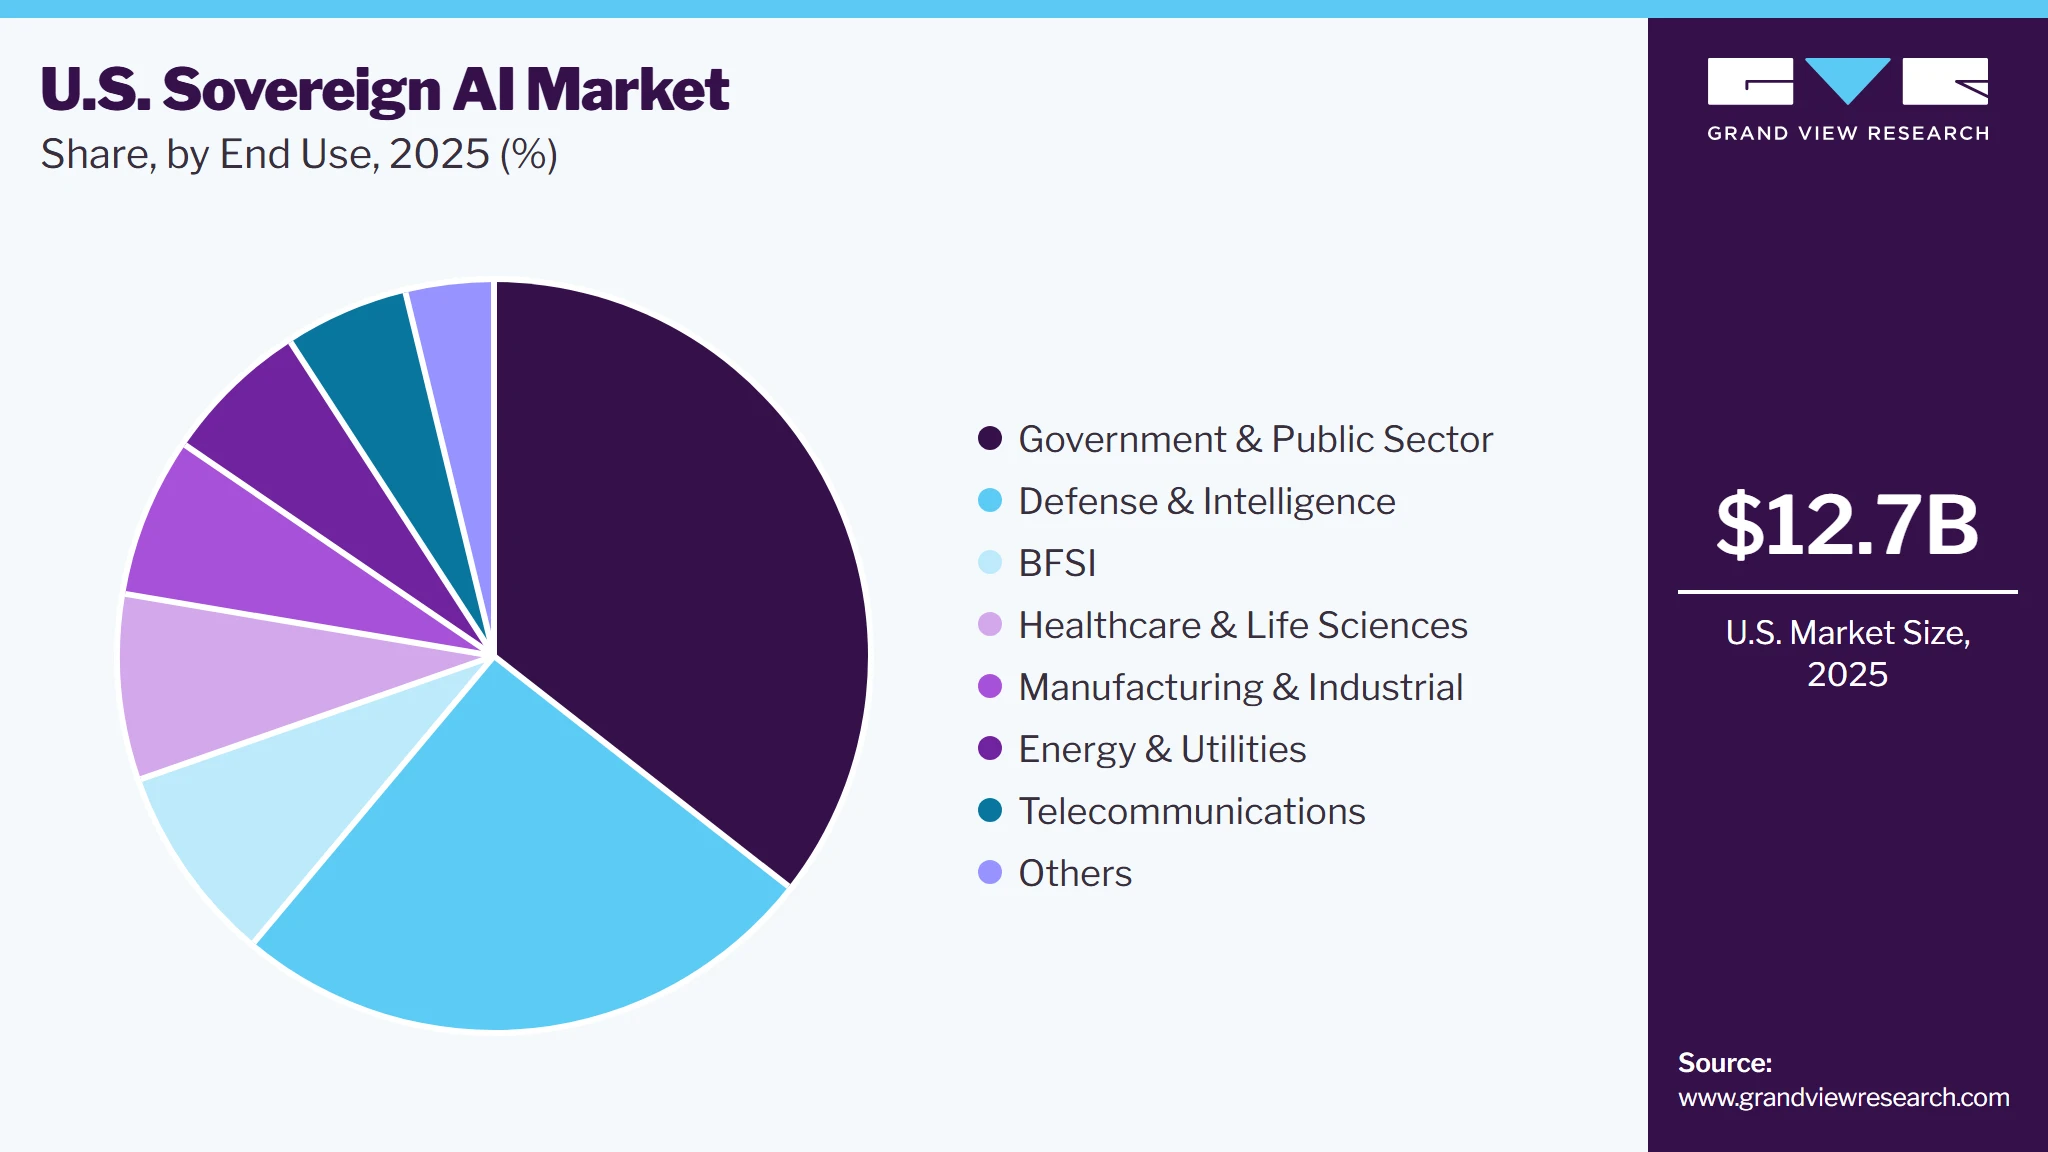
The government and public sector segment dominated the U.S. sovereign AI market, accounting for the largest revenue share of over 35.0% in 2025, supported by increasing investments in national AI initiatives, digital government transformation, and sovereign digital infrastructure to strengthen public-sector innovation and national resilience. Government agencies are expanding the adoption of artificial intelligence for public service delivery, intelligent decision support, citizen services, border security, emergency response, and administrative automation to improve operational efficiency. The growing adoption of AI-powered surveillance, digital identity platforms, intelligence analytics, geospatial analytics, and secure public-sector AI applications is further accelerating technology adoption across federal, state, and local agencies. The growing emphasis on national cybersecurity, critical infrastructure protection, trusted AI, regulatory compliance, and data residency is encouraging public institutions to deploy secure, domestically controlled AI solutions. These strategic investments continue to reinforce the government's position as the leading end user within the market, while creating new opportunities for AI software, infrastructure, and solution providers.
 To learn more about this report, Download Free Sample Report
The telecommunications segment is expected to experience substantial growth during the forecast period, primarily due to the rapid integration of AI-enabled network automation, 5G intelligence, network slicing, and autonomous network management across next-generation communication infrastructure. Telecommunications providers are increasingly deploying AI-driven network optimization, predictive network maintenance, real-time traffic analytics, and intelligent spectrum management to improve network performance, reliability, and service quality. The growing adoption of edge computing, Open RAN, virtualized network functions (VNFs), software-defined networking (SDN), and network function virtualization (NFV) is accelerating AI deployment across telecom operations. Rising demand for cyber threat detection, fraud analytics, customer experience management, and AI-powered service assurance is prompting operators to increase investment in intelligent communication platforms. These advancements are positioning the telecommunications industry as one of the fastest-growing adopters of sovereign AI technologies, creating significant opportunities for AI software providers, network technology vendors, and digital infrastructure developers.
Key U.S. Sovereign AI Company Insights
Some key companies in the U.S. sovereign AI industry are NVIDIA, Microsoft, Amazon Web Services (AWS), Alphabet (Google), IBM, and Oracle.
-
Microsoft operates in the sovereign AI market through Azure Sovereign Cloud, Azure AI services, and secure cloud infrastructure designed for governments and regulated industries. The company specializes in sovereign cloud environments, trusted AI services, data residency, compliance, and enterprise AI deployments that meet national regulatory requirements.
-
Amazon Web Services (AWS) provides sovereign AI capabilities through AWS Sovereign Cloud, dedicated cloud regions, AI and machine learning services, and secure computing infrastructure for public sector and regulated organizations. The company specializes in scalable cloud-based AI infrastructure, sovereign data hosting, secure AI workloads, and compliance-driven AI deployments.
Key U.S. Sovereign AI Companies:
-
NVIDIA Corporation
-
Microsoft Corporation
-
Amazon Web Services (AWS)
-
Alphabet Inc. (Google Cloud)
-
Oracle Corporation
-
International Business Machines Corporation (IBM)
-
Dell Technologies Inc.
-
Hewlett Packard Enterprise (HPE)
-
Cisco Systems, Inc.
-
Palantir Technologies Inc.
-
Intel Corporation
-
Advanced Micro Devices, Inc. (AMD)
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Microsoft Corporation; Amazon Web Services (AWS); Alphabet Inc. (Google Cloud); Oracle Corporation; International Business Machines Corporation (IBM).
- Focus on expanding sovereign AI infrastructure, government cloud, AI platforms, and HPC through federal partnerships and secure AI deployments.
- Strong cloud ecosystems, advanced AI capabilities, established government relationships, large computing infrastructure, and broad AI solution portfolios.
- High infrastructure costs, lengthy government procurement cycles, evolving compliance requirements, and increasing competition from specialized AI providers.
Emerging Players: NVIDIA Corporation; Palantir Technologies Inc.; Hewlett Packard Enterprise (HPE); Dell Technologies Inc.; Cisco Systems, Inc.
- Emphasize AI servers, GPU infrastructure, AI accelerators, edge AI, and sovereign-ready data center solutions supporting national AI initiatives.
- Leadership in AI hardware, semiconductor innovation, high-performance computing, scalable infrastructure, and strategic technology partnerships.
- Limited end-to-end AI software offerings, reliance on hardware demand, and dependence on partnerships for comprehensive sovereign AI solutions.
Recent Developments
-
In June 2026, Palantir Technologies and NVIDIA launched an intelligent engine for deploying NVIDIA Nemotron open models in sovereign environments for U.S. government agencies and critical infrastructure. The solution enables secure AI deployment in classified and air-gapped environments while ensuring full control over data, AI models, and computing infrastructure. This launch strengthens the U.S. sovereign AI market by advancing secure AI adoption across government, defense, and other mission-critical sectors.
-
In March 2026, Hewlett Packard Enterprise (HPE) expanded its sovereign AI infrastructure by deploying the Janus and Tara AI supercomputing systems at Argonne National Laboratory to support the U.S. national AI strategy. The systems enhance AI training, inference, and high-performance computing capabilities while enabling secure, large-scale AI research and scientific innovation. The expansion strengthens the U.S. sovereign AI industry by advancing domestic AI infrastructure, sovereign computing capabilities, and national AI leadership.
U.S. Sovereign AI Market Report Scope
Report Attribute
Details
Market size in 2025
USD 12.7 billion
Estimated market size in 2026
USD 14.7 billion
Projected market size by 2033
USD 46.9 billion
Growth Rate
CAGR of 18.0% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, deployment model, technology, end-use
Key companies profiled
NVIDIA Corporation; Microsoft Corporation; Amazon Web Services (AWS); Alphabet Inc. (Google Cloud); Oracle Corporation; International Business Machines Corporation (IBM); Dell Technologies Inc.; Hewlett Packard Enterprise (HPE); Cisco Systems, Inc.; Palantir Technologies Inc.; Intel Corporation; Advanced Micro Devices, Inc. (AMD)
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Sovereign AI Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the U.S. sovereign AI market report based on component, deployment model, technology, and end-use:
-
Component Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Hardware
-
Software
-
Services
-
-
Deployment Model Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Cloud
-
On premises
-
Hybrid
-
-
Technology Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Generative AI
-
Multimodal AI
-
Machine Learning
-
Computer Vision
-
Natural Language Processing (NLP)
-
Others
-
-
End-use Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Government and Public Sector
-
Defense and Intelligence
-
Healthcare and Life Sciences
-
BFSI
-
Telecommunications
-
Manufacturing and Industrial
-
Energy & Utilities
-
Others
-
Research Methodology
The U.S. sovereign AI market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. sovereign AI segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Component
Revenue capture definition
Hardware
The hardware segment comprises physical computing infrastructure, including AI accelerators, GPUs, CPUs, AI servers, networking equipment, storage systems, and high-performance computing (HPC) resources, used to develop and deploy sovereign AI. It includes dedicated infrastructure that enables secure AI training, inference, and data processing within national jurisdictions.
Software
This segment includes sovereign AI platforms, foundation models, AI development frameworks, orchestration software, analytics tools, and AI governance solutions. It covers software applications that enable secure AI development, deployment, management, and compliance across sovereign environments.
Services
Services include consulting, system integration, deployment, managed services, maintenance, training, and technical support associated with sovereign AI implementations. These services assist organizations in designing, operating, and optimizing secure AI ecosystems throughout their lifecycle.
Segment – Deployment Model
Revenue capture definition
Cloud
The cloud segment consists of sovereign cloud environments that provide scalable AI computing, storage, and application hosting while ensuring compliance with national data regulations. It enables secure access to AI capabilities through cloud-based infrastructure managed within approved jurisdictions.
On-premises
This on-premises segment covers AI infrastructure deployed within an organization's own facilities or government-controlled data centers. It provides maximum control over sensitive data, AI models, and computing resources for highly regulated environments.
Hybrid
Hybrid segment combines on-premises infrastructure with sovereign cloud resources to balance security, scalability, and operational flexibility. It enables organizations to distribute AI workloads according to performance, compliance, and data sensitivity requirements.
Segment – Technology
Revenue capture definition
Generative AI
The generative AI segment includes AI technologies capable of generating text, images, code, audio, video, and other digital content using foundation models and large language models (LLMs). It supports content creation, automation, simulation, and knowledge generation within sovereign AI environments.
Multimodal AI
This multimodal AI segment encompasses AI systems capable of processing and integrating multiple data formats, including text, images, audio, video, and sensor data. It enables richer contextual understanding and more advanced decision-making across complex sovereign AI applications.
Machine Learning
Machine learning refers to AI algorithms that learn from structured and unstructured data to generate predictions, classifications, recommendations, and automated decisions. It forms the core analytical technology supporting intelligent automation and data-driven operations.
Computer Vision
The computer vision segment includes AI technologies that analyze and interpret images, videos, and visual information captured from cameras and sensors. It supports applications such as surveillance, defense, industrial inspection, healthcare imaging, and autonomous systems.
Natural Language Processing (NLP)
This Natural Language Processing (NLP) segment comprises AI technologies that enable machines to understand, interpret, generate, and respond to human language. It supports multilingual communication, document analysis, conversational AI, and intelligent search capabilities.
Others
The others segment includes emerging AI technologies such as reinforcement learning, knowledge graphs, symbolic AI, federated learning, explainable AI, and other specialized AI techniques. These technologies complement core AI capabilities across diverse sovereign AI use cases.
Segment – End Use
Revenue capture definition
Government and Public Sector
The government and public sector segment comprises sovereign AI solutions deployed by government agencies, public institutions, and regulatory bodies to improve public services, digital governance, cybersecurity, and administrative operations. It supports secure AI adoption while maintaining national control over sensitive information.
Defense and Intelligence
This defense and intelligence segment includes AI applications used for military operations, intelligence analysis, surveillance, cybersecurity, command systems, and national security missions. It focuses on highly secure AI capabilities that support strategic defense objectives.
Healthcare and Life Sciences
Healthcare and life sciences cover sovereign AI applications used for medical diagnostics, clinical decision support, biomedical research, drug discovery, healthcare administration, and population health management. The segment emphasizes secure handling of sensitive health and research data.
BFSI
The BFSI segment includes banks, financial institutions, insurers, and payment service providers utilizing sovereign AI for fraud detection, risk management, compliance, customer intelligence, and operational automation. It prioritizes regulatory compliance, financial data protection, and secure AI deployment.
Telecommunications
This telecommunications segment encompasses telecom operators and communication service providers deploying sovereign AI for network optimization, predictive maintenance, cybersecurity, customer service, and intelligent network management. It supports a secure digital communication infrastructure and resilient network operations.
Manufacturing and Industrial
Manufacturing and industrial includes sovereign AI solutions used for production optimization, predictive maintenance, quality inspection, supply chain management, robotics, and industrial automation. The segment focuses on improving operational efficiency while protecting industrial data and intellectual property.
Energy & Utilities
The Energy & Utilities segment consists of AI deployments across electricity, oil & gas, renewable energy, water, and utility operations to optimize asset performance, grid management, predictive maintenance, and energy forecasting. It supports secure management of critical national infrastructure.
Others
This others segment includes sovereign AI deployments across sectors such as retail, education, transportation, agriculture, media, logistics, aerospace, and other industries adopting secure AI technologies. It captures emerging commercial applications beyond the primary end-use industries.
Estimation Model
Layer No.
Layer Name
Key Questions
Description
01
U.S. AI Sovereignty Demand Layer
Who drives demand for sovereign AI?
Identifies demand from U.S. federal agencies, defense organizations, public-sector institutions, and regulated industries. This layer evaluates national AI strategies, data sovereignty requirements, cybersecurity mandates, and digital modernization initiatives.
02
U.S. AI Infrastructure Investment Layer
Where are sovereign AI investments directed?
Assesses investments in AI data centers, HPC, government cloud, AI accelerators, GPU infrastructure, secure networking, and domestic semiconductor capabilities supporting sovereign AI deployment.
03
U.S. AI Platform Adoption Layer
Who adopts sovereign AI technologies?
Measures the adoption of generative AI, LLMs, machine learning, AI governance, and secure AI platforms across government, defense, healthcare, BFSI, telecommunications, manufacturing, and energy sectors.
04
U.S. Sovereign AI Revenue Layer
How is market revenue generated?
Estimates revenue from AI hardware, software, services, government cloud, AI platform licensing, system integration, and managed services across deployment models and end-use industries.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
U.S. Sovereign AI Infrastructure Assessment
Analyzed AI data centers, government cloud, HPC, AI supercomputers, AI accelerators, and domestic semiconductor capabilities.
Identifies infrastructure priorities, AI readiness, and growth opportunities.
Industry-Specific Sovereign AI Adoption
Assessed sovereign AI adoption across government, defense, healthcare, BFSI, telecommunications, manufacturing, and energy sectors.
Provides insights into adoption trends, investment potential, and regulatory landscape.
Generative AI & Sovereign Cloud Analysis
Evaluated generative AI, LLMs, sovereign cloud, foundation models, AI governance, and secure AI platforms.
Supports technology planning, product strategy, and investment decisions.
Frequently Asked Questions About This Report
The global U.S. Sovereign AI market size was valued at USD 12.7 billion in 2025 and is estimated at USD 14.7 billion in 2026.
The U.S. Sovereign AI market is expected to grow at a compound annual growth rate of 18.0% from 2026 to 2033, reaching USD 46.9 billion by 2033.
The hardware segment led with over 48.0% revenue share in 2025, while software is the fastest-growing segment.
The on-premises segment led with over 42.0% revenue share in 2025, while the cloud segment is the fastest-growing.
Key factors driving the market growth include a growing emphasis on national security and technological sovereignty, rising investments in domestic AI infrastructure and data centers, and increasing demand for secure, domestically controlled AI systems.
Some key players operating in the U.S. Sovereign AI market include NVIDIA Corporation, Microsoft Corporation, Amazon Web Services (AWS), Alphabet Inc., Oracle Corporation, International Business Machines Corporation (IBM), Dell Technologies Inc., Hewlett Packard Enterprise (HPE), Cisco Systems, Inc., Palantir Technologies Inc., Intel Corporation, and Advanced Micro Devices, Inc. (AMD).
The machine learning segment led with over 28.0% revenue share in 2025, while generative AI is the fastest-growing segment.
The government segment led with over 35.0% revenue share in 2025, while telecommunications is the fastest-growing segment.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


